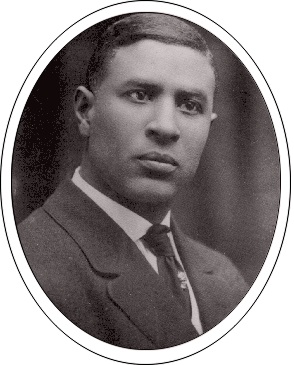
Profile №2 BEHI-P002-GAM
Garrett A. Morgan
1877 (reported)–1963
Inventor, entrepreneur, manufacturer, newspaper publisher, civic leader
Overview
TAKEAWAY: Morgan connected mechanical invention with patents, businesses, manufacturing, and publishing. Patent evidence and commercial results answer different questions.
WHY HE IS IN THE RECORD
Garrett A. Morgan built a career that connected practical invention to intellectual property, manufacturing, business formation, institutional sales, publishing, and civic leadership.
BEHI interprets the assembled record as a repeated economic pathway: identify a problem, develop a solution, secure legal protection, organize production, reach customers, and create commercial value around the invention.
A career linking invention and enterprise
Practical work
Sewing-machine repair and tailoring supplied operating experience before the better-known safety and traffic inventions. Those businesses connect mechanical skill with customers and production.
Protected designs
Four documented U.S. patent grants cover two breathing devices, a traffic signal, and a later de-curling comb. Each grant identifies a particular design rather than ownership of an entire field.
Routes to customers
Advertisements and contemporary reports link products to retailers, demonstrations, and institutional order leads. Adoption and payment require records beyond the patent.
A wider public role
Publishing, civic activity, and the shared rescue record widen the story beyond invention. Family contribution and succession belong alongside the commercial record.
BEHI career map: GM-S001–003, GM-S072, GM-S019, GM-S060, GM-S070, GM-S081, GM-S090. Patent facts are verified; business chronology and contemporary reporting retain their qualifications. The map does not establish company profits or total lifetime earnings.
EXACT ACCOMPLISHMENTS
Established a Cleveland business repairing and selling sewing machines, creating the commercial base for later manufacturing ventures.
Developed and marketed a line of hair-care products through a business serving Black consumers.
Received U.S. Patent Nos. 1,090,936 and 1,113,675 for breathing-device technology associated with the National Safety Device Company.
Received U.S. Patent No. 1,475,024 for a manually operated traffic signal incorporating an all-direction stop interval.
Received U.S. Patent No. 2,762,382 for a de-curling comb, extending his documented patent record into the 1950s.
What Would Move This Profile Forward?
These are the next evidence priorities for strengthening this Profile. Each identifies a concrete research step and what it could help establish.
- Complete the Yonkers procurement trail
Recover municipal authorizations, invoices, delivery and payment records for the reported 1914 safety-hood order. These would distinguish a reported order from fulfilled and paid procurement.
- Locate original Navy procurement evidence
Narrow the identified Navy subject-file leads to Morgan-related contracts, correspondence, shipment and payment records. These would test the reported order without treating an archival location as evidence of adoption.
- Establish traffic-signal transfer terms
Obtain the executed assignment or licensing agreement and related payment evidence. These would clarify what rights changed hands, on what terms, and what was paid.
- Measure business operations and ownership
Recover dated payrolls, order books, accounts and corporate stock records. These would support employee counts and operating scale while clarifying the participants’ legal and financial roles.
Read the Research Gaps & Open Questions for the unresolved issues and evidence limits. New material is reviewed before claims or classifications change.
THE RECEIPTS OR EVIDENCE SUPPORTING THIS PROFILE
Evidence labels apply to individual claims. Read the evidence guide and content-condition definitions.
| SOURCE / LOCATOR | RECORD / CONTEXT | DATE / PERIOD | EVIDENCE STATUS | SUPPORT / LIMITS |
|---|---|---|---|---|
| U.S. Patent No. 1,090,936 | Primary patent record for Morgan's breathing device. | 1914 | VERIFIED | Identifies Morgan as inventor and National Safety Device Company as assignee. |
| U.S. Patent No. 1,113,675 | Second primary patent record covering Morgan breathing-device technology. | 1914 | VERIFIED | Primary intellectual-property evidence. |
| U.S. Patent No. 1,475,024 | Primary patent record for Morgan's improved traffic signal. | 1923 | VERIFIED | Patent describes the device as an improvement in a traffic signal. |
THE FOUR-PATENT RECORD
| SOURCE | PATENT | GRANTED | WHAT THE RECORD ESTABLISHES | CLASSIFICATION |
|---|---|---|---|---|
| GM-S001 | US1090936A | March 24, 1914 | Breathing device; National Safety Device Company named assignee | VERIFIED |
| GM-S002 | US1113675A | October 13, 1914 | Related breathing-device patent; National Safety Device Company named assignee | VERIFIED |
| GM-S003 | US1475024A | November 20, 1923 | Manually operated traffic signal with an all-stop clearance interval | VERIFIED |
| GM-S072 | US2762382A | September 11, 1956 | De-curling comb; application December 11, 1953 | VERIFIED |
SOURCES FOR THIS SECTION
| SOURCE ID | DOCUMENT / SOURCE | DATE | LOCATOR | USE |
|---|---|---|---|---|
| GM-S019 | “Morgan, Garrett A.” Encyclopedia of Cleveland History | Current online edition | Full entry and linked finding aids | Usable with Qualification |
| GM-S060 | “A Man of worth To the Race — G. A. Morgan” | 1916-04-21 | Page 1, far-left column; Institute file Kansas_City_Advocate_1916_04_21_1.pdf | Usable with Qualification |
| GM-S081 | “Test of Two Smoke Helmets” | 1914-09-12 | Page 5; article clipping supplied Aug. 10, 2026 | Usable with Qualification |
| GM-S041 | Inventory and Appraisement — Schedules A–G | 1964-01 | PDF pp. 15–23 | Usable with Qualification |
| GM-S090 | Ordinance No. 86879-A — compensation for Garrett A. and Frank A. Morgan | 1929-09-23; printed 1929-10-02 | Garrett Morgan information.pdf, PDF p. 2; The City Record p. 17 / bound p. 1053 | Usable with Qualification |
Patent ownership, a reported order, a compensation authorization, and an estate appraisal measure different things. The source tables preserve those distinctions.
Background
TAKEAWAY: Morgan’s early repair and tailoring work supplied a foundation for later enterprises. His birth year and some business-opening dates remain unresolved or institutionally attributed.
EARLY LIFE & ORIGINS
Institutional histories commonly give Garrett Augustus Morgan’s birth as March 4, 1877, near Paris, Kentucky; 1879 also appears in the record, and the primary vital-record hierarchy remains unresolved. He received limited formal schooling before leaving home as a teenager and moving first to Cincinnati and then to Cleveland.
In Cleveland, Morgan developed mechanical skill through work with sewing machines. Case Western Reserve University’s institutional history places his independent sewing-machine business in 1907 and tailoring expansion in 1909. The original registrations and opening-date records remain acquisition targets.
Those early businesses gave Morgan a practical foundation in repair, manufacturing, customer service, and entrepreneurship before he moved into hair-care products, safety equipment, patented invention, publishing, and civic activity.
Experience before the celebrated inventions
Migration & identity
Kentucky, Cincinnati, and Cleveland frame the institutional account of his early life. The commonly reported 1877 birth year remains under review alongside 1879; primary records must settle that chronology.
Repair as business knowledge
Sewing-machine work connected diagnosis, maintenance, parts, and customer service. BEHI analysis treats those activities as practical preparation for later enterprise.
An independent base
Case Western Reserve’s chronology dates the sewing-machine business to 1907 and tailoring expansion to 1909. Original registrations, leases, and opening records remain acquisition targets.
Mary Morgan’s contribution
The April 21, 1916 newspaper profile credits his wife’s contribution to his success. The testimony deserves preservation while her exact managerial, financial, and ownership roles remain unresolved.
Sources: GM-S019, Encyclopedia of Cleveland History, and GM-S060, Kansas City Advocate, April 21, 1916, p. 1. Institutional chronology and contemporary assessment are attributed; a reported role is not a reconstructed stockholding or payroll record.
HISTORICAL & ECONOMIC CONTEXT
Cleveland offered expanding opportunities in manufacturing, machinery, transportation, and urban commerce at the turn of the twentieth century.
Black business owners operated within segregated markets while building independent enterprises, products, and customer networks.
Racial discrimination affected access to customers, institutions, and commercial credibility, shaping how Morgan marketed some of his products.
FORMATIVE EXPERIENCES
Born near Paris, Kentucky, into a large family.
Left Kentucky as a teenager and worked while continuing his education informally.
Entered the city that became the center of his business, inventive, and civic life.
Established a sewing-machine repair and sales business.
Opened a tailoring operation and moved from repair work into production and employment.
hands-on repair work and practical engineering experience.
early independent enterprises that taught production and customer markets.
Cleveland’s industrial economy created problems, markets, and opportunities.
Morgan’s inventive career grew out of operating experience, not invention in isolation.
PEOPLE IN THE BUSINESS RECORD
The Kansas City Advocate’s April 21, 1916 profile credited Morgan’s wife with a substantial contribution to his success. BEHI preserves that contemporary attribution while seeking records that establish Mary Hasek Morgan’s exact managerial, financial, or ownership role. It does not assign her an unsupported title or ownership percentage.
The proposed descent from Confederate general John Hunt Morgan is excluded: the institutional history identifies a lack of supporting documents. Exact schooling, teenage migration dates, and early employers remain research questions.
SOURCES FOR THIS SECTION
| SOURCE ID | DOCUMENT / SOURCE | DATE | LOCATOR | USE |
|---|---|---|---|---|
| GM-S019 | “Morgan, Garrett A.” Encyclopedia of Cleveland History | Current online edition | Full entry and linked finding aids | Usable with Qualification |
| GM-S060 | “A Man of worth To the Race — G. A. Morgan” | 1916-04-21 | Page 1, far-left column; Institute file Kansas_City_Advocate_1916_04_21_1.pdf | Usable with Qualification |
The Problem
TAKEAWAY: Morgan addressed hazards in industrial breathing and traffic control. A device’s intended purpose does not by itself establish adoption or use.
THE PROBLEMS HE CONFRONTED
Morgan focused on practical safety and transportation problems created by industrial work and rapidly growing automobile traffic.
Firefighters, tunnel workers, and industrial laborers faced smoke and hazardous fumes with limited protective equipment. Morgan developed breathing-device technology intended to help users operate in those environments.
He also addressed traffic-control problems created by the transition between stop and go movements, patenting an improved signal that incorporated an all-direction stop interval.
Technical solutions had to become usable commercial offers
Smoke & hazardous work
Morgan’s 1914 specifications describe historical breathing-device designs. The design problem, patent claim, demonstration, and actual protection in a particular environment are separate questions.
Changing traffic movements
The 1923 patent addresses the transition between directions by introducing an all-stop interval. Its contribution lies in a specified mechanism rather than inventing traffic control as a whole.
Manufacture & demonstration
A protected design still needed fabrication and an explanation to potential buyers. Demonstration reports can show attention and stated orders, with delivery and settlement requiring further evidence.
Access to institutional markets
The reported Yonkers order provides a concrete procurement lead. Municipal authority, invoices, shipping, and payment records would clarify how technical interest translated into completed commerce.
Source map: GM-S001–003, full patent specifications; GM-S081, September 12, 1914 report of the September 11 demonstration. BEHI analysis connects design, production, and adoption without treating a patent as a safety certification or a reported order as paid revenue.
DIMENSIONS OF THE PROBLEM
Workers and rescuers needed practical protection in smoke- and fume-filled environments.
Growing automobile traffic created dangerous transitions between opposing flows of movement.
A Black inventor still had to persuade institutions and buyers to adopt and purchase his products.
HOW THE PROBLEMS SHOWED UP
Smoke and fumes limited rescue and industrial work.
Protective devices had to be usable, manufacturable, and sellable.
More automobiles increased the need for clearer intersection control.
An invention created little economic value without customers and institutions willing to buy it.
Morgan sometimes adapted sales strategies to overcome racial resistance in the marketplace.
protecting workers and rescuers in dangerous environments.
improving the orderly movement of people and vehicles.
creating products that could be manufactured, sold, and licensed.
Morgan consistently treated practical problems as opportunities for invention and enterprise.
WHAT THE PATENTS CAN ESTABLISH
The 1914 patents describe hood-and-tube breathing devices intended to draw air from lower levels and limit smoke or dust exposure. These are historical designs; a patent is not a modern respirator certification or proof of protection against every gas or oxygen-deficient atmosphere. The traffic patent documents a manually operated signal, not the invention of traffic control or the modern electric three-color light.
SOURCES FOR THIS SECTION
| SOURCE ID | DOCUMENT / SOURCE | DATE | LOCATOR | USE |
|---|---|---|---|---|
| GM-S001 | U.S. Patent No. 1,090,936 — Breathing Device | 1914-03-24 | Full patent; specification, drawings, and claims | Usable |
| GM-S002 | U.S. Patent No. 1,113,675 — Breathing Device | 1914-10-13 | Full patent; specification, drawings, and claims | Usable |
| GM-S003 | U.S. Patent No. 1,475,024 — Traffic Signal | 1923-11-20 | Full patent; specification, drawings, and claims | Usable |
| GM-S023 | U.S. Patent No. 976,939 — Street-Traffic System | 1910-11-29 | Full patent; specification and claims | Usable |
| GM-S025 | U.S. Patent No. 764,709 — Respiratory Apparatus for Firemen or Others | 1904-07-12 | Full patent; specification and claims | Usable |
What He Built
TAKEAWAY: Morgan developed several businesses around technical skill and products. His career extends beyond a single invention or patent.
THE ENTERPRISES HE BUILT
Morgan built a portfolio of businesses around mechanical skill, consumer products, intellectual property, safety equipment, and publishing.
His activities included sewing-machine repair, tailoring and garment production, the G. A. Morgan Hair Refining Company, the National Safety Device Company, patented traffic-control technology, and participation in the Cleveland Call.
The common pattern was not a single invention. It was the repeated movement from problem-solving to products, companies, customers, and commercial value.
Separate enterprises, connected commercial skills
Repair & garment work
Mechanical service and tailoring represent different activities within the early business chronology. Leases, registers, accounts, and payroll would establish their particular scale.
Consumer products
Hair-care marketing and the 1919 advertised comb connect Morgan’s name to a consumer market. An advertisement records the product offer and retailer, rather than sales volume or an associated patent.
Safety-device enterprise
The 1914 patents name National Safety Device Company in the assignment wording. Charter, stock, and company records are needed to establish corporate formation and ownership beyond that patent statement.
Traffic-signal rights
The patented mechanism and the reported General Electric transaction require different evidence. The often-repeated $40,000 amount remains attributed pending the executed agreement and payment record.
Publishing & civic enterprise
Participation in the Cleveland Call adds a communications business to the career. Its ownership, accounts, and later institutional history should retain their own dates and records.
Evidence map: GM-S019, GM-S001–003, GM-S070, and the source tables below. BEHI synthesis: these ventures share skills and relationships, but they are not a verified consolidated company or a single balance sheet.
THE SYSTEM HE CREATED
Built early businesses around sewing-machine repair, sales, tailoring, and garment production.
Developed and marketed hair-care products through the G. A. Morgan Hair Refining Company.
Commercialized breathing-device technology through the National Safety Device Company.
Used patents to protect inventions and create pathways for commercialization and rights transactions.
HOW THE BUSINESS SYSTEM WORKED
Focused on problems in machinery, safety, personal care, or transportation.
Built or refined a product or mechanical device around the problem.
Secured patents for major inventions where appropriate.
Created enterprises to manufacture, market, and distribute products.
Sold to consumers and institutions and, in some cases, monetized rights associated with patented inventions.
independent businesses across several product and service categories.
movement from invention into manufacturing, marketing, and customer sales.
activity across garments, personal care, safety technology, transportation, and media.
Morgan’s record shows invention functioning as one part of a broader entrepreneurial system.
ENTERPRISE EVIDENCE AND ITS LIMITS
| ENTERPRISE / RELATIONSHIP | EVIDENCE CURRENTLY AVAILABLE | WHAT REMAINS UNRESOLVED |
|---|---|---|
| Sewing-machine and garment businesses | Institutional chronology; April 1916 newspaper description of factory and manufacturing activity | Registrations, opening dates, capitalization, payroll and accounts |
| G. A. Morgan Hair Refining Company | April 1916 profile; February 1919 Savannah Tribune product advertisement | Legal formation, formulation rights, manufacturing chain and complete sales record |
| National Safety Device Company | Named assignee in both 1914 patents; Yonkers newspaper report of a six-unit order | Original charter, stock register, officer records, delivery and payment |
| Alexander Dreyfus / Nadsco network | Lisa Cook’s published research and 2018 interview identify Dreyfus as treasurer | Original letterhead; no inferred ownership share, investment amount or unique trustee identities |
| Cleveland Call | CWRU attributes founding about 1920 to a group including Morgan; catalog chronology differs in precision | Mastheads, corporate documents, ownership and financing; avoid sole-founder claims |
SOURCES FOR THIS SECTION
| SOURCE ID | DOCUMENT / SOURCE | DATE | LOCATOR | USE |
|---|---|---|---|---|
| GM-S001 | U.S. Patent No. 1,090,936 — Breathing Device | 1914-03-24 | Full patent; specification, drawings, and claims | Usable |
| GM-S002 | U.S. Patent No. 1,113,675 — Breathing Device | 1914-10-13 | Full patent; specification, drawings, and claims | Usable |
| GM-S060 | “A Man of worth To the Race — G. A. Morgan” | 1916-04-21 | Page 1, far-left column; Institute file Kansas_City_Advocate_1916_04_21_1.pdf | Usable with Qualification |
| GM-S070 | G. A. Morgan Hair Refining Company advertisement — Heavy Metal Hair Pressing Comb and product line | 1919-02-22 | Page 6; advertisement lists Heavy Metal Hair Pressing Comb 'For Pressing and Drying the Hair' and Savannah Pharmacy retailer | Usable with Qualification |
| GM-S036 | “Cleveland Call and Post” | Current online edition | Founding and 1927 merger chronology | Usable with Qualification |
| GM-S086 | Lisa Cook interview: On invention gaps, hate-related violence, discrimination, and more | 2018-10-10 | Lines 59–89, Morgan consumer-discrimination discussion | Usable with Qualification |
Accomplishments
TAKEAWAY: Morgan’s accomplishments include patents and commercial activity across several industries. Claims about procurement and use require evidence beyond the inventions themselves.
DOCUMENTED ACCOMPLISHMENTS
Garrett A. Morgan’s record spans business formation, patented invention, manufacturing, institutional sales, publishing, and civic leadership.
BEHI separates documented accomplishments from later legend by relying on patents, company records, procurement evidence, contemporary reporting, and clearly attributed secondary sources.
An inventive career across four decades
1914 · Hazardous environments
Two breathing-device grants connect Morgan’s safety work to specific patent specifications and drawings: 1,090,936 and 1,113,675.
1923 · Street intersections
The traffic-signal patent describes a manually operated design that stops traffic in every direction before changing the right of way.
1956 · Personal care
The de-curling comb patent records a later invention, showing that his patent activity continued well beyond the better-known safety and traffic designs.
Verified patent records · GM-S001, GM-S002, GM-S003, GM-S072. These grants establish named inventions and issue dates; business success must be demonstrated with additional records.
ACCOMPLISHMENT LEDGER
Built an independent repair and sales business in Cleveland before expanding into other ventures.
Organized the G. A. Morgan Hair Refining Company and marketed Morgan-branded personal-care products.
Received U.S. Patent Nos. 1,090,936 and 1,113,675 for breathing-device technology.
Used the National Safety Device Company to market safety equipment to institutional customers.
Received U.S. Patent No. 1,475,024 for an improved traffic signal with an all-direction stop interval.
Historical sources report a $40,000 transaction involving rights associated with the traffic-signal invention.
created practical technologies around safety, transportation, and personal care.
built and participated in businesses that manufactured, marketed, and sold products.
used patents, companies, and customer relationships to create commercial value.
His significance lies in the repeated movement from problem-solving to enterprise.
ACCOMPLISHMENT CATEGORIES
Built independent businesses across repair, garments, hair care, and safety equipment.
Secured four documented U.S. patents spanning safety, traffic control, and personal-care technology.
Pursued customers including fire departments and other organizational buyers for safety equipment.
Extended his economic activity into Black-owned media and civic institution building.
ADDITIONAL ACCOMPLISHMENTS IN THE EVIDENCE
| EVENT | SUPPORTED FINDING | CLASSIFICATION / LIMIT |
|---|---|---|
| 1914 Yonkers demonstration and order | September 12 Statesman reports a demonstration the previous day and a six-hood order that morning | Contemporary reporting; delivery and payment not established |
| 1916 tunnel rescue | Garrett and Frank Morgan explicitly named in a later primary city ordinance concerning injuries sustained saving G. C. Van Dusen and McNamara | Verified content of ordinance; no fixed personal rescue count |
| 1929 municipal compensation | Ordinance No. 86879-A authorizes $2,000 each for Garrett and Frank Morgan | Verified authorization; actual disbursement requires vouchers |
| 1956 de-curling comb patent | U.S. Patent No. 2,762,382 names Garrett A. Morgan, Sr. | Verified patent; distinct from the 1919 marketed comb and John E. Laing’s 1914 patent |
SOURCES FOR THIS SECTION
| SOURCE ID | DOCUMENT / SOURCE | DATE | LOCATOR | USE |
|---|---|---|---|---|
| GM-S081 | “Test of Two Smoke Helmets” | 1914-09-12 | Page 5; article clipping supplied Aug. 10, 2026 | Usable with Qualification |
| GM-S090 | Ordinance No. 86879-A — compensation for Garrett A. and Frank A. Morgan | 1929-09-23; printed 1929-10-02 | Garrett Morgan information.pdf, PDF p. 2; The City Record p. 17 / bound p. 1053 | Usable with Qualification |
| GM-S072 | U.S. Patent No. 2,762,382 — De-curling comb | 1956-09-11 | Filed 1953-12-11; full specification, claims, and cited prior art | Usable |
| GM-S071 | U.S. Patent No. 1,108,375 — Comb | 1914-08-25 | Full patent; inventor field and specification | Usable |
Economic Impact
TAKEAWAY: Morgan turned technical skill into products and business opportunities. Orders, completed sales, income, and personal wealth must be established separately.
ECONOMIC IMPACT
Morgan’s economic impact came from converting technical skill and intellectual property into businesses, products, customer relationships, and commercial transactions.
His record spans service businesses, garment production, consumer products, safety equipment, institutional procurement, patented technology, publishing, and property investment.
What the estate inventory shows
The 1964 inventory’s gross appraised assets total $12,033.04. Real estate accounts for about 94% of that recorded total.
Court inventory · historical dollars. GM-S041, Case No. 646303, PDF pp. 18–22. Bars show each category’s share of gross assets. This is administered estate property, not lifetime wealth, company valuation, or business revenue; later-discovered assets are outside this snapshot.
Appraisal snapshot
The bars describe categories in the 1964 gross estate inventory. They start at zero and use gross appraised assets as the common denominator; this is not a sales-growth chart.
Commercial transactions
The reported $40,000 rights transaction needs an executed instrument and payment evidence. It should not be added to a later estate appraisal as if both were contemporaneous assets.
Municipal compensation
The 1929 ordinance authorizes $2,000 each for Garrett and Frank Morgan. Authorization and disbursement are different stages; the chart does not include an assumed payment.
Financial reading map: GM-S041, GM-S019/GM-S021, and GM-S090. Historical nominal dollars with distinct dates, parties, and categories; no combined wealth total is implied.
KEY ECONOMIC INDICATORS
Each measure identifies its entity, period, source and evidence limits. Dollar amounts are nominal historical U.S. dollars. Assets, revenue, profit, transaction amounts and employment measures are distinct. “Not yet established” identifies a research gap, not zero or “not applicable.”
| MEASURE / VALUE | ENTITY / PERIOD | SOURCE / LOCATOR | CONTENT CONDITION / EVIDENCE CLASSIFICATION | INTERPRETATION / LIMITS |
|---|---|---|---|---|
| Gross estate assets $12,033.04 | Garrett Morgan probate estate 1964 | GM-S041; supplied probate PDF pp. 15–23, recapitulation p. 22. | Documented VERIFIED | Gross inventory assets, before deductions; not lifetime wealth. |
| Inventory “Net Estate” $9,626.44 | Garrett Morgan probate estate 1964 | GM-S041; inventory and Schedule F, PDF pp. 15–23. | Documented VERIFIED | Inventory-defined net amount; distinct from the $5,304.97 taxable probate figure. |
| Reported workforce 32 workers | Morgan business Date not established in cited summary | 1976 retrospective, p. 67; institutional accounts cited below. | Documented ATTRIBUTED | Retrospective headcount; original payroll and reporting date remain needed. |
| Annual revenue and profit Not yet established | Morgan businesses Reporting period not established | Research gap; see Evidence & Context and Receipts. | Not yet established Evidence classification: not assigned to an unresolved answer. | Requires entity-specific accounts and expense records. Research Gap: Annual revenue and profit |
For evidence-label definitions, see the Receipts evidence guide.
HOW MORGAN CREATED ECONOMIC VALUE
Started with sewing-machine repair and sales.
Moved into tailoring, garments, personal-care products, and safety equipment.
Used patents to formalize ownership of major inventions.
Marketed safety products to fire departments and other organizations.
Historical sources report a $40,000 rights transaction associated with the traffic-signal invention.
Participated in Black-owned publishing and invested in property and other ventures.
created operating enterprises rather than relying only on patent ownership.
sold products to consumers and institutional buyers.
used commercial activity to support additional ventures and assets.
Morgan’s economic significance is best understood as a chain: Problems → Solutions → Intellectual Property → Products → Companies → Customers → Capital.
CHANNELS OF ECONOMIC IMPACT
Operated businesses that involved repair, garment production, manufacturing, and product distribution.
Marketed hair-care and personal-care products to Black consumers.
Pursued organizational customers for safety equipment, including documented fire-department interest and orders.
Used patents as economic assets that could support products, companies, and reported rights transactions.
DOCUMENTED ESTATE AND MUNICIPAL FIGURES
| MEASURE | HISTORICAL DOLLARS | RECORD LOCATOR | INTERPRETATION / LIMIT |
|---|---|---|---|
| Gross appraised estate assets | $12,033.04 | Inventory recapitulation, PDF p. 22 | Historical probate appraisal; not lifetime wealth |
| Real estate | $11,295.00 | Schedules E and recapitulation, PDF pp. 20–22 | Property administered through this estate |
| Personal goods | $300.00 | Schedule A, PDF p. 18 | 1954 Cadillac $200; desk, safe and effects $100 |
| Bank deposits | $438.04 | Schedule B, PDF p. 18 | Cleveland Trust $420 + $11.04; Wakeman Bank $7 |
| Statutory Schedule F set-aside | $2,406.60 | PDF p. 22 | Distinct from gross assets and other administration deductions |
| Inventory “Net Estate” | $9,626.44 | PDF p. 22 | After Schedule F set-aside |
| Inheritance-tax deductions | $6,728.07 | Tax recapitulation, PDF p. 36 | Tax calculation, not business expenses |
| Net taxable probate property | $5,304.97 | Tax recapitulation, PDF p. 36 | Not interchangeable with inventory net estate |
| Garrett Morgan compensation authorization | $2,000 | 1929 city ordinance, packet PDF p. 2 | Authorization; payment record not acquired |
| Frank Morgan compensation authorization | $2,000 | Same ordinance | Separate recipient; do not combine as Garrett’s income |
No inflation conversion, lifetime net worth, business valuation, royalty estimate, or canceled-order loss is inferred from these amounts. A later after-discovered bank-account proceeding is documented, but its handwritten cents remain qualified.
The 32-worker figure appears in Peter Jedick’s August 1976 retrospective article, p. 67, as well as later institutional biographies. That establishes circulation by 1976; repetition does not establish a verified payroll count. The reported $40,000 General Electric transaction remains attributed until the executed rights instrument and payment evidence are acquired.
SOURCES FOR THIS SECTION
| SOURCE ID | DOCUMENT / SOURCE | DATE | LOCATOR | USE |
|---|---|---|---|---|
| GM-S041 | Inventory and Appraisement — Schedules A–G | 1964-01 | PDF pp. 15–23 | Usable with Qualification |
| GM-S043 | Ohio Resident Inheritance Tax Return and Recapitulation | 1964-06 | PDF pp. 33–36 | Usable with Qualification |
| GM-S046 | Application and Entry Relieving Estate from Administration — Cleveland Trust Checking Account | 1978-12-29 to 1979-01-23 | PDF pp. 47–54 | Usable with Qualification |
| GM-S090 | Ordinance No. 86879-A — compensation for Garrett A. and Frank A. Morgan | 1929-09-23; printed 1929-10-02 | Garrett Morgan information.pdf, PDF p. 2; The City Record p. 17 / bound p. 1053 | Usable with Qualification |
| GM-S093 | Peter Jedick, Cleveland’s Black Edison | 1976-08 | Garrett Morgan information.pdf, PDF pp. 3–8; Cleveland magazine pp. 64, 66–70 | Usable with Qualification |
| GM-S019 | “Morgan, Garrett A.” Encyclopedia of Cleveland History | Current online edition | Full entry and linked finding aids | Usable with Qualification |
| GM-S021 | “Of Courage and Caution” | Current online edition | Full article and bibliography | Usable with Qualification |
Timeline
TAKEAWAY: The chronology distinguishes patent grants, events, newspaper reports, and later administrative actions. Early business dates retain their institutional attribution.
CHRONOLOGY AND DOCUMENT DATES
This chronology distinguishes an event date, a patent grant, a newspaper publication and a later administrative action. Early business dates are attributed to institutional histories; document-backed milestones are listed below.
Milestones anchored to documents
- 1914Two breathing-device patents
March 24 and October 13 grants formalize the safety inventions.
- 1916Tunnel rescue
The July 24–25 disaster is distinct from the later compensation action.
- 1919Consumer marketing
A February advertisement connects a Morgan comb to a Savannah retailer.
- 1923Traffic-signal patent
The November 20 grant documents the all-stop design.
- 1929Municipal authorization
The city authorizes separate amounts for Garrett and Frank Morgan.
- 1956Later patent activity
The September 11 grant records a separate de-curling comb.
Sources: GM-S001, GM-S002, GM-S003, GM-S070, GM-S072 and GM-S090. Patent dates, advertisement dates, event dates, and authorization dates describe different kinds of milestones; the detailed chronology below preserves those distinctions.
DATED EVIDENCE
| DATE | EVENT | WHAT THE DOCUMENT ESTABLISHES | EVIDENCE BASIS |
|---|---|---|---|
| March 24, 1914 | Breathing Device Patent No. 1,090,936 Granted | U.S. Patent No. 1,090,936 for a breathing device was granted to Garrett A. Morgan. | Primary patent |
| September 11–12, 1914 | Yonkers Demonstration and Reported Six-Unit Safety Hood Order | Statesman issue dated September 12 reports a demonstration “yesterday” (September 11) and a six-hood order that morning. Delivery and payment remain unverified. | Contemporary report / qualified |
| October 13, 1914 | Breathing Device Patent No. 1,113,675 Granted | U.S. Patent No. 1,113,675 for a related breathing device was granted to Garrett A. Morgan. | Primary patent |
| July 24–25, 1916 | Cleveland Waterworks Tunnel Rescue | Morgan and his safety equipment participated in rescue and recovery efforts during the Cleveland waterworks tunnel disaster. Personal rescue counts remain disputed and are not stated here. | Contemporary report / qualified |
| February 22, 1919 | Heavy Metal Hair Pressing Comb Advertised | A G. A. Morgan Hair Refining Company advertisement marketed the Heavy Metal Hair Pressing Comb and related products; the advertisement also identified a Savannah retail outlet. | Contemporary report / qualified |
| November 20, 1923 | Traffic Signal Patent No. 1,475,024 Granted | U.S. Patent No. 1,475,024 for Morgan’s Traffic Signal was granted, documenting a manually operated design with an all-stop clearance interval. | Primary patent |
| September 23, 1929 | Compensation authorized for Garrett and Frank Morgan | City ordinance authorizes $2,000 each; published October 2. Printed effective date November 3. No payment voucher reviewed. | Primary municipal authorization |
| June 1955 | Garrett A. Morgan Executes Will | Morgan executed a will naming Mary A. Morgan and sons Garrett Jr., John P., and Cosmo H. as principal beneficiaries and establishing testamentary shares. | Documented proceeding |
| September 11, 1956 | De-Curling Comb Patent No. 2,762,382 Granted | U.S. Patent No. 2,762,382 for a de-curling comb was granted to Garrett A. Morgan, Sr. | Primary patent |
| July 27, 1963 | Garrett A. Morgan Dies in Cleveland | Probate applications state that Garrett A. Morgan died at the Cleveland Clinic in Cleveland, Ohio. | Documented proceeding |
| 1964 | Morgan Estate Inventory and Distribution | Cuyahoga County probate records inventoried and distributed Morgan’s administered estate, including real estate, personal property, a vehicle, and bank deposits. | Documented proceeding |
| 1977 | Successor Executor Proceeding | John P. Morgan was appointed successor executor; the fiduciary account states the earlier estate administration had already been completed and no new receipts or disbursements came into his hands. | Documented proceeding |
| January 1979 | After-Discovered Cleveland Trust Account Released | A Cuyahoga County proceeding released an after-discovered Cleveland Trust checking account to Cosmo H. Morgan; the exact cents remain qualified because of scan legibility. | Documented proceeding |
SOURCES FOR THIS SECTION
| SOURCE ID | DOCUMENT / SOURCE | DATE | LOCATOR | USE |
|---|---|---|---|---|
| GM-S001 | U.S. Patent No. 1,090,936 — Breathing Device | 1914-03-24 | Full patent; specification, drawings, and claims | Usable |
| GM-S002 | U.S. Patent No. 1,113,675 — Breathing Device | 1914-10-13 | Full patent; specification, drawings, and claims | Usable |
| GM-S003 | U.S. Patent No. 1,475,024 — Traffic Signal | 1923-11-20 | Full patent; specification, drawings, and claims | Usable |
| GM-S072 | U.S. Patent No. 2,762,382 — De-curling comb | 1956-09-11 | Filed 1953-12-11; full specification, claims, and cited prior art | Usable |
| GM-S081 | “Test of Two Smoke Helmets” | 1914-09-12 | Page 5; article clipping supplied Aug. 10, 2026 | Usable with Qualification |
| GM-S090 | Ordinance No. 86879-A — compensation for Garrett A. and Frank A. Morgan | 1929-09-23; printed 1929-10-02 | Garrett Morgan information.pdf, PDF p. 2; The City Record p. 17 / bound p. 1053 | Usable with Qualification |
| GM-S015 | Estate of Garrett A. Morgan Sr. — complete record set supplied for Case No. 646303 | 1963–1979 | 56-page court-supplied scan; pages 1–56 | Usable with Qualification |
| GM-S070 | G. A. Morgan Hair Refining Company advertisement — Heavy Metal Hair Pressing Comb and product line | 1919-02-22 | Page 6; advertisement lists Heavy Metal Hair Pressing Comb 'For Pressing and Drying the Hair' and Savannah Pharmacy retailer | Usable with Qualification |
CHRONOLOGICAL RECORD
-
March 24, 1914
Breathing Device Patent No. 1,090,936 Granted
Garrett A. Morgan / National Safety Device Company
U.S. Patent No. 1,090,936 for a breathing device was granted to Garrett A. Morgan. -
September 11–12, 1914
Yonkers Demonstration and Reported Six-Unit Safety Hood Order
Yonkers Fire Department / National Safety Device Company
The September 12 Yonkers Statesman reports a safety-hood demonstration 'yesterday' (September 11) and a six-unit fire-department order that morning. Municipal purchase authorization, delivery and payment remain unverified. -
October 13, 1914
Breathing Device Patent No. 1,113,675 Granted
Garrett A. Morgan / National Safety Device Company
U.S. Patent No. 1,113,675 for a related breathing device was granted to Garrett A. Morgan. -
July 24–25, 1916
Cleveland Waterworks Tunnel Rescue
Garrett A. Morgan / Cleveland Waterworks rescue effort
Morgan and his safety equipment participated in rescue and recovery efforts during the Cleveland waterworks tunnel disaster. Personal rescue counts remain disputed and are not stated here. -
February 22, 1919
Heavy Metal Hair Pressing Comb Advertised
G. A. Morgan Hair Refining Company
A G. A. Morgan Hair Refining Company advertisement marketed the Heavy Metal Hair Pressing Comb and related products; the advertisement also identified a Savannah retail outlet. -
November 20, 1923
Traffic Signal Patent No. 1,475,024 Granted
Garrett A. Morgan
U.S. Patent No. 1,475,024 for Morgan’s Traffic Signal was granted, documenting a manually operated design with an all-stop clearance interval. -
June 1955
Garrett A. Morgan Executes Will
Garrett A. Morgan
Morgan executed a will naming Mary A. Morgan and sons Garrett Jr., John P., and Cosmo H. as principal beneficiaries and establishing testamentary shares. -
September 11, 1956
De-Curling Comb Patent No. 2,762,382 Granted
Garrett A. Morgan, Sr.
U.S. Patent No. 2,762,382 for a de-curling comb was granted to Garrett A. Morgan, Sr. -
July 27, 1963
Garrett A. Morgan Dies in Cleveland
Garrett A. Morgan
Probate applications state that Garrett A. Morgan died at the Cleveland Clinic in Cleveland, Ohio. -
1964
Morgan Estate Inventory and Distribution
Estate of Garrett A. Morgan Sr.
Cuyahoga County probate records inventoried and distributed Morgan’s administered estate, including real estate, personal property, a vehicle, and bank deposits. -
1977
Successor Executor Proceeding
Estate of Garrett A. Morgan Sr.
John P. Morgan was appointed successor executor; the fiduciary account states the earlier estate administration had already been completed and no new receipts or disbursements came into his hands. -
January 1979
After-Discovered Cleveland Trust Account Released
Estate of Garrett A. Morgan Sr.
A Cuyahoga County proceeding released an after-discovered Cleveland Trust checking account to Cosmo H. Morgan; the exact cents remain qualified because of scan legibility.
Myths & Disputes
TAKEAWAY: Morgan’s documented inventions should be described precisely. A patent or published account does not verify every later claim about invention priority, adoption, or payment.
MYTHS, DISPUTES AND LIMITS
Corrections protect Morgan’s documented achievements from claims that exceed the evidence. A source’s existence does not verify every assertion printed within it.
What Morgan’s traffic signal actually added
The patented mechanism introduces a clearance interval when the right of way changes:
1 · One direction proceeds
The operator allows traffic along one direction to move.
2 · All directions stop
The signal pauses every approach, giving vehicles already in the intersection time to clear.
3 · Right of way changes
The operator turns the indicators and allows the other direction to proceed.
Explanatory sequence based on U.S. Patent No. 1,475,024 · GM-S003. This is a simplified explanation of the manually operated design, not a reconstruction of its hardware. The patent establishes a specific improvement; it does not establish invention of the first traffic light or the modern three-color signal.
CLAIM AND CORRECTION
| CLAIM REQUIRING CARE | BEHI CORRECTION | SOURCE BASIS |
|---|---|---|
| Morgan invented the first traffic light | Earlier traffic-control patents predate Morgan. His 1923 patent documents a particular improved, manually operated signal. | GM-S003; GM-S023; GM-S024 |
| Morgan invented the gas mask | Earlier protective-device patents existed. Credit the two specified 1914 breathing-device patents; avoid universal first-invention language. | GM-S001; GM-S002; GM-S025–027 |
| The 1956 comb patent proves the 1919 product was patented | The 1919 advertisement does not identify a patent. Laing’s 1914 comb patent is not Morgan’s; Morgan’s 1956 patent is a separate record. | GM-S070; GM-S071; GM-S072 |
| Morgan alone saved a fixed number of men | Preserve the roles of Frank Morgan and other participants. Do not merge rescue, recovery and the full team’s work into a personal count. | GM-S090; GM-S033 |
| More than 100 cities are verified customers | The Yonkers article quotes Chief Mulcahey making this statement. It is attribution evidence, not a municipal customer register. | GM-S081 |
| A newspaper order proves delivery and payment | The six-hood order is contemporary reporting; original procurement and fulfillment records remain outstanding. | GM-S081 |
| The GE payment and cancellation losses are fully verified | The $40,000 story remains attributed. No executed agreement, payment instrument or quantified cancellation-loss record has been reviewed. | GM-S004; GM-S021; GM-S073 |
| Probate proves lifetime wealth or a millionaire fortune | Estate appraisal, statutory set-aside and taxable estate are different administrative measures, not lifetime net worth or business value. | GM-S041; GM-S043 |
| The Confederate-general genealogy is established | Exclude this assertion as fact. The institutional history identifies a lack of supporting historical documents. | GM-S019 |
| The profile’s interpretation is itself a verified document fact | The inventor-entrepreneur model and broad economic significance are BEHI analysis built from individual sources. | Institute Analysis |
SOURCES FOR THIS SECTION
| SOURCE ID | DOCUMENT / SOURCE | DATE | LOCATOR | USE |
|---|---|---|---|---|
| GM-S003 | U.S. Patent No. 1,475,024 — Traffic Signal | 1923-11-20 | Full patent; specification, drawings, and claims | Usable |
| GM-S023 | U.S. Patent No. 976,939 — Street-Traffic System | 1910-11-29 | Full patent; specification and claims | Usable |
| GM-S001 | U.S. Patent No. 1,090,936 — Breathing Device | 1914-03-24 | Full patent; specification, drawings, and claims | Usable |
| GM-S025 | U.S. Patent No. 764,709 — Respiratory Apparatus for Firemen or Others | 1904-07-12 | Full patent; specification and claims | Usable |
| GM-S019 | “Morgan, Garrett A.” Encyclopedia of Cleveland History | Current online edition | Full entry and linked finding aids | Usable with Qualification |
| GM-S081 | “Test of Two Smoke Helmets” | 1914-09-12 | Page 5; article clipping supplied Aug. 10, 2026 | Usable with Qualification |
| GM-S090 | Ordinance No. 86879-A — compensation for Garrett A. and Frank A. Morgan | 1929-09-23; printed 1929-10-02 | Garrett Morgan information.pdf, PDF p. 2; The City Record p. 17 / bound p. 1053 | Usable with Qualification |
| GM-S041 | Inventory and Appraisement — Schedules A–G | 1964-01 | PDF pp. 15–23 | Usable with Qualification |
Claim Review & Corrections
| CLAIM / ASSERTION | HISTORICAL CLARIFICATION & CORRECTION | CLAIM STATUS | RECEIPT |
|---|---|---|---|
|
◆
Safety Hood Patent Issued — U.S. Patent No. 1,090,936 (1914)
“Garrett A. Morgan was granted U.S. Patent No. 1,090,936 for a breathing device on March 24, 1914.”
|
|
Verified | |
|
◆
Breathing Device Patent Issued — U.S. Patent No. 1,113,675 (1914)
“Garrett A. Morgan was granted U.S. Patent No. 1,113,675 for a related breathing device on October 13, 1914; the patent identifies Morgan as inventor and National Safety Device Company as assignee.”
|
Receipts → Documents: Breathing-device patent, 1914 — preview, full file, citation, evidence classification and rights. Read the document’s limits before applying it to this claim. |
Verified | |
|
◆
Yonkers Fire Department Ordered Six Morgan Safety Hoods (1914)
“The Yonkers Statesman of September 12, 1914 reports that, after a demonstration on September 11, Fire Chief James J. Mulcahey ordered six Morgan Safety Hoods on September 12.”
|
Contemporary reported order; municipal purchase authorization, delivery and payment remain unverified.
|
Attributed | |
|
◆
Morgan Safety Hood Used in Cleveland Waterworks Tunnel Rescue (1916)
“Garrett A. Morgan brought his safety hood to the Cleveland waterworks tunnel disaster during the night of July 24–25, 1916, and the equipment was used in rescue and recovery efforts.”
|
|
Attributed | |
|
◆
Traffic Signal Patent Issued — U.S. Patent No. 1,475,024 (1923)
“Garrett A. Morgan was granted U.S. Patent No. 1,475,024 for a Traffic Signal on November 20, 1923, based on an application filed February 27, 1922.”
|
Receipts → Documents: Traffic signal patent, 1923 — preview, full file, citation, evidence classification and rights. Read the document’s limits before applying it to this claim. |
Verified | |
|
◆
GM-C016 — Morgan invented the gas mask.
“Morgan invented the gas mask.”
|
Do not publish “invented the gas mask.” Approved concept: Morgan patented and marketed specific smoke-hood/breathing-device improvements within an older respiratory-protection field.
|
Disputed | |
|
◆
GM-C017 — Morgan’s safety hood filtered poison gas.
“Morgan’s safety hood filtered poison gas.”
|
The patents describe drawing comparatively cleaner air from a low level, clearing foul air, and in one design moist absorbent material that retards smoke/dust. They do not establish broad chemical poison-gas filtration.
|
Disputed | |
|
◆
GM-C018 — Protective breathing devices, smoke hoods, respirators, and mine-safety systems existed before Morgan’s patents.
“Protective breathing devices, smoke hoods, respirators, and mine-safety systems existed before Morgan’s patents.”
|
Verified at the broad-priority level: respiratory apparatus, smoke helmets, and firemen’s air-supply devices predated Morgan. Detailed technical lineage remains separate.
|
Verified | |
|
◆
GM-C027 — Morgan invented the three-way traffic light.
“Morgan invented the three-way traffic light.”
|
Do not publish “invented the three-way traffic light” as a priority claim. Morgan patented a specific manually operated traffic signal with an all-stop position.
Receipts → Documents: Traffic signal patent, 1923 — preview, full file, citation, evidence classification and rights. Read the document’s limits before applying it to this claim. |
Disputed | |
|
◆
GM-C028 — Morgan invented the caution signal used in modern traffic lights.
“Morgan invented the caution signal used in modern traffic lights.”
|
Do not equate the all-stop position with inventing the modern yellow/caution light. Describe the patented clearance function precisely.
Receipts → Documents: Traffic signal patent, 1923 — preview, full file, citation, evidence classification and rights. Read the document’s limits before applying it to this claim. |
Disputed | |
|
◆
GM-C029 — Traffic-control devices and patents addressing stop, go, caution, or clearance intervals existed before Morgan’s filing.
“Traffic-control devices and patents addressing stop, go, caution, or clearance intervals existed before Morgan’s filing.”
|
Verified: patented street/municipal traffic-control systems existed before Morgan’s 1922 filing.
|
Verified | |
|
◆
GM-C030 — Morgan’s patent included a temporary all-stop position intended to clear an intersection before traffic changed direction.
“Morgan’s patent included a temporary all-stop position intended to clear an intersection before traffic changed direction.”
|
Verified: the patent describes stopping traffic in all directions momentarily before permitting movement in one direction.
Receipts → Documents: Traffic signal patent, 1923 — preview, full file, citation, evidence classification and rights. Read the document’s limits before applying it to this claim. |
Verified | |
|
◆
GM-C037 — Probate records document that Morgan held Cleveland and Huron County real estate, a 1954 Cadillac, personal effects, and bank deposits at death.
“Probate records document that Morgan held Cleveland and Huron County real estate, a 1954 Cadillac, personal effects, and bank deposits at death.”
|
Verified as holdings administered at death: Cleveland real estate appraised at $8,750; Huron County property at $2,545; 1954 Cadillac at $200; other personal effects at $100; deposits at $438.04. Property use, acquisition dates, title history, and lifetime peak holdings still require deed, tax, and directory research.
|
Verified | |
|
◆
GM-C046 — Morgan died on July 27, 1963, at the Cleveland Clinic in Cleveland, Ohio.
“Morgan died on July 27, 1963, at the Cleveland Clinic in Cleveland, Ohio.”
|
Multiple court filings within the probate file state the same death date and Cleveland location. The certified death certificate remains desirable as an independent vital record and for parentage, occupation, burial, and informant fields.
|
Verified | |
|
◆
GM-C047 — Morgan’s probate records establish the composition and appraised value of assets administered in his estate.
“Morgan’s probate records establish the composition and appraised value of assets administered in his estate.”
|
The principal 1964 estate reported gross appraised assets of $12,033.04: $11,295 real estate, $300 tangible personal property, and $438.04 deposits. The inventory reported a $9,626.44 net estate after the statutory set-aside; the inheritance-tax return reported $5,304.97 net taxable probate property after deductions. A small after-discovered account was handled in 1979. None of these figures is lifetime wealth, peak net worth, or enterprise valuation.
|
Verified | |
|
◆
GM-C048 — Morgan executed a will in 1955 naming Mary A. Morgan and sons Garrett Jr., John P., and Cosmo H. as principal beneficiaries.
“Morgan executed a will in 1955 naming Mary A. Morgan and sons Garrett Jr., John P., and Cosmo H. as principal beneficiaries.”
|
The will and probate applications identify Mary as spouse and Garrett Jr., John, and Cosmo as sons. This does not independently resolve Morgan's parentage or every genealogical claim.
|
Verified | |
|
◆
GM-C049 — Morgan’s will and 1964 transfer entries passed his real estate in one-third shares to Mary and Garrett Jr. and one-sixth shares to John and Cosmo, subject to the will’s terms.
“Morgan’s will and 1964 transfer entries passed his real estate in one-third shares to Mary and Garrett Jr. and one-sixth shares to John and Cosmo, subject to the will’s terms.”
|
The 5202 Harlem property was also subject to Henry Lucille Rodgers's life-occupancy provision and a ten-year no-sale/no-mortgage restriction. The probate record establishes testamentary transfer, not later ownership duration or property performance.
|
Verified | |
|
◆
GM-C050 — The principal administration of Morgan’s estate was completed by 1964; a 1977 successor-executor proceeding produced no additional receipts or disbursements.
“The principal administration of Morgan’s estate was completed by 1964; a 1977 successor-executor proceeding produced no additional receipts or disbursements.”
|
John P. Morgan's 1977 account states that the file showed the earlier administration was complete and that no assets or debts came into his hands. A separate after-discovered account was later handled in 1979.
|
Verified | |
|
◆
GM-C051 — An after-discovered Cleveland Trust checking account was released to Cosmo H. Morgan through a 1979 proceeding.
“An after-discovered Cleveland Trust checking account was released to Cosmo H. Morgan through a 1979 proceeding.”
|
The account number and recipient are legible. The corrected amount appears to be approximately $474.79, but exact cents should remain unpublished until a clearer copy or bank record is obtained.
|
Attributed | |
|
◆
GM-C052 — By April 1916, a contemporary Black newspaper profile described Morgan as operating from his own factory and associated him with multiple manufacturing enterprises.
“By April 1916, a contemporary Black newspaper profile described Morgan as operating from his own factory and associated him with multiple manufacturing enterprises.”
|
Usable only as attributed contemporary reporting. The statement is important because it predates the July 1916 tunnel disaster and captures Morgan's public economic identity before that event.
|
Attributed | |
|
◆
GM-C054 — A 1916 newspaper profile reported that Morgan lost an employment position because of his race.
“A 1916 newspaper profile reported that Morgan lost an employment position because of his race.”
|
May be used only with attribution to the 1916 profile unless independently corroborated. Do not convert the article's assertion into unqualified causal fact.
|
Attributed | |
|
◆
GM-C057 — A 1916 profile publicly credited Morgan’s wife with substantial contribution to his success.
“A 1916 profile publicly credited Morgan's wife with substantial contribution to his success.”
|
Useful for preserving spouse contribution in the research record, but not enough to assign Mary Morgan a specific legal or managerial role.
|
Attributed | |
|
◆
GM-C061 — By February 1919, the G. A. Morgan Hair Refining Company marketed a ‘G. A. Morgan Heavy Metal Hair Pressing Comb’ for pressing and drying hair.
“By February 1919, the G. A. Morgan Hair Refining Company marketed a 'G. A. Morgan Heavy Metal Hair Pressing Comb' for pressing and drying hair.”
|
Verified as a marketed Morgan-branded product. Do not state that it embodied U.S. Patent 1,108,375: that patent belongs to John E. Laing. Morgan's later U.S. Patent 2,762,382 (1956) is a separate de-curling comb patent and cites Laing's 1914 patent as prior art. The 1919 product's patent status and exact technical construction remain unresolved.
|
Verified | |
|
◆
GM-C062 — Following the July 1916 Cleveland tunnel disaster, fire departments placed new orders for Morgan safety hoods.
“Following the July 1916 Cleveland tunnel disaster, fire departments placed new orders for Morgan safety hoods.”
|
General post-disaster demand increase is strongly supported institutionally. Publication should remain attributed/qualified until named transactions are reconstructed. Do not use phrases such as 'orders poured in' quantitatively unless the underlying order record is found.
|
Attributed | |
|
◆
GM-C066 — The 1914 Yonkers article cited by USPTO as appearing in ‘The Herald Statesman’ requires title correction because The Herald Statesman began publication in 1932.
“The 1914 Yonkers article cited by USPTO as appearing in 'The Herald Statesman' requires title correction because The Herald Statesman began publication in 1932.”
|
YPL supplied the clipping and confirmed that the database file labeled 'The Herald Statesman' was actually from The Yonkers Herald. Correct citation: 'New Style Helmets for Local Fire Fighters,' The Yonkers Herald, Sept. 12, 1914, p.1.
|
Verified | |
|
◆
GM-C068 — Alexander Dreyfus was listed as treasurer of the National Safety Device Company on company letterhead used in Morgan’s white-facing safety-device business.
“Alexander Dreyfus was listed as treasurer of the National Safety Device Company on company letterhead used in Morgan's white-facing safety-device business.”
|
Cook specifically names Alexander Dreyfus and title 'treasurer.' Publish only with attribution to Cook until original company/corporate record is acquired. Do not infer investment amount, ownership percentage, or founding status.
|
Attributed | |
|
◆
GM-C069 — Nadsco’s white-facing stationery prominently displayed full names of officers, while three trustees were listed only by initials and surnames.
“Nadsco's white-facing stationery prominently displayed full names of officers, while three trustees were listed only by initials and surnames.”
|
This is a strong scholarly finding based directly on Morgan Papers. It supports analysis of differential corporate presentation but should not be expanded into claims that every named officer was merely a figurehead.
|
Attributed | |
|
◆
GM-C071 — The three trustees named on National Safety Device Company letterhead cannot presently be uniquely identified from the accessible record.
“The three trustees named on National Safety Device Company letterhead cannot presently be uniquely identified from the accessible record.”
|
Cook explicitly reports that only initials and surnames were printed for the three trustees and that this prevented unique matches. BEHI should preserve them as unidentified trustees until stronger records surface rather than guess.
|
Institute Analysis | |
|
◆
De-Curling Comb Patent Issued — U.S. Patent No. 2,762,382 (1956)
“Garrett A. Morgan, Sr. was granted U.S. Patent No. 2,762,382 for a de-curling comb on September 11, 1956, based on an application filed December 11, 1953.”
|
|
Verified |
Legacy
TAKEAWAY: Morgan’s legacy joins problem-solving, intellectual property, business ownership, and civic activity. Patent drawings and claims show what he actually designed.
LEGACY
Garrett A. Morgan’s legacy extends beyond the safety hood and traffic signal. His career shows how technical problem-solving could be combined with patents, business ownership, manufacturing, publishing, and civic activity.
His enduring importance lies in the documented pattern he repeated across decades: identify a problem, build a solution, protect the intellectual property, organize commercial activity, and create value around the result.
Three ways to study Morgan’s legacy
Technology that can be examined
Patent drawings and claims let readers study what he actually designed, rather than relying on an invention slogan.
Enterprise that needs its own evidence
Advertisements and customer reports connect invention to commercial activity. Accounts, contracts, and payrolls are needed to measure the results.
People and institutions in the record
Frank Morgan’s recognition and the estate’s succession records widen the story to shared work, family, property, and legal transfer.
BEHI analysis. Based on the patent records, contemporary reporting, municipal ordinance GM-S090, and probate file GM-S015. These are complementary ways to interpret the evidence, not a claim that every later technology or business descends directly from Morgan.
ENDURING LEGACY
Combined invention with company formation, manufacturing, sales, and intellectual-property strategy.
Developed patented breathing-device technology intended for hazardous smoke and fumes.
Patented an improved traffic signal incorporating an all-direction stop interval.
Operated in mechanical services, garments, personal care, safety equipment, media, and property.
Participated in Cleveland’s Black business, publishing, and civic infrastructure.
built independent enterprises rather than remaining only an employee or inventor-for-hire.
focused on practical technologies tied to real-world safety and transportation needs.
demonstrated a repeatable path from technical skill to patents, companies, customers, and capital.
His legacy is not simply what he invented—it is the economic structure he repeatedly built around invention.
CHANNELS OF LEGACY
Linked technical problem-solving to owned businesses, patents, and commercialization.
Worked on technologies connected to industrial safety and urban transportation.
Built businesses and assets within an economy shaped by racial barriers.
Participated in Black-owned publishing and civic institutions in Cleveland.
SHARED CREDIT AND LATER RECOGNITION
Frank Morgan receives explicit credit alongside Garrett in the 1929 compensation ordinance. This municipal record strengthens the account of shared rescue work without reducing the operation to a single hero or an unsupported rescue total. The ordinance’s wording identifies injuries sustained July 25, 1916; the broader disaster chronology is retained as the night of July 24–25.
The probate file supplies a further legacy: assets, legal transfers, beneficiaries and later administration can be studied as economic records. Those records complement the invention story while placing limits on unsupported claims about wealth.
SOURCES FOR THIS SECTION
| SOURCE ID | DOCUMENT / SOURCE | DATE | LOCATOR | USE |
|---|---|---|---|---|
| GM-S090 | Ordinance No. 86879-A — compensation for Garrett A. and Frank A. Morgan | 1929-09-23; printed 1929-10-02 | Garrett Morgan information.pdf, PDF p. 2; The City Record p. 17 / bound p. 1053 | Usable with Qualification |
| GM-S015 | Estate of Garrett A. Morgan Sr. — complete record set supplied for Case No. 646303 | 1963–1979 | 56-page court-supplied scan; pages 1–56 | Usable with Qualification |
| GM-S040 | Last Will and Testament of Garrett A. Morgan | 1955-06 | PDF pp. 8–9 | Usable |
| GM-S042 | Applications and Journal Entries — Transfer of Real Estate | 1964-08-04 | PDF pp. 25–31 | Usable |
Company Records
TAKEAWAY: Patents, advertisements, reports, and probate instruments support different findings. An advertisement or reported order does not establish fulfillment or payment.
COMPANY AND INSTITUTIONAL RECORDS
The evidence inventory contains patents, newspaper reports, probate instruments, catalog authorities and later interpretations. A citation entry is distinguished from an original scan held by BEHI.
Follow the business through its documents
Ownership & invention
The first 1914 breathing-device patent identifies National Safety Device Company in its assignment wording. A charter and stock register would answer separate questions about corporate formation and shareholders.
Products & customers
The 1919 Savannah Tribune advertisement identifies a product and retailer. The Yonkers report adds an order lead; fulfillment still requires invoices and payment records.
Property & succession
Case No. 646303 documents estate administration and asset transfers. Those personal estate records complement the company story but do not replace corporate ledgers or annual accounts.
Record guide: GM-S001–002, GM-S070, GM-S081 and GM-S015. Each document answers a particular question. The full record categories, source locators, and acquisition limits follow below.
THE DOCUMENTED BUSINESS AND INSTITUTIONAL RECORD
| RECORD CATEGORY | DATE | SOURCE / LOCATOR | WHAT IT ESTABLISHES AND ITS LIMITS |
|---|---|---|---|
| Intellectual property | 1914, 1923, 1956 | 1,090,936; 1,113,675; 1,475,024; 2,762,382 | Four issued U.S. patents; both 1914 patents name National Safety Device Company as assignee. Patents alone do not establish sales or licensing income. |
| Institutional customers | September 11–12, 1914 | Yonkers Statesman, September 12, p. 5 | Reports the demonstration on September 11 and a six-hood order on September 12. Delivery and payment remain unverified. |
| Garment and hair-care activity | April 21, 1916 | Kansas City Advocate, p. 1 | Contemporary account of business activity and his wife’s contribution. Promotional scale and ownership assertions require separate documentation. |
| Consumer products and retail | February 22, 1919 | Savannah Tribune, p. 6 | Advertisement markets Morgan’s Heavy Metal Hair Pressing Comb and related products and identifies a Savannah retailer. It does not identify a patent for that product. |
| Municipal compensation | September 23, 1929 | Ordinance No. 86879-A; The City Record, October 2, p. 17 / bound p. 1053; supplied packet p. 2 | Authorizes $2,000 each for Garrett and Frank Morgan for injuries sustained July 25, 1916. Payment vouchers remain to be acquired. |
| Estate and property | 1963–1979 | Cuyahoga County Probate Case No. 646303; 56-page court-supplied scan | Will, inventory, property transfers, tax return, fiduciary accounts and later proceedings document administered assets and succession. Probate appraisal is not lifetime wealth. |
| Business network | Published research and interview | Lisa Cook’s scholarship and 2018 interview | Identifies Alexander Dreyfus as treasurer with attribution to Cook. Original charter, letterhead, stock records and unique trustee identities remain research targets. |
| Publishing | Institutional title history | Cleveland Call and Call & Post | Institutional histories identify Morgan among a founding group. Original mastheads, corporate ownership and financing records remain to be reconciled. |
MUNICIPAL DOCUMENTS
| SOURCE | DOCUMENT | USE |
|---|---|---|
| GM-S090 | Ordinance No. 86879-A — compensation for Garrett A. and Frank A. Morgan | Authorizes $2,000 each from Water No. 101 fund for injuries sustained July 25, 1916. Authorization is not a payment voucher. Printed effective date November 3, 1929. |
| GM-S091 | Division of Water annual report for 1917 — West Side tunnel completion | Report states tunnel available June 2, 1917 and water turned into mains July 17, 1917. Context for completion, not a 1916 rescue roster. |
| GM-S092 | Division of Water annual report for 1918 — Crib No. 5 removal | Spring 1918 crib-removal context. Its no-accidents statement does not describe the 1916 tunnel disaster. |
SOURCES FOR THIS SECTION
| SOURCE ID | DOCUMENT / SOURCE | DATE | LOCATOR | USE |
|---|---|---|---|---|
| GM-S015 | Estate of Garrett A. Morgan Sr. — complete record set supplied for Case No. 646303 | 1963–1979 | 56-page court-supplied scan; pages 1–56 | Usable with Qualification |
| GM-S060 | “A Man of worth To the Race — G. A. Morgan” | 1916-04-21 | Page 1, far-left column; Institute file Kansas_City_Advocate_1916_04_21_1.pdf | Usable with Qualification |
| GM-S081 | “Test of Two Smoke Helmets” | 1914-09-12 | Page 5; article clipping supplied Aug. 10, 2026 | Usable with Qualification |
| GM-S090 | Ordinance No. 86879-A — compensation for Garrett A. and Frank A. Morgan | 1929-09-23; printed 1929-10-02 | Garrett Morgan information.pdf, PDF p. 2; The City Record p. 17 / bound p. 1053 | Usable with Qualification |
| GM-S086 | Lisa Cook interview: On invention gaps, hate-related violence, discrimination, and more | 2018-10-10 | Lines 59–89, Morgan consumer-discrimination discussion | Usable with Qualification |
Court links lead to the repository home; the case number and PDF page locators identify the supplied scan. They are not represented as public direct-document downloads. Source descriptions distinguish contemporary documents from later interpretation.
ARCHIVAL CERTIFICATION & PUBLIC RECORD INTEGRITY
All company records presented in this repository have been cataloged according to the BEHI Company Records Classification System. Documents marked as Primary Sources are drawn from certified state and county archives, corporate filings, and recognized institutional repositories. Where physical scans are currently in the acquisition pipeline, verified archival metadata, source citations, and holding locators are provided to facilitate scholarly research.
| Document & ID | Evidence Type | Date | Description & Location | Source Repository | Action |
|---|---|---|---|---|---|
|
U.S. Patent No. 1,090,936 — Breathing Device (1914)
BEHI-P002-GAM-REC001
Garrett A. Morgan / National Safety Device Company
|
Primary Archival
IP · Patents
|
March 24, 1914 |
Primary patent record documenting Morgan’s 1914 breathing-device patent and the intellectual-property relationship with National Safety D...
|
U.S. Patent No. 1,090,936
|
|
|
U.S. Patent No. 1,113,675 — Breathing Device (1914)
BEHI-P002-GAM-REC002
Garrett A. Morgan / National Safety Device Company
|
Primary Archival
IP · Patents
|
October 13, 1914 |
Primary patent record documenting a second breathing-device patent issued to Morgan in 1914.
|
U.S. Patent No. 1,113,675
|
|
|
Yonkers Statesman — Morgan Safety Hood Demonstration and Six-Unit Order (1914)
BEHI-P002-GAM-REC003
Yonkers Fire Department / National Safety Device Company
|
Primary Archival
Contracts & Transactions · Publications & Press Releases · Reports & Correspondence
|
September 12, 1914 |
Contemporary newspaper evidence associated with an early municipal demonstration and reported purchase of six Morgan Safety Hoods by the ...
|
Yonkers Statesman, September 12, 1914, p. 5; “Test of Two Smoke Helmets”
|
|
|
Kansas City Advocate — “A Man of Worth to the Race” (1916)
BEHI-P002-GAM-REC004
Garrett A. Morgan
|
Primary Archival
Publications & Press Releases · Reports & Correspondence
|
April 21, 1916 |
A contemporary profile describing Morgan’s business activity before the July 1916 Cleveland tunnel disaster.
|
Kansas City Advocate, April 21, 1916, p. 1
|
|
|
U.S. Patent No. 1,475,024 — Traffic Signal (1923)
BEHI-P002-GAM-REC005
Garrett A. Morgan
|
Primary Archival
IP · Patents
|
November 20, 1923 |
Primary patent record documenting Morgan’s traffic-control signal and its all-stop clearance function.
|
U.S. Patent No. 1,475,024
|
|
|
The Monitor — “Colored Hero at Cleveland Disaster” (1916)
BEHI-P002-GAM-REC006
Garrett A. Morgan / Cleveland waterworks tunnel disaster
|
Primary Archival
Publications & Press Releases · Reports & Correspondence
|
August 5, 1916 |
Contemporary newspaper source lead concerning Morgan’s role in the 1916 Cleveland waterworks tunnel disaster.
|
The Monitor, August 5, 1916, ed. 1; reported p. 1
|
|
|
GM-S015 — Estate of Garrett A. Morgan Sr. — Case No. 646303
BEHI-P002-GAM-SRC015
Garrett A. Morgan / Profile №2 evidence
|
Primary Archival
Estate & Testamentary · Ownership & Property
|
1963–1979 |
Complete court-supplied probate record set reviewed. Use with qualification because scan quality varies and probate assets do not equal l...
|
Case No. 646303; 56-page court-supplied scan; pages 1–56
|
|
|
GM-S070 — G. A. Morgan Hair Refining Company Advertisement — Heavy Metal Hair Pressing Comb
BEHI-P002-GAM-SRC070
Garrett A. Morgan / Profile №2 evidence
|
Primary Archival
Advertising · Operational
|
February 22, 1919 |
Primary contemporary advertisement verifying the marketed Heavy Metal Hair Pressing Comb and a named Savannah retailer. Patent status rem...
|
Page 6
|
|
|
GM-S072 — U.S. Patent No. 2,762,382 — De-curling comb — Garrett A. Morgan
BEHI-P002-GAM-SRC072
Garrett A. Morgan / Profile №2 evidence
|
Primary Archival
IP · Patents
|
September 11, 1956 |
Primary patent record for Morgan’s later de-curling comb. Separate from the 1919 Heavy Metal Hair Pressing Comb.
|
Full patent; filed December 11, 1953
|
|
|
GM-S073 — USPTO — Of courage and caution — Post-1916 Orders and Cancellations
BEHI-P002-GAM-SRC073
Garrett A. Morgan / Profile №2 evidence
|
Secondary Scholarship
Contracts & Transactions · Publications & Press Releases · Reports & Correspondence
|
2023 |
Institutional source reporting new fire-department orders and cancellations by some Southern cities after Morgan’s race became known. Tra...
|
Post-tunnel-disaster demand/cancellation passage
|
|
|
GM-S085 — Cook — Overcoming Discrimination by Consumers during the Age of Segregation
BEHI-P002-GAM-SRC085
Garrett A. Morgan / Profile №2 evidence
|
Secondary Scholarship
Publications & Press Releases · Reports & Correspondence
|
2012 |
Peer-reviewed archival analysis of Nadsco’s white-facing business network and stationery. Original letterhead remains the highest-priorit...
|
Footnotes 47–49 and Nadsco archival discussion
|
|
|
GM-S023 — U.S. Patent No. 976,939 — Street-Traffic System
BEHI-P002-GAM-SRC023
Garrett A. Morgan / Profile №2 evidence
|
Primary Archival | November 29, 1910 |
Primary prior-art patent documenting a street-traffic system before Morgan’s 1922 filing.
|
Full patent
|
|
|
GM-S025 — U.S. Patent No. 764,709 — Respiratory Apparatus for Firemen or Others
BEHI-P002-GAM-SRC025
Garrett A. Morgan / Profile №2 evidence
|
Primary Archival | July 12, 1904 |
Primary prior-art patent documenting respiratory apparatus for smoke, foul air, or noxious gases before Morgan’s patents.
|
Full patent
|
|
|
GM-S039 — Application for Probate of Will; Application for Letters Testamentary
BEHI-P002-GAM-SRC039
Garrett A. Morgan / Profile №2 evidence
|
Primary Archival
Court Filings · Legal & Regulatory
|
August 1963 |
Primary court records stating Morgan died July 27, 1963 at the Cleveland Clinic and identifying spouse and sons.
|
Case No. 646303; PDF pp. 3–4 and 10–11
|
|
|
GM-S040 — Last Will and Testament of Garrett A. Morgan
BEHI-P002-GAM-SRC040
Garrett A. Morgan / Profile №2 evidence
|
Primary Archival
Estate & Testamentary · Ownership & Property
|
June 1955 |
Primary will establishing beneficiaries, executor, and testamentary shares.
|
Case No. 646303; PDF pp. 8–9
|
|
|
GM-S041 — Inventory and Appraisement — Schedules A–G
BEHI-P002-GAM-SRC041
Garrett A. Morgan / Profile №2 evidence
|
Primary Archival
Financial
|
January 1964 |
Primary probate inventory reporting $12,033.04 gross appraised assets. Probate appraisal is not lifetime wealth or present-day market value.
|
Case No. 646303; PDF pp. 15–23
|
|
|
GM-S042 — Applications and Journal Entries — Transfer of Real Estate
BEHI-P002-GAM-SRC042
Garrett A. Morgan / Profile №2 evidence
|
Primary Archival
Ownership & Property · Property Records
|
August 4, 1964 |
Primary court record of legal descriptions and testamentary real-estate transfers.
|
Case No. 646303; PDF pp. 25–31
|
|
|
GM-S044 — Final Fiduciary Account and Distribution Record
BEHI-P002-GAM-SRC044
Garrett A. Morgan / Profile №2 evidence
|
Primary Archival
Ledgers & Accounts
|
July–August 1964 |
Primary fiduciary account documenting distribution of vehicle, personal effects, deposits, and real estate.
|
Case No. 646303; PDF pp. 55–56
|
|
|
GM-S045 — Successor Executor Proceedings and Zero-Activity Fiduciary Account
BEHI-P002-GAM-SRC045
Garrett A. Morgan / Profile №2 evidence
|
Primary Archival
Ledgers & Accounts
|
1977 |
Primary court record showing earlier administration was complete and no new receipts or disbursements came into the successor executor’s ...
|
Case No. 646303; PDF pp. 37–46
|
|
|
GM-S046 — After-Discovered Cleveland Trust Checking Account Proceeding
BEHI-P002-GAM-SRC046
Garrett A. Morgan / Profile №2 evidence
|
Primary Archival
Banking Records · Financial
|
December 1978–January 1979 |
Primary court record releasing an after-discovered checking account to Cosmo H. Morgan. Exact cents remain qualified because of scan legi...
|
Case No. 646303; PDF pp. 47–54
|
No verified records are currently published in this category.
Receipts
TAKEAWAY: Morgan’s evidence includes both inspected records and unresolved acquisition leads. Limited archival searches do not prove that equipment was never evaluated or used.
RECEIPTS & EVIDENCE
HOW TO READ THE EVIDENCE
Follow the claim to its source, then read the evidence status and limits. A source may support one narrow fact while leaving a larger conclusion unresolved.
Content condition describes whether the question can currently be answered. Evidence classification describes the support for a documented finding.
- Documented: A finding is presented with its source, evidence classification and limits. Documented does not automatically mean Verified.
- Not yet established: The answer remains unresolved. The entry identifies missing evidence and connects to Research Gaps.
- Not applicable: The measure does not fit the person or enterprise being examined; an explanation must state why. Missing evidence alone never makes a question not applicable.
Shared section headings remain visible. Relevance that is uncertain is treated as Not yet established until resolved.
Evidence labels and source access
- Verified
- The specific fact or record described has been checked against the cited material. Read the limit: an inspected reproduction, index or catalog entry does not mean every underlying document or broader claim has been verified.
- Attributed
- The statement is credited to the named source. Independent confirmation or the underlying original may still be outstanding.
- Disputed
- Sources or interpretations conflict. Read the competing evidence and the unresolved question.
- Estimated
- The figure is an approximation or qualified valuation, not an exact measured total. Read its basis, date and uncertainty.
- Institute Analysis
- BEHI’s interpretation or calculation from identified evidence. It is separate from what the historical source directly states.
Source access: A link may lead to an original scan, a published transcription, a finding aid, or a repository page. Use the source ID, collection, box, folder and page locator where supplied. A catalog listing or repository confirmation is not inspection of the item itself.
Images and permissions: Historical support and reproduction permission are separate questions. Read each image credit and rights note; a source link does not itself grant permission to republish.
Open questions: See Research Gaps & Open Questions below for missing records and unresolved claims.
Each Receipt links a specific assertion to its evidence and limitations. This Profile preserves verified patent and court facts while keeping attributed reporting, disputed claims and BEHI analysis distinct.
DOCUMENTS
Morgan probate — 56-page packet, Case No. 646303
Publication hold — reviewed October 28, 2026. Court delivery and completeness correspondence establish provenance. On August 6, 2026, the court confirmed that the supplied packet contains everything on the case microfilm. That confirmation does not state republication terms for the entire mixed-document packet.
Release condition: Document the applicable reproduction basis for the complete packet, confirm any required treatment of individual filings, and finish page-level publication review.
Evidence limit: Complete on the supplied microfilm does not mean every original record survives. Probate appraisal and taxable-estate figures are not lifetime net worth. This publication hold does not change the claim-specific evidence classifications.
Preview: Withheld while the publication hold is unresolved; the description above identifies the supplied material.
Full file: Not publicly released. No download is offered while this hold remains.
Citation: Cuyahoga County Probate Court, Garrett A. Morgan estate, Case No. 646303, 56-page microfilm reproduction; completeness correspondence, August 6, 2026.
Evidence classification: Primary probate case reproduction; estate measures are distinct from lifetime net worth.
Rights note: Unresolved reproduction terms; release conditions above remain in force.
Original Patent Drawings — Garrett A. Morgan
Primary-source patent drawings, reproduced for visual inspection. Select a drawing to open the full-size image.
Traffic signal patent, 1923
Readable text — Visual description
The displayed drawing is sheet 1 of 2 of patent 1,475,024, dated November 20, 1923; the application date is February 27, 1922. Figures 1–4 show a vertical traffic-signal pole, movable arms bearing STOP and GO lettering, and operating parts with reference numbers.
Description of the displayed drawing only. The remaining drawing sheet and written patent specification are not transcribed here; use the full-file link below. Checked against the source images by BEHI, October 28, 2026.
Preview: Supplied document image; see citation for coverage.
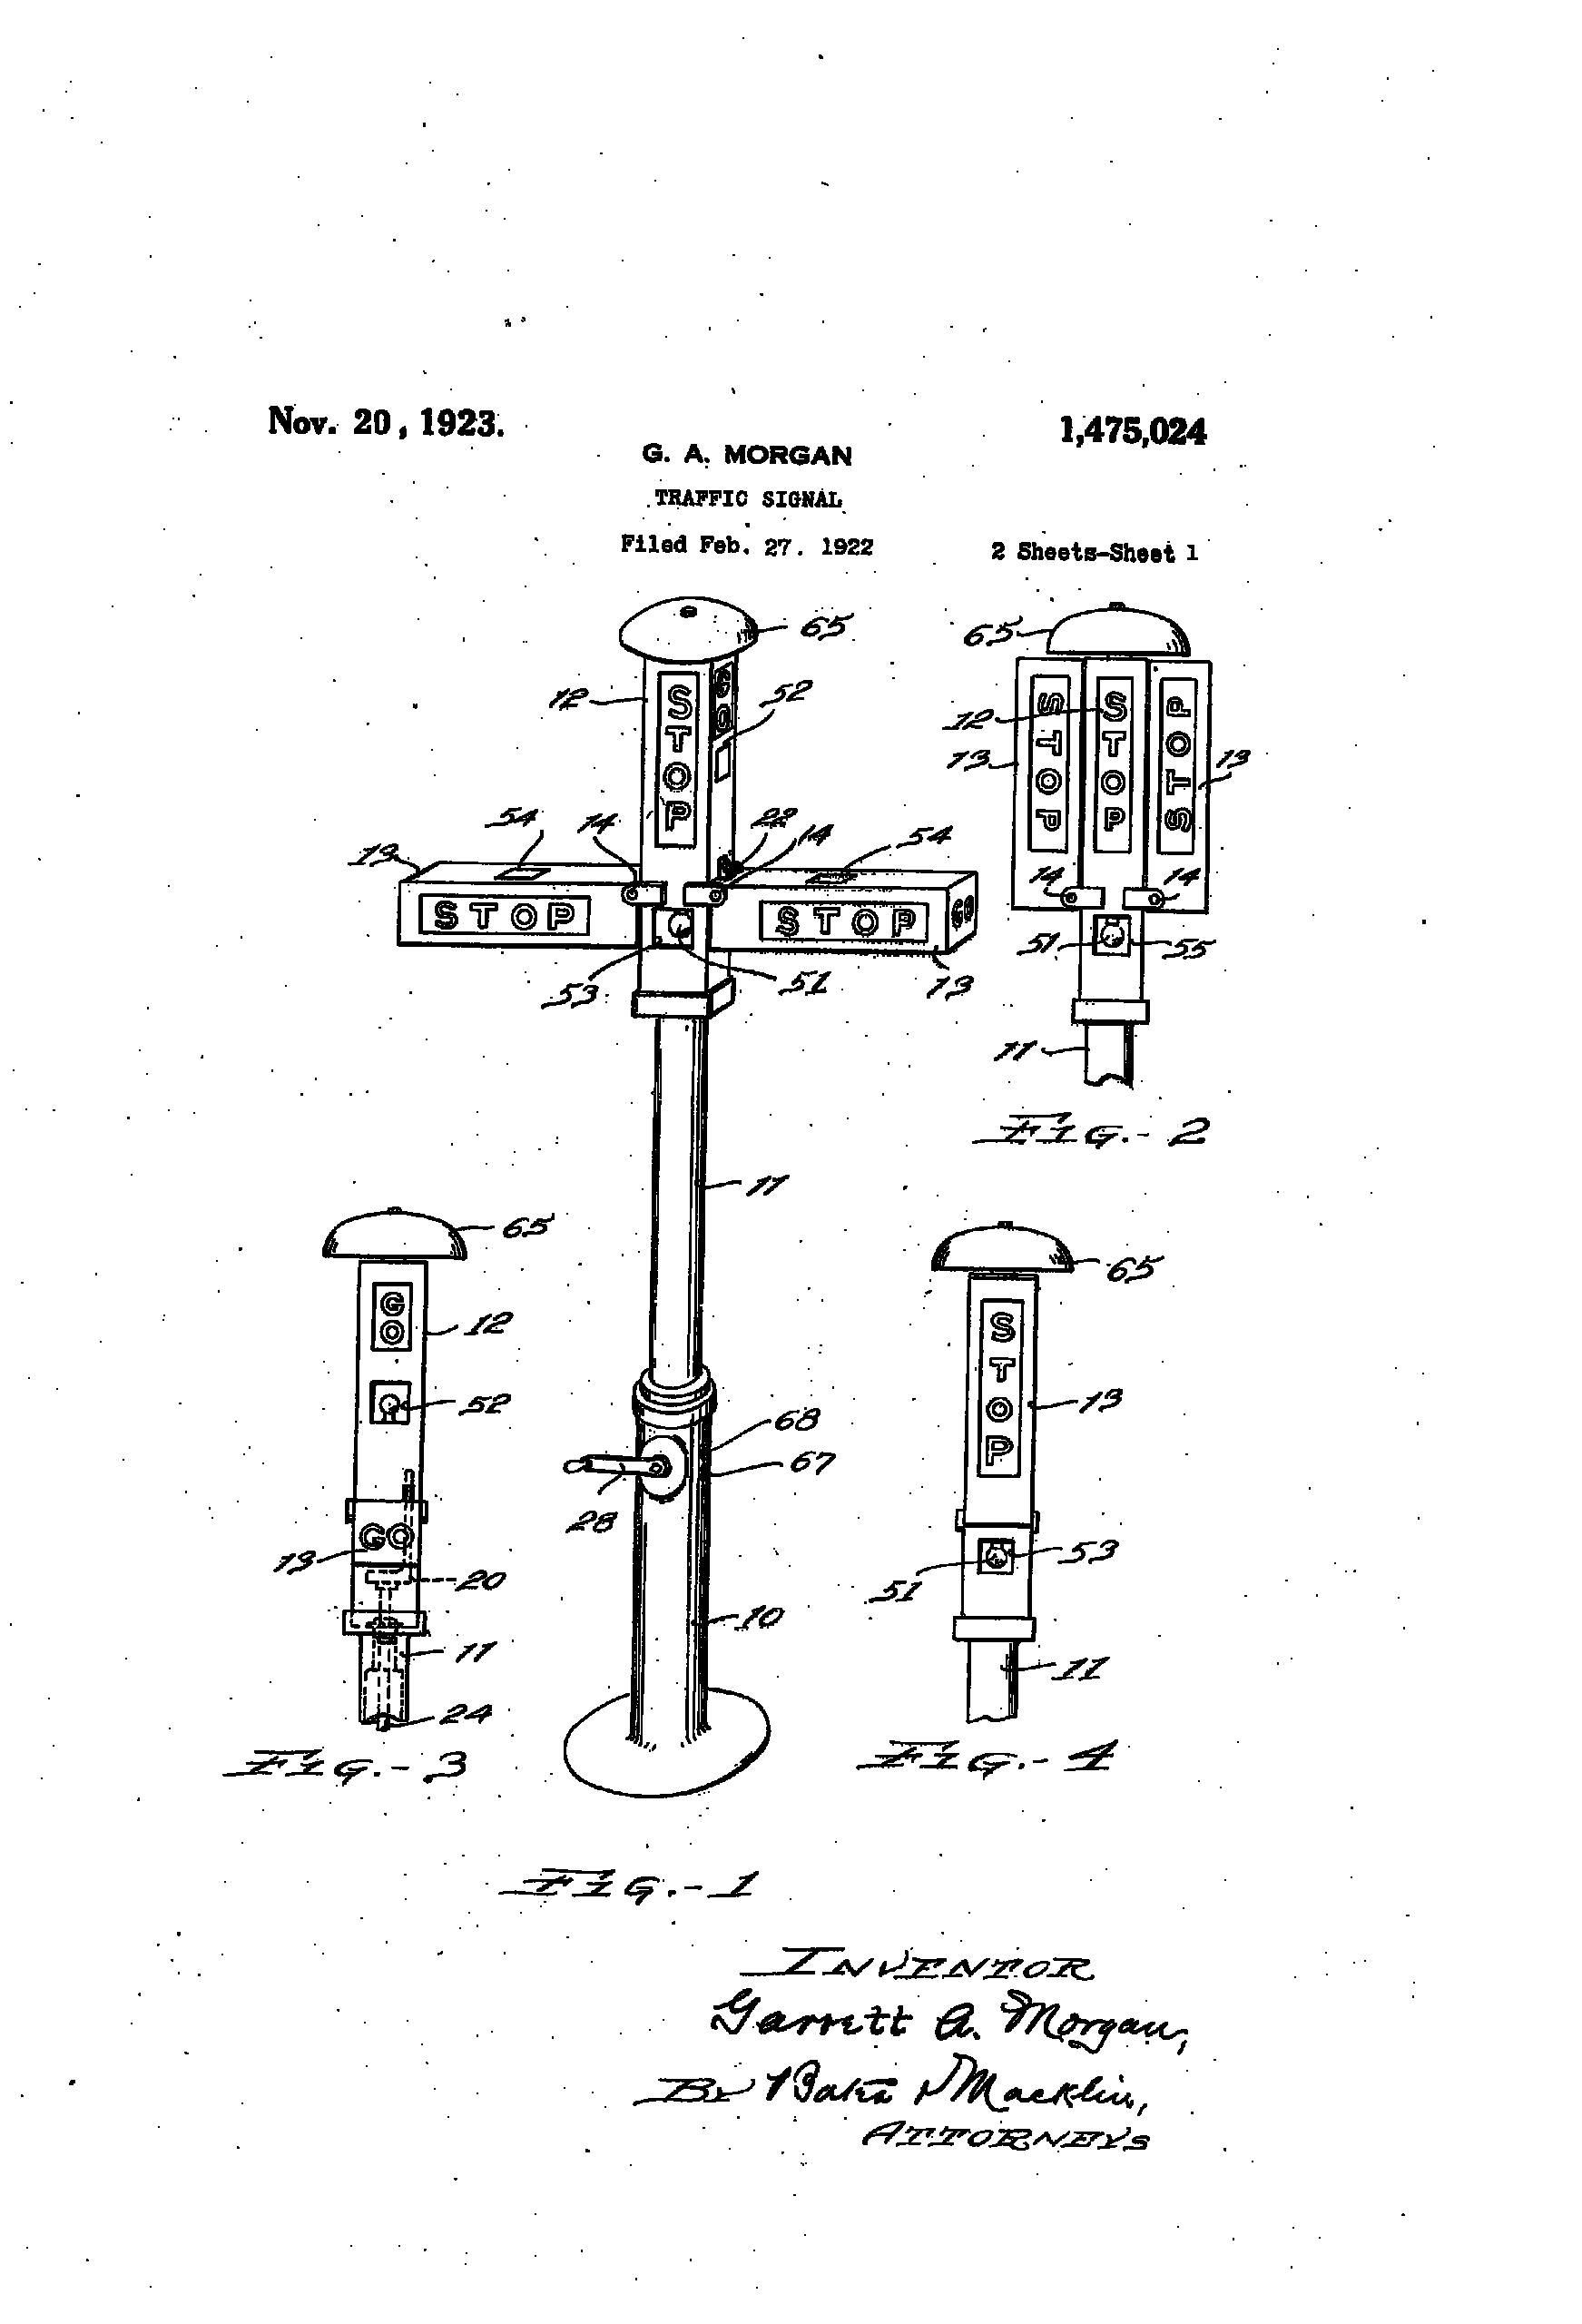
Full file: Open full-size file
Evidence classification: Primary patent record; disclosed invention, not sales or earnings.
Rights note: Historical U.S. patent; existing public-domain/CC0 reproduction.
Breathing-device patent, 1914
Readable text — Visual description
The displayed drawing is sheet 1 of 2 of patent 1,113,675, dated October 13, 1914; the application date is August 19, 1912. It shows a person wearing a hood, with long tubes extending toward the feet, alongside separate views of the hood and tubing.
Description of the displayed drawing only, not a statement of tested performance. The remaining sheet and written specification are not transcribed here. Checked against the source images by BEHI, October 28, 2026.
Preview: Supplied document image; see citation for coverage.
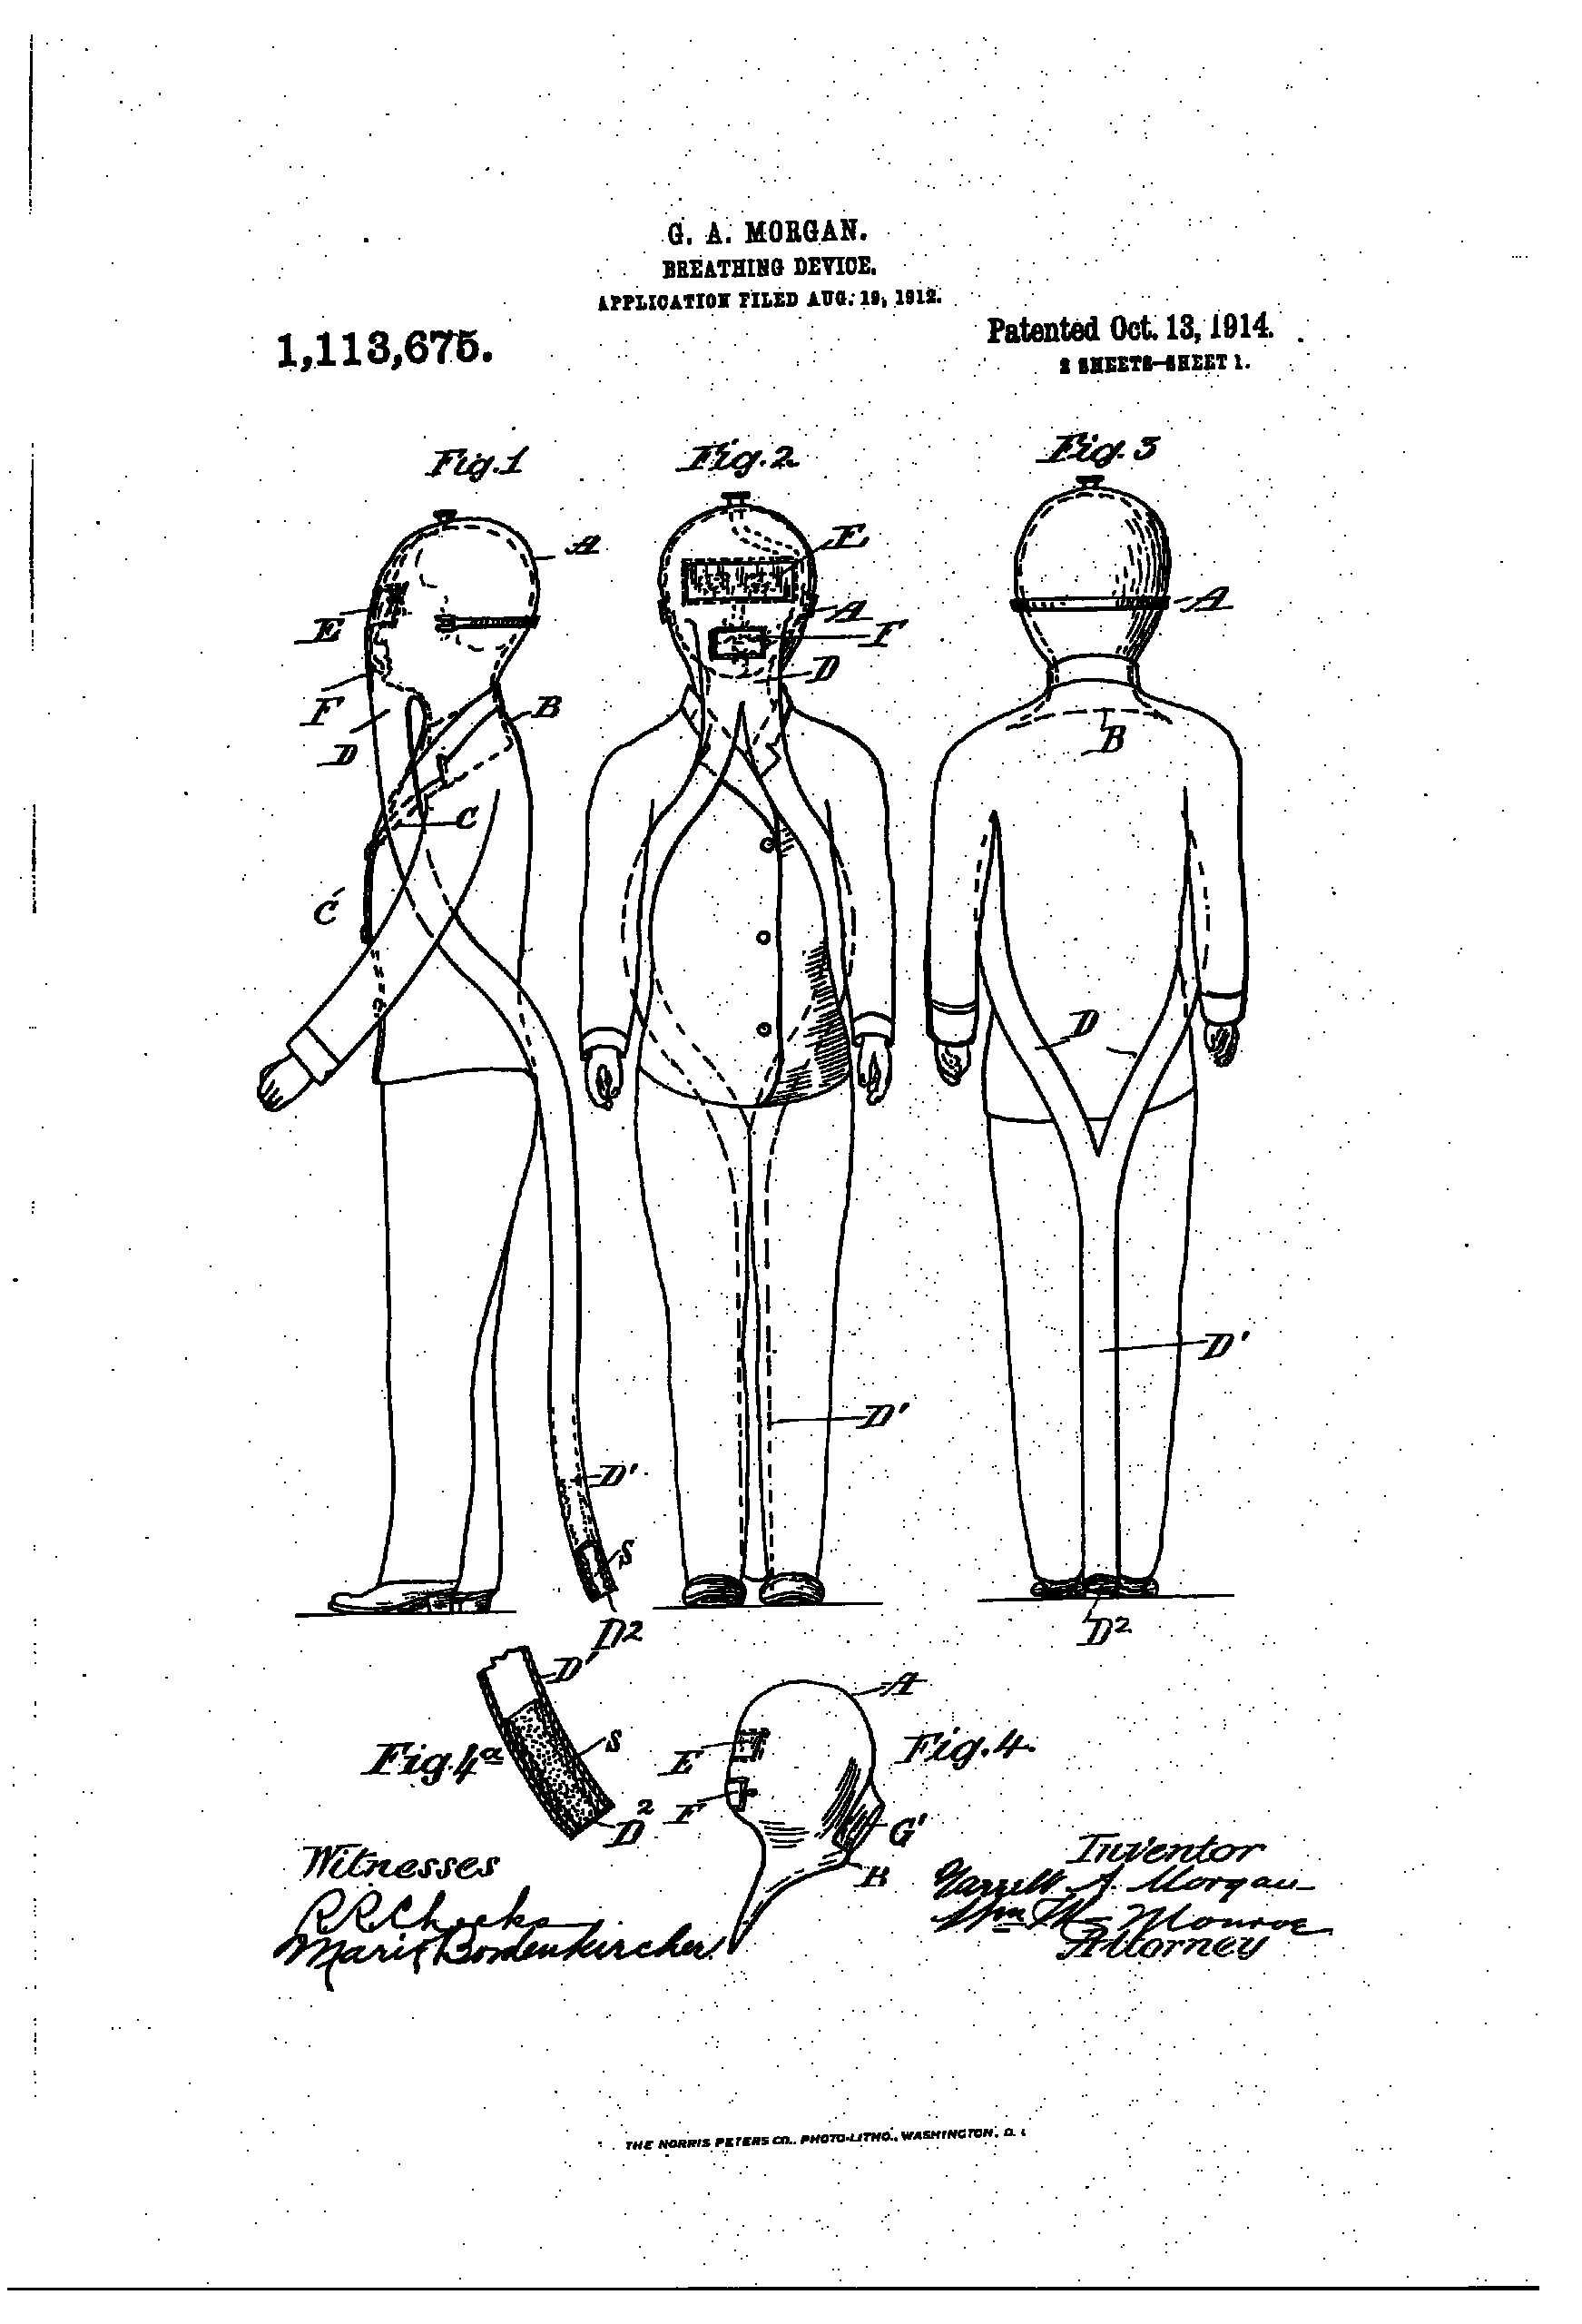
Full file: Open full-size file
Evidence classification: Primary patent record; disclosed invention, not sales or earnings.
Rights note: Historical U.S. patent; existing public-domain/CC0 reproduction.
Source: historical U.S. patent drawings, public-domain/CC0 reproductions via Wikimedia Commons. Patents establish disclosed inventions, not sales or earnings.
Read a Receipt: claim, document, boundary
Patent → design
GM-S003 identifies the inventor, issue date, and traffic-signal mechanism. It supports the patented improvement; a rights-sale payment needs a different receipt.
Ordinance → authorization
GM-S090 names Garrett and Frank and authorizes $2,000 each. A voucher or check is needed to establish that either amount was actually paid.
Inventory → appraised assets
GM-S041 records gross estate assets of $12,033.04. The inventory, statutory set-aside, and taxable estate are different measures, not interchangeable wealth totals.
Evidence-reading guide. Source identifiers connect these examples to the detailed tables below. A verified document can support a narrow fact while leaving a broader claim unresolved.
SOURCE REGISTER & EVIDENCE LIMITS
WHAT THE RECEIPTS ESTABLISH
| EVIDENCE | SOURCE IDS | CLASSIFICATION | READING LIMIT |
|---|---|---|---|
| Breathing-device patents | GM-S001; GM-S002 | Verified patent records | The two 1914 patents document specific improvements and the company assignment; avoid a universal gas-mask invention claim. |
| Yonkers order | GM-S081 | Attributed contemporary reporting | September 11 demonstration; six-hood order reported September 12. Delivery and payment remain unverified. |
| Tunnel rescue and compensation | GM-S090 | Verified ordinance content | The city explicitly names Garrett and Frank and authorizes $2,000 each. This establishes authorization, not disbursement or a fixed rescue count. |
| Traffic-signal patent | GM-S003 | Verified patent record | The 1923 patent documents a manually operated signal with an all-stop clearance interval, distinct from inventing the modern three-color light. |
| Reported GE rights transaction | GM-S019; GM-S021 | Attributed claim | The reported $40,000 terms require an executed agreement, assignment or licensing instrument and payment evidence. |
| Business activity and Mary Morgan’s contribution | GM-S060 | Attributed contemporary account | The April 1916 article supports a documented account of business activity; it does not establish every promotional figure or Mary’s exact legal role. |
| Hair pressing comb | GM-S070 | Verified advertisement content | The 1919 advertisement markets a comb; it does not identify a patent for the product. |
| De-curling comb patent | GM-S072 | Verified patent record | The September 11, 1956 patent is a separate invention, distinct from the 1919 advertised product and Laing’s 1914 patent. |
| Estate assets and succession | GM-S039–GM-S046 | Court records, with qualifications | Case No. 646303 documents administered property, beneficiaries and appraisal. Gross assets, net estate and taxable property are separate measures. |
| Orders, cancellations and business network | GM-S073; GM-S085; GM-S086 | Attributed secondary interpretation | Published histories and scholarship supply leads; original transaction records, letterhead and a quantified revenue effect remain outstanding. |
| Trustee identities | GM-S085 | Present research limit | Published scholarship does not uniquely identify the three trustees. BEHI does not assign identities from initials alone. |
SOURCES FOR THIS SECTION
| SOURCE ID | DOCUMENT / SOURCE | DATE | LOCATOR | USE |
|---|---|---|---|---|
| GM-S001 | U.S. Patent No. 1,090,936 — Breathing Device | 1914-03-24 | Full patent; specification, drawings, and claims | Usable |
| GM-S002 | U.S. Patent No. 1,113,675 — Breathing Device | 1914-10-13 | Full patent; specification, drawings, and claims | Usable |
| GM-S003 | U.S. Patent No. 1,475,024 — Traffic Signal | 1923-11-20 | Full patent; specification, drawings, and claims | Usable |
| GM-S072 | U.S. Patent No. 2,762,382 — De-curling comb | 1956-09-11 | Filed 1953-12-11; full specification, claims, and cited prior art | Usable |
| GM-S060 | “A Man of worth To the Race — G. A. Morgan” | 1916-04-21 | Page 1, far-left column; Institute file Kansas_City_Advocate_1916_04_21_1.pdf | Usable with Qualification |
| GM-S081 | “Test of Two Smoke Helmets” | 1914-09-12 | Page 5; article clipping supplied Aug. 10, 2026 | Usable with Qualification |
| GM-S041 | Inventory and Appraisement — Schedules A–G | 1964-01 | PDF pp. 15–23 | Usable with Qualification |
| GM-S090 | Ordinance No. 86879-A — compensation for Garrett A. and Frank A. Morgan | 1929-09-23; printed 1929-10-02 | Garrett Morgan information.pdf, PDF p. 2; The City Record p. 17 / bound p. 1053 | Usable with Qualification |
RESEARCH GAPS & OPEN QUESTIONS
ECONOMIC INDICATORS — MISSING EVIDENCE
Annual revenue and profit
Content condition: Not yet established. Morgan businesses
Reporting period not established
Evidence needed / present limit: Requires entity-specific accounts and expense records.
The record remains open. This Profile presents the evidence currently assembled; further documents may expand, clarify, or correct it.
These questions distinguish evidence still to be located from evidence that needs further review. An open question does not establish or disprove a claim.
Yonkers safety-hood procurement
What do the original municipal records establish about the reported 1914 order for six Morgan safety hoods and its fulfillment?
Evidence needed: The municipal authorization or order, invoices, payment records, and fire-department minutes linked to the transaction.
Status: Original procurement documentation remains a research target; a reported order is not proof of delivery or payment.
Navy orders and commercial follow-through
What original records establish the reported 1918 Navy order, including the device, quantity, supplier, delivery, and payment?
Evidence needed: Navy purchasing files, contracts, correspondence, shipping records, and payment vouchers.
Status: Original procurement records remain to be located and reviewed.
Traffic-signal rights and payment
What do original transaction records establish about the often-repeated sale or licensing of Morgan’s traffic-signal rights?
Evidence needed: The executed agreement, assignment or licensing documents, related correspondence, and payment evidence.
Status: Further primary-document verification is needed for the transaction terms and reported payment.
Business scale and employment
What dated records support specific employee counts, manufacturing output, sales, and the effect of reported order cancellations?
Evidence needed: Payrolls, company accounts, order books, cancellation correspondence, and dated manufacturing records.
Status: Precise figures and commercial effects need further reconciliation with contemporary business records.
HELP EXPAND THE RECORD
Have a document or source that could expand or clarify this Profile? Share the source, its provenance, and your explanation with BEHI for review. Contributions undergo BEHI’s verification process before any decision to include them.
Contact BEHI about a source. Include the Profile name, where the document came from, and any known ownership or reproduction restrictions.
FURTHER RESEARCH QUESTIONS
| QUESTION | EVIDENCE NEEDED | PRESENT LIMIT |
|---|---|---|
| What is the primary birth-year chronology? | Vital record, census and family-record hierarchy | 1877 commonly reported; 1879 also appears |
| Were the 1929 compensation amounts disbursed? | City vouchers, checks, ledger and appropriation records | Ordinance authorizes $2,000 each; payment unverified |
| Who held Nadsco ownership and legal offices? | Original charter, letterhead, stock register and corporate minutes | Dreyfus identified with attribution to Cook; trustee identities not guessed |
| What did Mary Morgan contribute to the businesses? | Accounts, correspondence, title and employment records | 1916 newspaper credits her contribution without fixing a legal role |
| What is the underlying 32-worker record? | Dated payroll, employee register or contemporaneous business return | Retrospective repetition now traced at least to 1976 |
| What proves the specific military contracts? | Original 1915 / 1918 newspaper pages plus Navy / Army contracts, delivery and payment files | Institutional and contemporary-report leads do not establish procurement fulfillment |
| What does the estate omit or later add? | Complete case index, deeds, bank statements and clearer after-discovered-account scan | Administrative appraisal is not lifetime wealth |
| Can the portrait’s provenance be improved? | Original NHTSA / archive identifier, creator, date and rights documentation | Commons upload date is not the photograph date |
RESEARCH UPDATES & RECONCILIATION
Evidence status: Archival leads only: Navy adoption or use remains unverified.
Read full note: U.S. Navy archival leads — October 2026
Research gap — U.S. Navy subject files (October 2026): In correspondence with BEHI, National Archives Textual Reference staff clarified that NAID 594070 combines RG 45 Navy Subject Files, 1775–1910 (Entry 502), and Navy Subject Files, 1911–1927 (Entry 520), even though the catalog's 1924–1946 dates describe later compilation or maintenance. Staff identified Entry 520, Box 994 (Bureau of Steam Engineering / Bureau of Engineering), and Box 995 (Bureau of Supplies and Accounts / Bureau of Engineering), as potentially relevant archival locations. These files are not digitized. BEHI has requested folder-level descriptions to narrow its inquiry into potential Navy consideration, evaluation, procurement or use of Morgan's safety hood or related breathing apparatus. Status: archival leads only; no Morgan-related Navy record has been inspected or identified in these boxes, and Navy adoption or use remains unverified. NARA advises in-person research or fee-based reproduction, generally $0.80 per page with a $20 mail-order minimum.
Research Gap — Yonkers Fire Department FOIL #24090
Evidence status: No responsive records were located in the stated search; this does not prove that Yonkers never used Morgan equipment. The appeal remains pending.
Read full note: Yonkers FOIL search and appeal
September 22, 2026: the Yonkers Fire Department certified that, after a diligent search, no records responsive to BEHI’s request concerning the demonstration, evaluation, acquisition, purchase, possession, or use of Morgan-associated smoke helmets or related respiratory protective equipment were located in the Fire Department’s possession.
Evidence boundary: this is a negative-search result, not proof that Yonkers never evaluated or used Morgan equipment. BEHI filed an administrative appeal asking whether historical, transferred, archived, or other municipal record series were included in the search. Appeal status: pending.
Safety Hood Patent Issued — U.S. Patent No. 1,090,936 (1914)
Audited Historical Assertion
Garrett A. Morgan was granted U.S. Patent No. 1,090,936 for a breathing device on March 24, 1914.
Supporting Archival Receipts & Primary Sources
HOW TO READ THE RECEIPTS & ARCHIVAL CITATIONS
Evidence linked on this page may include primary archival records, contemporary sources, repository citations, authoritative secondary scholarship, and Institute analysis. Where a physical archival holding has been identified, BEHI provides repository and locator information when available.
Cite This Profile
The Black Economic History Institute (BEHI) Digital Archive