Profile №15 BEHI-P015-AGG
A. G. Gaston
1892–1996
Insurance Founder · Funeral Services · Banking · Education · Hospitality
Overview
TAKEAWAY: Gaston developed a network of service and financial enterprises with collaborators, including Minnie L. Gaston. Business operations and company resources are distinct from personal net worth.
BEHI PROFILE — RESEARCH IN PROGRESS — UPDATED NOVEMBER 4, 2026. CLAIMS ARE CLASSIFIED INDIVIDUALLY; ORIGINAL CORPORATE AND FINANCIAL RECORDS REMAIN UNDER INVESTIGATION.
OVERVIEW
Arthur George “A. G.” Gaston (1892–1996) was a Birmingham entrepreneur who developed an interlocking group of service and financial enterprises: burial insurance, funeral services, banking, vocational education, lodging, real estate, and broadcasting. The record reflects both his initiative and the work of collaborators, including Minnie L. Gaston. This profile distinguishes business operations from Gaston’s personal net worth and measures claims at the level each source supports.
One founder, multiple institutions
Recurring premium payments and burial protection
Service delivery, property, and facilities
Savings and lending infrastructure
Office training and employment pathways
Travel accommodation and broadcasting
THE ECONOMIC SYSTEM BEHIND THE GASTON ENTERPRISES
The 1926 Alabama insurance report documents a working burial society. A 1932 funeral invoice and a 1933 payment certificate document individual transactions.
Citizens Federal's 1956 charter and later corporate transformations are described in SEC-filed company records; lending outcomes remain a separate question.
Minnie L. Gaston's correspondence records the business college's workforce ambitions and employer demand, not a verified placement rate.
THREE DOCUMENTARY TRAILS
| Business activity | Documentary anchor | Evidence boundary |
|---|---|---|
| Burial and funeral services | 1926 insurer report; 1932 invoice; 1933 dues certificate | Selected records, not total corporate earnings |
| Banking and savings | 2002 company statement filed with SEC | Company milestones, not Gaston's personal shareholding |
| Professional training | 1966 congressional correspondence from Minnie L. Gaston | Employer inquiries are not completed hires |
This overview maps distinct economic institutions and their sources. It does not assert a consolidated corporate group, a unified balance sheet or a verified personal net worth.
EXACT ACCOMPLISHMENTS
The 1926 Alabama report, 1932 funeral invoice and 1933 payment certificate document operating activity and individual transactions, not total earnings.
SEC-filed company history describes Citizens Federal’s 1956 charter and subsequent corporate changes. This is a company account, not an independently inspected original charter.
Minnie L. Gaston’s 1966 correspondence documents the business college’s workforce ambitions and employer inquiries. Inquiries do not establish completed hires or a placement rate.
What Would Move This Profile Forward?
These are the next evidence priorities for strengthening this Profile. Each identifies a concrete research step and what it could help establish.
- Complete the ESOP transaction record
Obtain the original 1987 transfer instruments, the missing 1992 audit, notes and investment detail, and the missing 2009 Schedules H and R. The received Form 5500 packages provide a starting point; these additions would clarify ownership transfer, valuation and plan finances.
- Recover motel conveyance and financing records
Obtain the signed March 29, 1954 deed, related mortgages, corporate authorizations and construction payment records. These would extend the recovered property-transaction entry into evidence of title, financing and actual expenditure.
- Establish original corporate and banking ownership
Acquire formation documents, stock registers and Citizens Federal charter and conversion records. These would distinguish Gaston’s individual interests from the assets of separate institutions.
- Document graduate employment outcomes
Recover the 1965 House hearing on H.R. 6468, pages 104–107, and supporting placement records. These would help distinguish employer inquiries and reported placements from documented hires.
Read the Research Gaps & Open Questions for the unresolved issues and evidence limits. New material is reviewed before claims or classifications change.
THE RECEIPTS OR EVIDENCE SUPPORTING THIS PROFILE
Evidence labels apply to individual claims. Read the evidence guide and content-condition definitions.
| SOURCE / LOCATOR | RECORD / CONTEXT | DATE / PERIOD | EVIDENCE STATUS | SUPPORT / LIMITS |
|---|---|---|---|---|
| Alabama insurance report Printed p. 414; supplied PDF p. 415 | Inspected regulator report; Booker T. Washington Burial Society | 1926 | VERIFIED | Documents the Society’s reported activity and finances. Company amounts are not Gaston’s personal wealth; legal continuity with later entities requires separate evidence. |
| Alabama insurance report Printed pp. 146, 176; PDF pp. 151, 181 | Inspected regulator report; Booker T. Washington Burial Insurance Company | 1936 | VERIFIED | Supports company financial and insurance figures and the corrected 1935 coverage comparison. Distinct company rows and reporting years must remain separate. |
| Citizens Federal / CFS company statement BEHI-P015-S11; Exhibit 99.2 | SEC-filed corporate account of banking history | May 30, 2002 | ATTRIBUTED | Company account describes the 1956 charter and later changes. Underlying original charters are not yet inspected; corporate assets do not establish Gaston’s personal ownership or wealth. |
| Senate manpower hearing BEHI-P015-S05; printed pp. 40–41 | Published Minnie L. Gaston correspondence | 1966 | VERIFIED | Documents correspondence and reported employer demand. Requests are not confirmed hires or a verified placement rate; underlying 1965 placement pages remain an acquisition target. |
DOCUMENTED MOTEL PROPERTY TRANSACTION
A Jefferson County Board of Equalization entry records a March 29, 1954 transfer from Booker T. Washington Insurance Co. to A. G. Gaston Motels, Inc., listing $64,637.72. This is a corporate transaction amount; payment, construction financing and personal wealth require separate evidence. Read the transaction entry, archival citation and limits.
THE RECORD & ITS LIMITS
Different enterprises were distinct legal entities. Corporate assets, reported sale values, enrollment figures and enterprise revenues are not interchangeable with personal income or wealth.
HISTORY WITH RECEIPTS™
Claims remain subject to individual source review. Additional archival material will be added as evidence is recovered.
Background
TAKEAWAY: Gaston’s Birmingham career developed under segregation through family, managerial, investor, and employee relationships. Each enterprise’s participants require specific attribution.
BACKGROUND
Gaston was born in Demopolis, Alabama, in 1892 and developed his career in Birmingham in the context of segregation and restricted access to capital, insurance, lodging and professional employment. His business expansion involved family collaborators, managers, investors and employees; the relevant organizational relationships must be documented enterprise by enterprise.
Background: the records we can follow
- Burial and funeral enterprises provided early, recurring customer relationships.
- Insurance and lending businesses created distinct pools of financial resources and regulatory obligations.
- Minnie L. Gaston played a documented leadership role in the business college, including communications with federal and state officials.
- Property records and financial ledgers are needed to reconstruct how specific acquisitions were financed.
HISTORICAL & ECONOMIC CONTEXT
State filings name Creola A. Gaston, Bessie Smith, Ella Fulton and others in distinct formations; Minnie L. Gaston's educational leadership is documented separately.
A 1926 Alabama report identifies A. G. Gaston as president of the Booker T. Washington Burial Society and records its early activity.
Alabama Penny Savings Bank, founded in 1890, preceded Citizens Federal; the earlier institutions were not necessarily Gaston's legal predecessors.
EVIDENCE & CONTEXT
| Date | Documentary anchor | Important qualification |
|---|---|---|
| 1925–1926 | State incorporation listing and insurer report | Officers and incorporators are different roles |
| 1928 and 1931 | Separate Alabama corporate identifiers | Continuity of assets and policies requires original instruments |
| 1956 | Citizens Federal charter reported in SEC-filing | Financial-institution record is distinct from the burial enterprise |
Biography and institutional history should distinguish later accounts from original company records. Family collaboration does not, by itself, prove shared ownership.
THE RECORD & ITS LIMITS
Exact early investment amounts and ownership percentages have not been reconstructed from original deeds, subscriber records and stock ledgers.
HISTORY WITH RECEIPTS™
Claims remain subject to individual source review. Additional archival material will be added as evidence is recovered.
The Problem
TAKEAWAY: Gaston’s businesses addressed barriers in insurance, credit, funerals, training, and lodging. Their existence alone does not measure household reach or outcomes.
THE PROBLEM
Segregated Birmingham presented barriers to adequate insurance, credit, dignified funeral services, skilled office training, and lodging for Black travelers. Gaston’s enterprises addressed several of these needs with privately operated services, but the existence of a business is not by itself proof that it met every community need or reached every household.
Economic needs and enterprise responses
| Barrier | Associated initiative | What remains to measure |
|---|---|---|
| Limited burial protection | Burial-insurance services | Premiums, claims and policyholder counts |
| Restricted access to banking | Citizens Federal savings institution | Deposits, loan books and borrower impact |
| Employment and training barriers | Booker T. Washington Business College | Students trained, verified placements, wages |
| Segregated lodging | A. G. Gaston Motel | Occupancy, construction financing, payroll |
| Limited media ownership | Broadcasting interests | Original acquisition terms and audited finances |
DIMENSIONS OF THE PROBLEM
The burial society provided certificate-based protection and funeral services; policy claims and payment records remain necessary to assess outcomes.
Citizens Federal offered a Black-led thrift institution under a federal charter; loan files are required to measure access.
Business education and the Gaston Motel addressed important needs in segregated Birmingham, but outcomes require operating records.
HOW THE PROBLEM SHOWED UP
Burial protection and funeral services addressed costs families faced. Premium, benefit and claims records are still needed to measure who received protection and what was paid.
Citizens Federal provided an institutional response to financial-service barriers. Deposits, loan approvals and borrower records are needed to establish the extent of access.
The Business College and Gaston Motel addressed skilled-work preparation and accommodations in segregated Birmingham. Verified placements, wages, occupancy and payroll are needed to measure outcomes.
EVIDENCE & CONTEXT
| Barrier | Related institution | Measurement still needed |
|---|---|---|
| Funeral expenses | Burial Society / Smith & Gaston | Premium, benefits and claims ledger |
| Restricted lending | Citizens Federal | Deposits, loan approvals and borrower records |
| Skilled work and lodging | Business College / Gaston Motel | Verified employment placements, occupancy and payroll |
A need and an institutional response are not themselves proof that every household was served or that inequality was removed.
THE RECORD & ITS LIMITS
Statements about discrimination describe the business environment and should not be treated as proof of a particular company's performance or customer outcomes.
HISTORY WITH RECEIPTS™
Claims remain subject to individual source review. Additional archival material will be added as evidence is recovered.
What He Built
TAKEAWAY: The Gaston network comprised connected but distinct operations. Shared names and relationships do not make them one corporation or establish automatic legal succession.
WHAT HE BUILT
The Gaston enterprise network combined service delivery with institutions that managed premiums, savings, skills, facilities and communications. It should be understood as a portfolio of historically connected operations rather than one undifferentiated corporation.
Enterprises and documentary status
| Enterprise | Historical role | Evidence anchor |
|---|---|---|
| Booker T. Washington burial-insurance enterprise | Burial protection; incorporated December 22, 1931, under its historical name. | Alabama insurance examination |
| Smith & Gaston Funeral Directors | Funeral operations and later cemetery ownership. | 1955 court opinion |
| Booker T. Washington Business College | Business, secretarial and accounting instruction; college's modern corporation index suggests a later 1966 incorporation. | 1966 congressional letters |
| Citizens Federal savings institution | Savings and lending; historical charter and conversion records requested. | Federal regulator research ongoing |
| A. G. Gaston Motel | Birmingham hotel opened in 1954 and associated with civil-rights history. | NPS historical study |
| Booker T. Washington Broadcasting Service | Vehicle for reported mid-1970s radio-station acquisition. | FCC application files requested |
| Grace Hill Cemetery | Acquired by Smith & Gaston in 1948. | Alabama Supreme Court |
THE ENTERPRISE SYSTEM
Recurring dues financed contractual protection. A 1933 card preserves certificate and collection entries.
A 1932 itemized invoice documents casket, embalming, hearse and transport charges; a court opinion records a cemetery acquisition.
These enterprises had separate operational, regulatory and ownership records; do not treat them as one undifferentiated corporation.
EVIDENCE & CONTEXT
| Operating system | Inputs and activity | Documentable outputs |
|---|---|---|
| Protection | Dues, premiums and reserves | Certificates, claims and liabilities |
| Physical services | Staff, supplies, vehicles and property | Invoices, payrolls and deeds |
| Banking and education | Deposits, loans, teaching and recruitment | Loan books, graduates and verified placements |
A portfolio diagram helps explain breadth, but evidence does not establish a particular financial transfer among any two enterprises without transaction records.
THE RECORD & ITS LIMITS
An enterprise's appearance in this table does not imply uniform or continuous personal ownership. Transactions and entities are being traced separately.
New primary-source insurance evidence: 1931 transition
The Alabama Superintendent of Insurance reported that the Booker T. Washington Burial Society, Fairfield, was reinsured in the Booker T. Washington Burial Insurance Co., Fairfield, on December 31, 1931. This is contemporaneous state regulatory evidence of the organizational transition into the insurance company. The table does not name A. G. Gaston personally, so BEHI uses it to document the enterprise rather than to assign every reported figure directly to him.
HISTORY WITH RECEIPTS™
Claims remain subject to individual source review. Additional archival material will be added as evidence is recovered.
Accomplishments
TAKEAWAY: Gaston’s strongest achievements are institutional and operational. Minnie L. Gaston’s educational leadership and advocacy deserve separate attribution within that history.
ACCOMPLISHMENTS
The strongest record of Gaston’s achievements is institutional: the creation or operation of businesses with durable legal and operational footprints. The education record also shows Minnie L. Gaston advocating nationally for access to vocational training and financing.
Documented milestones
- The December 22, 1931 incorporation of Booker T. Washington Burial Insurance Company is described in the 2004 official examination report.
- A 1955 Alabama Supreme Court opinion states Smith & Gaston acquired Grace Hill Cemetery in 1948.
- The National Park Service identifies the A. G. Gaston Motel as an important Birmingham historic site dating from 1954.
- In 1966 letters published by Congress, Minnie Gaston describes college courses and employer inquiries.
- The 1972 federal accreditation publication independently places the college on an accreditation list.
ACCOMPLISHMENT LEDGER
Dates and evidence classifications apply to the specific findings below. Economic significance is BEHI analysis; evidence limits remain attached to each entry.
| DATE / PERIOD | ACCOMPLISHMENT | ECONOMIC SIGNIFICANCE | SOURCE / LOCATOR | EVIDENCE CLASSIFICATION | EVIDENCE LIMITS |
|---|---|---|---|---|---|
| December 22, 1931 | Burial-insurance company formation The later official examination report records the incorporation of Booker T. Washington Burial Insurance Company. | Identifies a regulated institution within the burial-protection enterprise. | 2004 official examination report Official examination report, condition December 31, 2004. | ATTRIBUTED | This row uses the later report’s historical account; it does not merge similarly named earlier entities or establish initial paid capital. |
| 1948 | Grace Hill Cemetery acquisition The 1955 Alabama Supreme Court opinion states that Smith & Gaston acquired the cemetery in 1948. | Connects funeral services with a physical cemetery asset. | 1955 Alabama Supreme Court opinion 1955 Alabama Supreme Court opinion. | VERIFIED | The finding concerns the named company and acquisition, not Gaston’s personal wealth or the purchase financing. |
| 1954 | Development of the A. G. Gaston Motel The National Park Service identifies the motel and its 1954 history. | Documents an institution serving lodging and civic needs in Birmingham. | National Park Service NPS historical account of the motel. | ATTRIBUTED | Original conveyance, construction and financing instruments are separate evidence questions. |
| 1966 correspondence | Vocational-education leadership by Minnie L. Gaston Letters published by Congress describe the college’s courses and employer inquiries. | Documents a collaborator’s work connecting training with employment opportunities. | 1966 letters published by Congress 1966 congressional correspondence. | VERIFIED | Credit belongs to Minnie L. Gaston for these letters. Employer inquiries are not completed hires or a verified placement rate. |
ACCOMPLISHMENT CATEGORIES
State insurance statements and probate exhibits document burial services and business transactions.
The 1955 Alabama Supreme Court opinion documents the 1948 cemetery acquisition; filings record the later bank's legal history.
Congressional correspondence documents Minnie L. Gaston's role; unverified job-placement counts remain appropriately qualified.
EVIDENCE & CONTEXT
| Milestone | Evidence | Qualification |
|---|---|---|
| 1926 Burial Society | State regulator report | Company statistics, not personal assets |
| 1932–1933 customer transactions | Original probate exhibits | Specific invoices and certificate, not annual totals |
| 1956–2003 Citizens Federal | SEC-filed company statements | Later sale is not automatically Gaston's personal proceeds |
BEHI favors demonstrable milestones over broad claims of being first, largest or wealthiest without original comparative accounting.
THE RECORD & ITS LIMITS
The exact personal wealth, founding capital for each company, lifetime jobs created and cumulative charitable giving remain unresolved, and are not assigned precise unsupported figures.
HISTORY WITH RECEIPTS™
Claims remain subject to individual source review. Additional archival material will be added as evidence is recovered.
Economic Impact
TAKEAWAY: Employer requests, reported graduates, referrals, and verified hires are different measures. The inspected material does not establish a placement rate, wage effect, or verified employment total.
ECONOMIC IMPACT
Employee ownership plan — inspected federal filing extracts
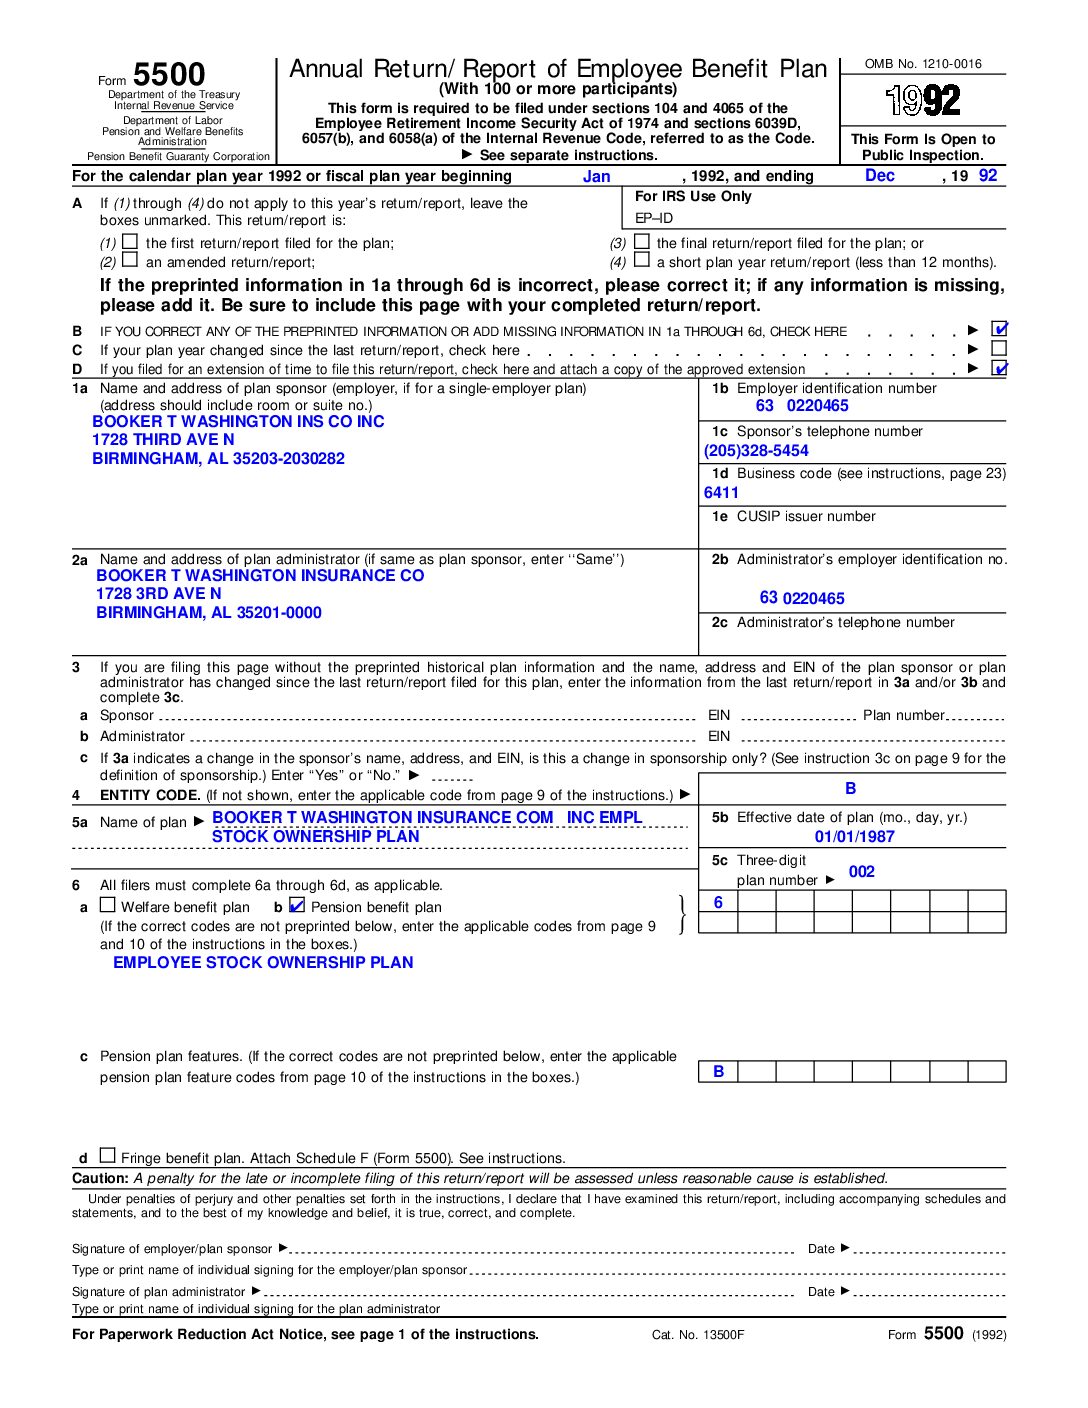
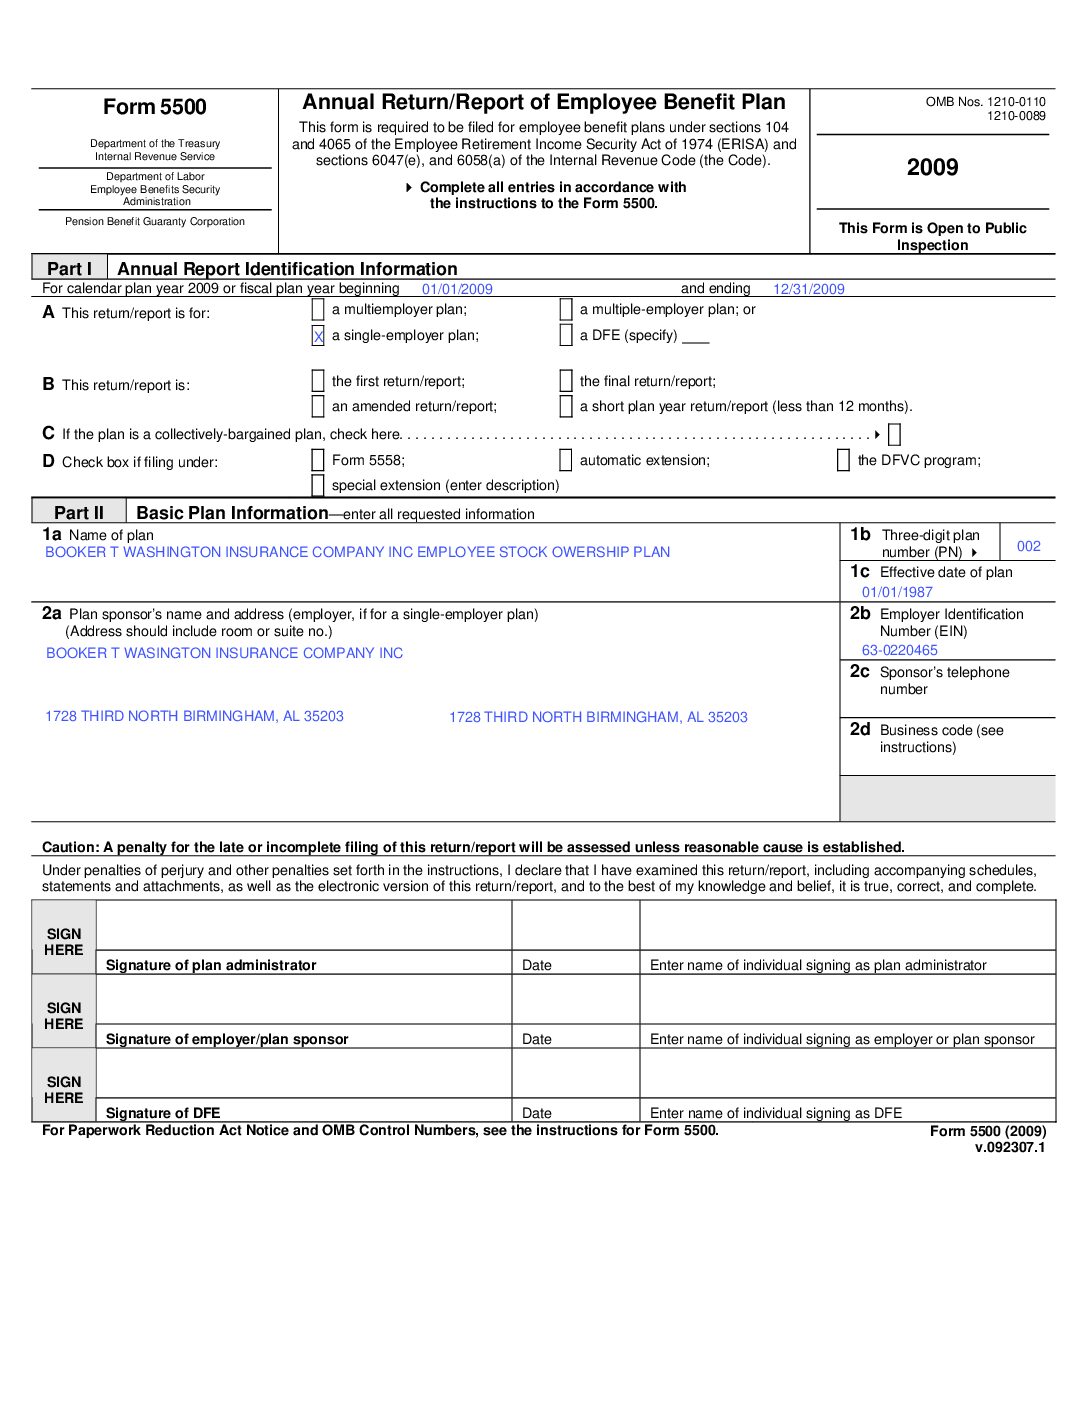
1992 and 2009 Form 5500, Booker T. Washington Insurance Company, Inc. ESOP, EIN 63-0220465, plan 002, released under FOIA 2027-F-00524. Both report January 1, 1987 as effective date. Classification: inspected plan-reported figures, not an independently inspected audit.
| Measure | Reported value | Locator |
|---|---|---|
| 1992 total / active participants | 296 / 205 | p. 2, item 7 |
| 1992 participants with account balances | 256 | p. 2, item 7g |
| Employer securities, beginning / end | $4,395,855 / $4,402,665 | 1992 p. 5, 31d(1) |
| Total assets, beginning / end | $4,895,855 / $4,402,665 | p. 5, 31f |
| Total liabilities, beginning / end | $1,278,155 / $888,319 | p. 5, 31k |
| Net assets, beginning / end | $3,617,700 / $3,514,346 | p. 5, 31l |
| Employer contributions received or receivable | $187,296 | p. 6, 32a |
| Direct benefit payments | $229,083 | p. 6, 32e |
| Interest expense | $54,858 | p. 6, 32f |
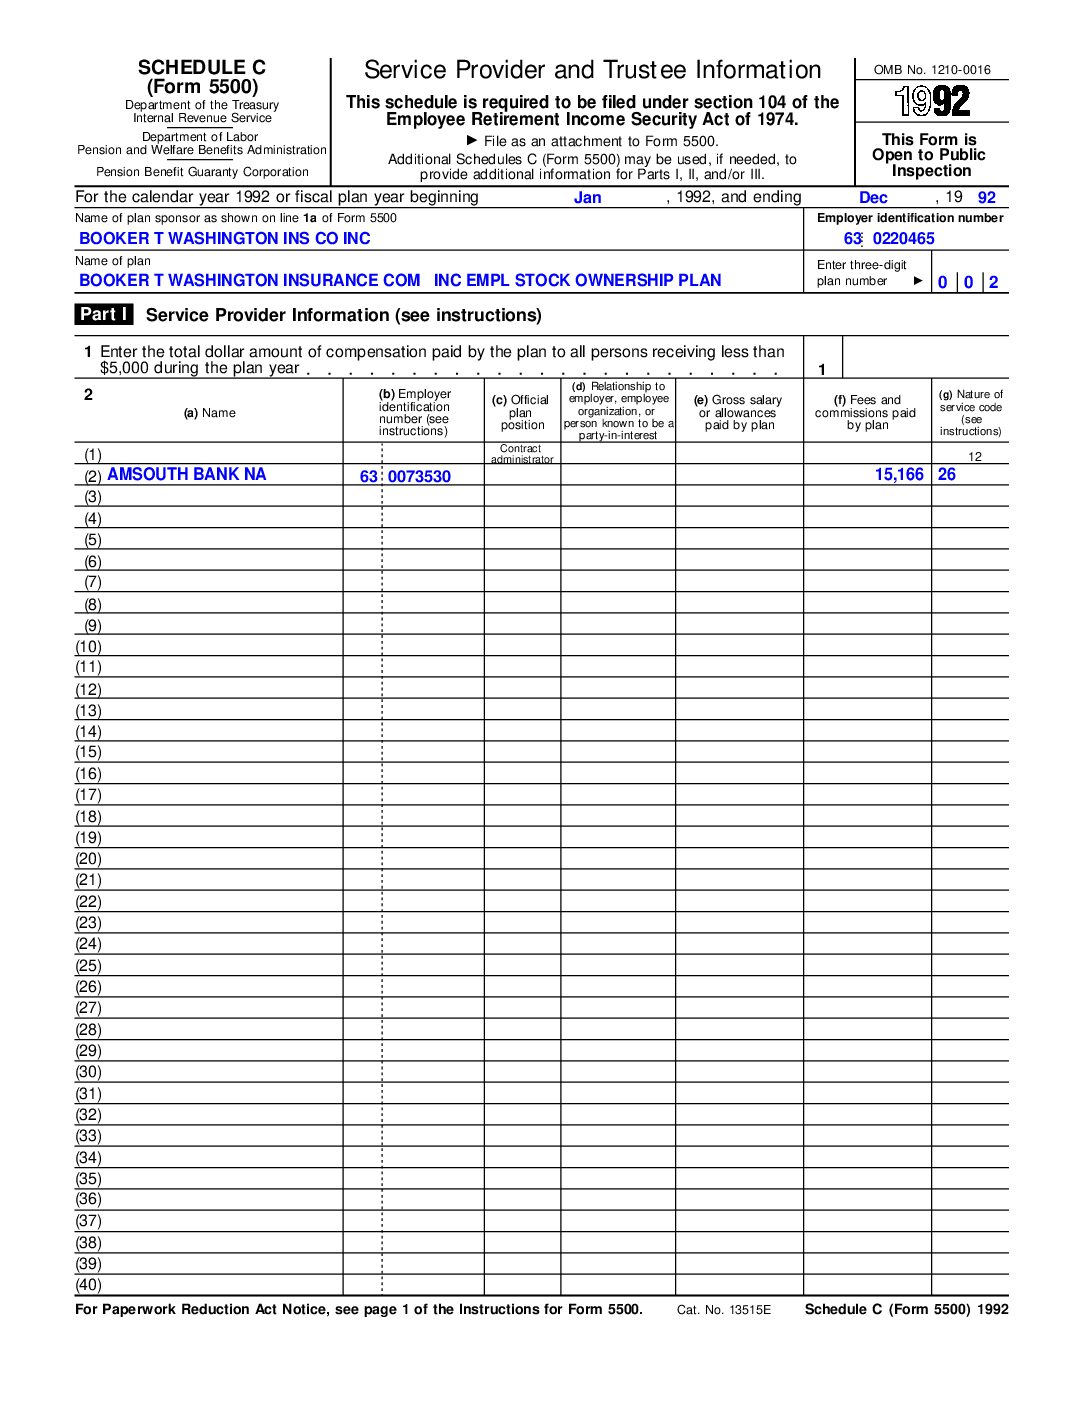
| Trustee expense / AmSouth compensation | $15,166 | 1992 p. 6, 32g; Schedule C p. 1 |
| 2009 total / active participants | 106 / 0 | 2009 p. 2, item 6 |
| 2009 receiving benefits / future benefits | 55 / 51 | p. 2, 6b–c |
| 2009 participants with account balances | 51 | p. 2, 6g |
Reconciliation: 1992 income $195,753 less expenses $299,107 equals a $103,354 decrease, reconciling opening and closing net assets. Schedule C names AmSouth Bank N.A. as trustee; its $15,166 fee matches the main form. The filing also reports sponsor-paid administrative expenses outside line 32g; listed plan expenses are not necessarily all administration costs.
Limits: Employer-security holdings are plan assets, not the whole company valuation or Gaston’s wealth. These filings do not establish original purchase price, ownership percentage, equal worker allocations or Gaston’s personal proceeds. Blank acquisition indebtedness does not prove an originally debt-free purchase. Zero active participants in 2009 does not alone establish termination.
Missing attachments: 1992 accountant opinion, financial statements/notes and investment schedule; 2009 Schedules H and R marked attached but not supplied. No 2009 asset totals are inferred. 1987–1990 filings remain unrecovered; EBSA reports no retained pre-1992 filings. Completeness clarification requested; legacy SPD referral to PBGC remains open. Source coverage.
Employment outcomes — evidence distinctions
Employer demand: Minnie L. Gaston's correspondence reported more than 250 requests for workers; these are requests for personnel, not a count of completed placements. Reported graduates: a contemporary 1965 account attributed more than 8,000 graduates to the college; this figure has not been reconciled with enrollment and graduation registers. Named placements: the 1966 Senate hearing points to a partial list of employers and graduates in the 1965 House H.R. 6468 hearing, pp. 104–107. The underlying pages, employer names, positions, and resulting employment outcomes await inspection.
BEHI will distinguish (1) employer inquiries, (2) referrals, (3) documentary evidence of hires, and (4) independently corroborated employment outcomes. No placement rate, wage impact or verified employment total can yet be calculated from the material inspected.
Measured economic activity — 1946 advertising evidence: Correspondence, advertising statements and receipts preserved in NAACP Records, Library of Congress, Box II:F4, document Booker T. Washington Business College's paid advertising relationship with The Crisis and related correspondence involving Smith & Gaston. These show a specific historical marketing activity and business administration, not a reliable measure of the college's total advertising expenditures, student recruitment, revenue, or employment outcomes. Several $4.90 entries require reconciliation before totals can be reported. See Receipts for the primary-source citation and limitations.
Economic impact is best assessed through measurable business services, capital access, training and employment—not unverified estimates of one man's fortune. This section distinguishes observed records, reported figures and outcomes requiring original ledgers.
Separate measures—not interchangeable totals
| Measure | Available evidence | How BEHI interprets it |
|---|---|---|
| College enrollment | 473 students reported for fall 1986 in a federal directory. | A point-in-time headcount, not cumulative graduates or tuition revenue. |
| Published college tuition | $925 figure reported for 1987–88. | Published tuition indicator, not collected fees or net income. |
| Employer demand | Minnie Gaston reported 250-plus requests for clerical staff in 1966. | Recruitment requests, not confirmed placements. |
| Reported alumni | A contemporary report attributed 8,000-plus graduates to Minnie in 1965. | Reported claim; audited graduate rosters pending. |
| Funeral financing | A $50,000 arrangement is described in secondary accounts. | Do not classify as confirmed loan before original mortgage. |
| Insurance statements | Alabama insurer examination report | Company-level condition, ownership and accounting findings; not personal net worth. |
KEY ECONOMIC INDICATORS
Each measure identifies its entity, period, source and evidence limits. Dollar amounts are nominal historical U.S. dollars. Assets, revenue, profit, transaction amounts and employment measures are distinct. “Not yet established” identifies a research gap, not zero or “not applicable.”
| MEASURE / VALUE | ENTITY / PERIOD | SOURCE / LOCATOR | CONTENT CONDITION / EVIDENCE CLASSIFICATION | INTERPRETATION / LIMITS |
|---|---|---|---|---|
| Total income $11,597.66 | Booker T. Washington Burial Society 1926 | Alabama insurance report, 1926; printed p. 414 / PDF p. 415. | Documented VERIFIED | Inspected regulatory report; Society income, not Gaston’s personal earnings. Corporate continuity requires separate evidence. |
| Certificates in force 1,000 | Booker T. Washington Burial Society December 31, 1926 | Alabama insurance report, 1926; printed p. 414 / PDF p. 415. | Documented VERIFIED | Certificates outstanding, not employment, profit or people enriched. |
| Admitted assets $52,313.54 | Booker T. Washington Burial Insurance Company December 31, 1936 | Alabama insurance report, 1936; printed p. 176 / PDF p. 181; HathiTrust hvd.hl2d7u. | Documented VERIFIED | Company assets, not personal wealth. Do not merge distinct corporate entities or periods. |
| Total income $57,363.60 | Booker T. Washington Burial Insurance Company 1936 | Alabama insurance report, 1936; printed p. 176 / PDF p. 181; HathiTrust hvd.hl2d7u. | Documented VERIFIED | Income before disbursements; not net profit. |
| Verified employment placements Not yet established | Booker T. Washington Business College Reporting period not established | Research gap; see Evidence & Context and Receipts. | Not yet established Evidence classification: not assigned to an unresolved answer. | Reported employer requests and graduates do not establish hires, placement rates or wage outcomes. Research Gap: Verified employment placements |
For evidence-label definitions, see the Receipts evidence guide.
CHANNELS OF ECONOMIC IMPACT
Regulatory reports identify admitted assets, revenue, obligations and certificates; different corporate identities and years must not be collapsed.
250-plus reported employer inquiries differ from hires; 8,000-plus reported graduates await institutional register reconciliation.
The 2002 SEC-filed statement reports assets, deposits and loans at the institution level, decades after founding.
EVIDENCE & CONTEXT
| Measure | Illustrative evidence | Correct interpretation |
|---|---|---|
| 1926 certificates | 1,000 reported in force | Certificates outstanding, not customers personally enriched |
| 1931 insurer admitted assets | $9,511.46 | Insurer's admitted assets, not shareholder wealth |
| March 2002 bank assets | $108 million reported | CFS corporate assets, not Gaston's estate |
| Employer requests | More than 250 reported | Staff requests, not verified job placements |
Company assets, premium income, deposits, employment inquiries and personal net worth are five distinct quantities. Any chart must label entity, year, source and unit.
THE RECORD & ITS LIMITS
Financial analysis must distinguish corporation from owner; premiums from earnings; asset values from profits; applications from enrolled students; and referrals from hired graduates.
1936 regulatory financial statement — Booker T. Washington Burial Insurance Company
Inspected state report, printed p. 176 (PDF page 181) and insurance-activity comparison, printed p. 146 (PDF page 151). Values below represent the company, in nominal dollars.
| Measure | 1936 reported figure |
|---|---|
| Capital stock | $6,050.00 |
| Total income | $57,363.60 |
| Total disbursements | $49,807.34 |
| Admitted assets | $52,313.54 |
| Liabilities | $28,755.52 |
| Surplus over liabilities and capital | $17,508.02 |
| Insurance in force at year-end | $1,450,742.00 |
1935 comparative correction: The 1936 regulator's activity table shows $1,127,321.00 of insurance in force at December 31, 1935, for the Booker T. Washington Burial Insurance Company. A previously published $278,190.00 figure was attached to the wrong company row and must not be treated as Gaston's insurer's 1935 coverage. The other previously displayed 1935 values have been withdrawn pending line-by-line rereading of the 1935 tables; the 1936 comparative year-end figure is not a substitute for all financial statements.
Primary source: Alabama Superintendent of Insurance, Annual Report for the Year Ending December 31, 1936, print pp. 146 and 176; digitized HathiTrust volume hvd.hl2d7u. Regulatory company income, insurance in force, assets, and surplus are not Gaston's personal income or wealth.
1926 regulatory financial baseline — Booker T. Washington Burial Society
Alabama's published annual report records the early activities of the burial society headed by A. G. Gaston. Values are 1926 nominal U.S. dollars and refer to the Society, not Gaston's personal finances or the distinct Booker T. Washington Life Insurance Company.
| Reported measure | 1926 amount |
|---|---|
| Total income | $11,597.66 |
| Total disbursements | $12,103.24 |
| Admitted assets at December 31 | $1,345.17 |
| Liabilities, excluding capital | $531.64 |
| Reported surplus over liabilities | $813.53 |
| Certificates in force, December 31 | 1,000 |
Interpretation: The report demonstrates a functioning burial-assistance enterprise with stated service activity and contemporaneous financial reporting. Income, expenditure, surplus, asset value and insurance coverage are different measures; none is a statement of A. G. Gaston's personal net worth. Do not assume this 1925-chartered Society is legally identical to the enterprise later described as incorporated in 1931 without the underlying corporate chain.
Primary source: Alabama Superintendent of Insurance, Annual Report for the Year Ending December 31, 1926, printed p. 414 / digital PDF p. 415 (Gerry Waters research transmission, October 2026); Alabama Department of Archives and History, State Publications Database. Read the document locator and evidence qualifications in the Receipts tab.
1935 company comparison — historical correction
Prior 1935 numerical table withdrawn: The old comparative entry incorrectly attributed $278,190 insurance in force and associated amounts to Booker T. Washington Burial Insurance Company. The 1936 Alabama report instead records $1,127,321 of insurance in force at December 31, 1935, for the Booker T. Washington company. Other 1935 accounting figures previously displayed here are withheld until the 1935 source tables can be checked against the correct company row. The withdrawn table is not evidence of Gaston company financial condition.
See the corrected 1936 regulator statement and the Receipts correction log. 1936 regulatory source, printed p. 146, PDF p. 151. Original 1935 reproduction preserved pending reconciliation.
Early insurance-company financial snapshots
| Year | Capital | Income | Disbursements | Admitted assets | Liabilities* | Surplus |
|---|---|---|---|---|---|---|
| 1931 | $5,000.00 | $32,485.16 | $32,586.94 | $9,511.46 | $4,406.00 | Not stated in cited table |
| 1933 | $5,000.00 | $29,022.47 | $26,976.52 | $19,002.73 | $5,554.49 | $8,448.24 |
*Liabilities excluding capital stock. These figures are company-level regulatory data and should not be treated as Gaston’s personal income, wealth, or ownership percentage.
HISTORY WITH RECEIPTS™
Claims remain subject to individual source review. Additional archival material will be added as evidence is recovered.
Timeline
TAKEAWAY: The chronology follows dated institutional records while retaining unresolved early dates and transfers. Separate banks or entities do not become legal successors through timeline proximity.
TIMELINE
This working chronology privileges dated institutional documents. Early-business dates and later property transfers remain subject to amendment as originals are received.
Working timeline
| Year | Event | Classification | |
|---|---|---|---|
| 1892 | Arthur George Gaston born in Demopolis, Alabama. | ATTRIBUTED | |
| 1920s | Smith & Gaston funeral-services enterprise emerges in historical accounts. | ATTRIBUTED | |
| 1925 | Alabama's 1926 insurance report identifies the Booker T. Washington Burial Society under A. G. Gaston and Creola Gaston as incorporated in July 1925 and operating from July 19, 1925. | DOCUMENTED — 1926 REGULATORY REPORT | |
| 1926 | State report records the Society's income ($11,597.66), admitted assets ($1,345.17), and 1,000 burial certificates in force; printed p. 414 / PDF p. 415. | DOCUMENTED — 1926 REGULATORY REPORT | |
| 1928–1929 | Separate Booker T. Washington Burial Society, Inc. registration 000-808-983 formed December 4, 1928, and dissolved July 20, 1929. Named incorporators include A. G. Gaston, Creola Gaston, A. L. Smith and Bessie Smith. | STATE REGISTRY CONFIRMED | |
| 1931 | Booker T. Washington Insurance Company, Incorporated, registration 000-019-662, formed December 22 with A. G. Gaston, Creola Gaston and Abe L. Smith as incorporators. The 1925 nonprofit registration 000-808-981 remained listed until January 26, 1932; original transfer or succession filings remain unexamined. | FORMATION VERIFIED; SUCCESSION UNRESOLVED | |
| 1936 | State insurer report records $57,363.60 income, $52,313.54 admitted assets, and $1,450,742 of insurance in force for the Booker T. Washington Burial Insurance Company. | DOCUMENTED REGULATORY REPORT | |
| 1946 | Secretary of State records December 27 name change from The Booker T. Washington Burial Ins. Co. Inc. to Booker T. Washington Insurance Company, Incorporated. | STATE REGISTRY CONFIRMED | |
| 1938 | Reported expansion of funeral premises and possible $50,000 financing. | ATTRIBUTED | |
| 1939 | Widely cited founding period for Booker T. Washington Business College; verify against early catalogs. | ATTRIBUTED | |
| 1948 | Smith & Gaston acquired Grace Hill Cemetery according to 1955 court opinion. | VERIFIED | |
| 1954 | A. G. Gaston Motel begins operations in Birmingham. | ||
| February 1954 | Surviving motel architectural sheets are dated as early as February 1954 according to National Park Service preservation research. Original drawings and the full plan set remain to be acquired and independently inspected. | SECONDARY SOURCE | |
| December 1954 | National Park Service historic documentation reports the addition of a restaurant building east of the motel's original coffee shop. The December 27, 1954 Board of Equalization photographs are a separate contemporaneous visual-evidence lead; neither the original building permit nor the restaurant-addition permit has been recovered. | SECONDARY SOURCE | VERIFIED |
| September 1956 | SEC-filed company statement dates Citizens Federal federal charter to September 1956; original charter and opening records outstanding (issuer also describes bank as founded in 1957). | ATTRIBUTED — SEC-FILED COMPANY STATEMENT | |
| 1965–1966 | Minnie Gaston documents vocational education and employment needs in congressional materials. | VERIFIED | |
| 1966 | December 20 college incorporation appears in secondary corporate index; original requested. | ATTRIBUTED | |
| 1972 | Federal publication lists business college as accredited. | VERIFIED | |
| 1975–1976 | Reported WENN/WENN-FM acquisition through a Gaston-related broadcast company; FCC originals requested. | ATTRIBUTED | |
| 1983 | March 28: Citizens Federal converted from federal mutual savings and loan to federal stock association, issuing 130,000 shares. October 10: converted to federal stock savings bank. | ATTRIBUTED — SEC-FILED COMPANY STATEMENT | |
| 1987 | 1992 and 2009 Form 5500 report January 1, 1987 as the ESOP effective date. Original transfer instruments remain outstanding; see later filings and limits. | ATTRIBUTED | |
| 1988 | Federal closed-school listing reports May 31 closure of business college. | VERIFIED | |
| 1996 | Gaston dies in Birmingham. | ATTRIBUTED | |
| 1998 | June 30: Citizens Federal became a wholly owned subsidiary of CFS Bancshares, Inc. | ATTRIBUTED — SEC-FILED COMPANY STATEMENT | |
| 2002–2003 | Acquisition agreement announced May 2002; transaction completed February 28, 2003, with Citizens Federal merging into Citizens Trust Bank. Subsequent Form 10-K reports about $9.055 million aggregate purchase price. | SEC-FILED CORPORATE REPORT |
Banking context before Citizens Federal
1890: Reverend William Reuben Pettiford opened Alabama Penny Savings Bank in Birmingham, October 15, 1890. 1915: Following a merger with Prudential Savings Bank, the predecessor institution failed and its assets were liquidated. 1956: Gaston's Citizens Federal received its federal charter. These are milestones involving separate institutions; they are not a proven corporate succession.
Property title gap: Published municipal history reports that Gaston later purchased the former Penny Savings Bank building, but the original deed and intervening owners are still under investigation. Sources: Encyclopedia of Alabama and City of Birmingham.
TIMELINE AT A GLANCE
1925–1933 state filings, insurer statements, funeral invoice and payment certificate.
Later school, motel and cemetery milestones must be tied to each institution's own source records.
1983 Citizens Federal conversions, 1998 holding-company structure and 2003 acquisition occurred across a changing corporate history.
EVIDENCE & CONTEXT
| Date | Event | Documentary qualification |
|---|---|---|
| 1925–1926 | Early burial society formation and financial report | Three distinct registration trails require reconciliation |
| 1931–1933 | Insurance reinsurance transition and company records | Succession documents remain research targets |
| 1954–1956 | Motel and Citizens Federal developments | National Park Service history and SEC-filed statement |
| 1983–2003 | Bank conversions and acquisition | Some developments occurred after Gaston's 1996 death |
An event after 1996 belongs to institutional succession, not to an action personally performed by Gaston after his death.
THE RECORD & ITS LIMITS
December 31, 1931 — regulatory transition documented
The Alabama Superintendent of Insurance reported that Booker T. Washington Burial Society of Fairfield was reinsured in Booker T. Washington Burial Insurance Co. of Fairfield. This contemporaneous regulatory record independently documents the transition in the enterprise structure.
A reported closure date does not establish corporate dissolution date. School operations, state authorization, accreditation and corporate existence are distinct.
March 29, 1954 — motel land transfer (secondary documentation)
National Park Service historical documentation dates the transfer of four parcels from Booker T. Washington Insurance Company to A. G. Gaston Motels, Inc. to March 29, 1954. A reported $64,637.72 consideration and the precise recorded deed remain subject to primary-source verification. Original incorporation and financing records have been requested.
HISTORY WITH RECEIPTS™
Claims remain subject to individual source review. Additional archival material will be added as evidence is recovered.
No verified records are currently published in this category.
Myths & Disputes
TAKEAWAY: Shared names and overlapping participants do not prove corporate identity or succession. Claims about transferred policies, assets, and ownership require original instruments.
MYTHS & DISPUTES
Popular narratives often compress multiple businesses and decades into one dramatic success story. BEHI retains distinctions that are essential for historical accounting.
1925–1931: one trade name, three registration records
Alabama Secretary of State identifiers 000-808-981 (1925), 000-808-983 (1928), and 000-019-662 (1931) refer to three distinct filings. Overlapping family names and the shared Booker T. Washington designation do not prove identity or automatic succession. In particular the 1925 nonprofit registry lists Creola A. Gaston, Bessie Smith and Ella Fulton as incorporators, while A. G. Gaston's 1926 presidency is evidenced independently by the regulatory report. Original formation, dissolution and assignment instruments are needed to trace transfer of policies and assets.
Entity-name collision in the original insurance reports
Documented distinction: The 1926 regulatory report's Booker T. Washington Burial Society was headed by A. G. Gaston and Creola Gaston (printed p. 414). The neighboring Booker T. Washington Life Insurance Company was headed by B. L. Windham and J. W. Gillispie (printed p. 415), with its own 1921 incorporation date and financial statements. Similar naming is not evidence of common ownership. BEHI excludes the latter company's figures from Gaston's financial history unless later primary evidence establishes a specific relationship.
The 1926 report retrospectively records a July 1925 incorporation for Gaston's Society. An additional December 1931 insurance-enterprise incorporation appears in the existing research. Their legal relationship is UNRESOLVED, pending the respective incorporation instruments, amendments and regulatory succession trail.
Claims and evidentiary tests
| Claim | Current assessment | Evidence needed |
|---|---|---|
| Gaston personally owned the full value of every enterprise | Not established: businesses were distinct legal entities. | Stock ledgers, shareholder registers and estate inventory |
| The 1938 funeral expansion was financed by a $50,000 Brown-Service mortgage | Reported; lender entity and loan terms not verified. | Recorded mortgage and property deed |
| All 250-plus employment requests led to jobs | Incorrect inference; requests are not hires. | Placement bureau reports and employer records |
| The college began only in 1966 | A later incorporation date would not disprove earlier instruction. | 1930s advertisements, charter and licensing records |
| The 1987 ESOP proves all workers received an equal ownership interest | Not established. | Plan trust, participant allocations, Form 5500 and transaction documents |
| The insurance enterprise remained financially healthy throughout its history | Official late-period examination raises serious financial-record and solvency concerns. | Annual statements and examination chronology |
COMMON SOURCES OF CONFUSION
Penny Savings Bank was earlier, but Prudential Savings also existed; a precise ordinal claim is not established.
The 1926 Booker T. Washington Burial Society and adjacent Booker T. Washington Life Insurance Company had different officers and financial tables.
A reported 1987 employee stock plan does not establish equal shares; assets reported for separate corporations do not establish individual net worth.
EVIDENCE & CONTEXT
| Claim | Present assessment | Evidence needed |
|---|---|---|
| All early burial entities were one corporation | Not proved by shared names or personnel | Signed incorporation, transfer and dissolution instruments |
| 250 employer inquiries mean 250 hires | Incorrect inference | Placement rosters, employer records |
| 13,000 shareholders in 1967 Citizens Federal | Conflicts with later description of mutual status until 1983 | Contemporaneous member statements and charter records |
Corrections remain visible. A source reporting a claim proves that claim was reported; it may not independently verify that the underlying event or amount occurred.
THE RECORD & ITS LIMITS
Disputes are identified to prevent unwarranted certainty, not to suggest that all claims have equal evidentiary support.
HISTORY WITH RECEIPTS™
Claims remain subject to individual source review. Additional archival material will be added as evidence is recovered.
No verified records are currently published in this category.
Legacy
TAKEAWAY: Gaston’s legacy includes economic institutions and a civil-rights landmark. Minnie L. Gaston’s leadership and later institutional developments retain their own attribution.
LEGACY
Gaston’s legacy lies in building economic institutions under segregation and in the subsequent roles those institutions played in Birmingham. The motel is also part of the nationally significant civil-rights landscape. Minnie Gaston's work in business education and advocacy deserves clear attribution as independent leadership within this network.
Legacy across generations
- Insurance and funeral enterprises illustrate durable demand for services and the need to examine the cash flows behind their expansion.
- Banking and education initiatives created infrastructure for saving, borrowing, vocational skills and professional access.
- The A. G. Gaston Motel carries preservation significance in addition to its original commercial function.
- Contemporary federal correspondence makes Minnie Gaston a named historical actor in educational policy and workforce preparation.
- Later business reorganization and financial distress remain part of the record and must not be erased from an institutional history.
CHANNELS OF LEGACY
The burial and funeral enterprises illustrate durable commercial systems; records are needed to trace corporate continuity.
Citizens Federal developed through conversions and merger; its successor record continues beyond Gaston's lifetime.
The Gaston Motel occupies a recognized civil-rights preservation landscape, while Minnie Gaston's correspondence supports her independent role.
EVIDENCE & CONTEXT
| Legacy channel | Surviving evidence | Unresolved issue |
|---|---|---|
| Institutions | Insurance reports and SEC-filed bank documents | Ownership chain and financial continuity |
| People | Minnie Gaston correspondence and John Drew contact lead | Individual contributions and corroborated recollections |
| Places | Motel historical research and Penny Savings building lead | Deed chain and acquisition financing |
Legacy encompasses documented achievements, collective labor, later institutional changes and financial vulnerabilities; it is not a single net-worth claim.
THE RECORD & ITS LIMITS
Legacy cannot be reduced to a single net-worth estimate. BEHI will expand this assessment as employment, property, insurance and corporate records are delivered.
HISTORY WITH RECEIPTS™
Claims remain subject to individual source review. Additional archival material will be added as evidence is recovered.
Company Records
TAKEAWAY: Separate registry identifiers and operating reports establish specific entity facts. They do not alone prove policy transfers, asset continuity, stock ownership, or legal succession.
COMPANY RECORDS
Alabama state corporate register — three distinct formations, 1925–1931
| Formation date | Entity and Secretary of State number | Documented incorporators and status |
|---|---|---|
| July 16, 1925 | Booker T. Washington Burial Society, Inc.000-808-981; domestic nonprofit corporation | Creola A. Gaston, Bessie Smith and Ella Fulton. Dissolved January 26, 1932. |
| December 4, 1928 | Booker T. Washington Burial Society, Inc.000-808-983; domestic corporation | A. G. Gaston, Creola Gaston, A. L. Smith and Bessie Smith. Authorized capital $20,000; paid-in capital $2,000; dissolved July 20, 1929. |
| December 22, 1931 | Booker T. Washington Insurance Company, Incorporated000-019-662; domestic corporation | A. G. Gaston, Creola Gaston and Abe L. Smith. State database lists authorized capital $1,250,000 and paid-in capital $5,000 (not necessarily initial capitalization). Name changed December 27, 1946 from 'The Booker T. Washington Burial Ins. Co. Inc.' Dissolved November 2017. |
Official state registry sources: 1925 registration · 1928 registration · 1931 registration. Registry screenshots received from research correspondent Gerry Waters, October 14, 2026.
Interpretive boundary: These are separate state entity identifiers. The 1926 insurance report identifies A. G. Gaston as president of the operating Burial Society but does not make him an incorporator in the 1925 state list. No legal successor, policy transfer, capitalization transfer, stock ownership chain, or asset continuity is established solely by these entries. Signed original charters, corporate amendments, dissolution and transfer files remain research targets.
1925–1926 insurer records recovered — legal identity not presumed
Published primary record in BEHI digital research custody: Alabama Superintendent of Insurance, Annual Report for the Year Ending December 31, 1926, printed p. 414 (PDF p. 415). It identifies the Booker T. Washington Burial Society of Fairfield with A. G. Gaston as president, Creola Gaston as secretary, a July 1925 incorporation date and a July 19, 1925 commencement date. The page preserves a 1926 financial abstract and an end-of-year count of 1,000 certificates. The adjacent p. 415 (PDF p. 416) instead concerns Booker T. Washington Life Insurance Company (1921; B. L. Windham) and must not be imported into Gaston's accounts.
Evidence-state distinctions: Report for 1926 inspected; report supplied under filename for 1929 actually covers 1925; actual 1929 report not yet secured. The later 1931 corporate filing remains a separate documentary lead until original incorporation and amendment instruments establish whether it was a new entity, reorganization or statutory conversion. Alabama Department of Archives and History, State Publications Database lists annual publications but is not itself the underlying scanned financial statement.
Register placement: Financial; Incorporation; Reports & Correspondence; Legal & Regulatory. Preserve the complete original PDFs privately. The specific 1926 source-image page is available for controlled extraction and public use review but has not yet been embedded in this web Profile.
Archival recovery register — October 13, 2026
- Alabama Department of Archives and History — inquiry sent: 1930–1940 annual insurance reports, insurer-specific financial tables, early corporate/regulatory records and burial-society transition documentation. Original records outstanding.
- Alabama Department of Insurance, Financial Examiners Division — inquiry sent: original annual financial statements, examinations, premiums, assets, liabilities, reserves, capitalization and policies in force. Original records outstanding.
- Library of Congress Manuscript Division — inquiry sent: 1946 NAACP Records file concerning Booker T. Washington Business College. A separate 1946 Box II:F4 correspondence scan is already documented in the Receipts section; do not conflate the pending inquiry with the materials already inspected.
- 1965 House hearing H.R. 6468: identified testimony volume, pages 104–107, employer-placement list; pages pending recovery.
- College corporation file: Alabama historical entity 019-660, with the reported 1966 incorporation awaiting the original certified filing. Distinguish corporate registration from the college's earlier operation.
- College catalog: 1949–1952 catalog identified through a listing, but not yet examined or reproduced.
Research status: inquiries submitted and bibliographic leads identified; neither absent scans nor unverified accounting figures are presented as recovered corporate records.
Contracts & Transactions / Operational Records — inspected 1946 documents: NAACP Records, Library of Congress, Box II:F4, PDF pp. 1–4. Contemporary Smith & Gaston and Booker T. Washington Business College correspondence, The Crisis advertising statements, payment acknowledgments and business envelopes establish an advertising-related commercial correspondence trail. Some documents display $4.90 amounts, which must not be summed without matching invoices to receipts. The records do not establish ownership structure, incorporation dates or total expenditures. Scans are held privately pending reproduction-rights review; see Receipts for archival citation and limits.
The Company Records register covers eight categories. An archival locator or an inquiry is not treated as if the requested original has already been inspected.
The earlier banking institution — Alabama Penny Savings Bank
| Period | Documented historical context | Evidence boundary |
|---|---|---|
| 1890 | Reverend William Reuben Pettiford and Birmingham associates established Alabama Penny Savings Bank. The institution began operations October 15, 1890, and is identified by the Encyclopedia of Alabama as Alabama's first Black-owned and Black-operated financial institution. | Published institutional history; original bank records not yet inspected by BEHI |
| 1913–1915 | Penny Savings built a five-story headquarters on Eighteenth Street in 1913. In 1915 it merged with the Black-owned Prudential Savings Bank and then failed in the same year. | Published historical account; deeds and merger/liquidation instruments outstanding |
| 1956 | Citizens Federal Savings & Loan Association was federally chartered under A. G. Gaston's leadership, renewing Black-owned savings and lending infrastructure in Birmingham after Penny Savings Bank's closure. | Charter date reported in SEC-filed company statement; historical comparison attributed to published scholarship |
Why the distinction matters: Historian David T. Beito's comparison, repeated in BLACKListed Culture, describes Citizens Federal as the first Black-owned financial institution in Birmingham since Penny Savings Bank closed. This does not establish Citizens Federal as the second such institution ever founded in Birmingham; the earlier Prudential Savings Bank also existed.
Building ownership research lead: The City of Birmingham reports that A. G. Gaston subsequently purchased the former Penny Savings Bank headquarters on Eighteenth Street for use by his businesses. This is a municipal historical account, not an inspected conveyance. BEHI must recover the original deed, seller, purchase date, consideration, financing and intervening title chain before labeling the transfer verified.
Source references: Encyclopedia of Alabama — Penny Savings Bank of Birmingham · City of Birmingham — Historic Black Main Street · Karen D. Brame, A. G. Gaston — BLACKListed Culture.
Citizens Federal — charter, conversion, acquisition
| Date | Corporate milestone | Evidence |
|---|---|---|
| September 1956 | Citizens Federal federally chartered and joined the Federal Home Loan Bank System. A 2002 statement also calls the institution founded in 1957; original charter and opening records are still sought. | 2002 SEC-filed issuer release |
| March 28, 1983 | Converted from a federal mutual savings and loan association to a federal capital-stock association through issuance of 130,000 common shares. | 2002 SEC-filed issuer release |
| October 10, 1983 | Converted from a federal stock savings and loan association to a federal stock savings bank. | 2002 SEC-filed issuer release |
| June 30, 1998 | Citizens Federal became a wholly owned subsidiary of CFS Bancshares, Inc. | 2002 SEC-filed issuer release |
| May 30, 2002 | Citizens Bancshares Corporation and Citizens Trust Bank publicly announced an agreement to acquire CFS Bancshares. | Contemporaneous announcement filed with SEC |
| February 28, 2003 | Acquisition of CFS Bancshares completed and Citizens Federal Savings Bank merged into Citizens Trust Bank. | 2004 Form 10-K filed with SEC |
Financial context: As of March 31, 2002, the merger announcement reported CFS Bancshares assets of $108 million, loans of $39 million and deposits of $98 million. The buyer's 2004 Form 10-K reports approximately $8.751 million in cash paid through December 31, 2004, plus $304,000 expected on remaining tendered shares, for an approximately $9.055 million total purchase price. These figures concern corporate entities and a later merger—not A. G. Gaston's personal net worth.
Primary sources: May 30, 2002 announcement (SEC Exhibit 99.2) · Citizens Bancshares Corporation, 2004 Form 10-K, Note 2 — Acquisition.
Evidence boundary: These are company statements preserved in SEC filings; BEHI has not recovered the original 1956 charter, 1983 conversion instruments, stock registers or complete stand-alone financial statements. Names appearing in later documents do not establish Gaston's individual equity or ownership percentage.
Eight categories of company evidence
| Register | What is known | Priority missing instrument |
|---|---|---|
| Incorporation | 1931 insurance incorporation documented in state report; later college corporation indexed under 019-660. | Signed original articles, amendments, stock subscriptions |
| Financial | 2004 Alabama regulator report reviews company finances and recordkeeping. | Early annual statements, loan files, trial balances |
| Operational | College curricula and recruitment letters; cemetery litigation. | Policy counts, payrolls, enrollment and placement ledgers |
| Contracts & Transactions | Motel, radio, bank and cemetery transactions identified as archival targets. | Signed purchase agreements, deeds, FCC assignment exhibits |
| Legal & Regulatory | 1955 cemetery case, 1972 accreditation listing. | Court exhibits, banking charter and licensing files |
| Intellectual Property | Business names and marks were used across subsidiaries. | Historical registration certificates, mark ownership files |
| Ledgers & Accounts | Public regulator materials and published school statistics serve as partial leads. | General ledgers, burial-insurance premiums, bank deposit records |
| Reports & Correspondence | 1966 letters; 1946 archival correspondence lead. | Original incoming employer replies and annual institutional reports |
EIGHT CATEGORIES OF COMPANY RECORDS
State registration summaries identify 1925, 1928 and 1931 separate formations; originals and stock registers remain pending.
Original insurer reports, probate invoices and collection cards provide company-level accounting and individual transaction examples.
SEC documents identify charter, conversions and acquisition; original federal charter and Eighteenth Street deeds remain targets.
EVIDENCE & CONTEXT
| Company-record category | Current evidence | Priority missing record |
|---|---|---|
| Incorporation; legal & regulatory | State registry entries and published court opinions | Signed articles, amendments and land deeds |
| Financial; ledgers & accounts | State annual insurance reports; individual receipts | Audited statements and general ledgers |
| Operational; contracts & transactions | 1932 invoice; 1933 dues card; 1946 correspondence | Payroll, signed transactions and financing |
| Intellectual property; reports & correspondence | Published materials, regulator reports and college letters | Trademark records, correspondence registers |
The eight categories are a classification system, not a claim that all original records have been recovered. Preserve source distinctions and the full existing document links.
THE RECORD & ITS LIMITS
A negative archival search is a gap, not proof a transaction did not occur. All production of records will be tied to document identifiers.
Original corporate and transaction records recovered
1932 funeral-service transaction: The Pink Neely estate file includes an itemized Smith & Gaston invoice dated June 2, 1932, totaling $159 (casket $85, box $10, embalming $20, hearse $10, two cars $14), plus a sworn account statement attributed to A. G. Gaston. View invoice and view sworn statement. Jefferson County Probate Court, FamilySearch image group 007824432.
1933 burial-society collection record: A James Harris estate file preserves a Booker T. Washington Burial Society certificate/payment card (certificate no. 4090), naming Smith & Gaston Undertaking Co., President A. G. Gaston, and weekly dues of 25 cents, with handwritten collection entries. View front and view reverse. Jefferson County Probate Court, FamilySearch image group 007738062.
1935 state financial returns — company-row attribution under re-audit: Alabama Superintendent of Insurance report, Table XI and Part IX (p. 152). Read digitized original.
Alabama Insurance Reports — 1931 and 1933
1931 regulatory transition: the state report records Booker T. Washington Burial Society, Fairfield, as reinsured in Booker T. Washington Burial Insurance Co., Fairfield, on December 31, 1931.
1931 annual-statement figures: $5,000 capital stock; $32,485.16 total income; $32,586.94 disbursements; $9,511.46 admitted assets; $4,406 liabilities excluding capital stock.
1933 annual-statement figures: $5,000 capital stock; $29,022.47 total income; $26,976.52 disbursements; $19,002.73 admitted assets; $5,554.49 liabilities excluding capital; $8,448.24 surplus.
Publication note: the 1933 report states that the 1932 annual report was not separately published and that the department combined the 1932 and 1933 reporting years.
1931 Alabama Insurance Report · 1933 Alabama Insurance Report
Evidence limit: these regulatory tables identify the company but do not name Gaston personally; they are used here to establish the company's financial and regulatory record.
1954 motel property transfer and financing — original instruments pending
Original motel design and construction (historical-source attribution): National Park Service historic-preservation documentation identifies architect Stanley B. Echols and general contractor Steel City Construction Company. Surviving architectural sheets reportedly include February 1954 dates. A published National Trust historical account reports approximately $300,000 personally financed by Gaston; this is a secondary-source claim, not a verified original construction account. The original agreement, contractor payments, drawings, building permit and source-of-funds records remain outstanding.
December 1954 building and operations expansion (secondary-source documentation): National Park Service preservation research describes the addition of a restaurant building east of the original motel coffee shop. Original construction permit, valuation, contractor invoices, inspection and occupancy records for the initial motel and separate restaurant addition have not been examined. Do not infer a verified dollar construction cost from the reported $300,000 financing claim or from the reported $64,637.72 land transfer.
March 29, 1954: National Park Service historical documentation reports that Booker T. Washington Insurance Company transferred four Birmingham parcels (Lots 17–20, Block 43) to A. G. Gaston Motels, Inc. The reported consideration of $64,637.72 is attributed to later historical research, not yet checked against the signed deed. This is a reported property transaction amount, not a verified motel construction cost or a measure of Gaston's personal investment.
Earlier deed leads: Jefferson County Deed Book 3436, p. 545 (Lot 18, 1943); Deed Book 3637, p. 176 (Lot 19, 1945); Deed Book 4985, p. 501 (Lot 20, March 1953). Original recorded copies remain outstanding. The 1954 deed book and page are still unknown.
Financing hypothesis: a published historical account states that Gaston personally underwrote construction in 1953. The company's incorporation, stock subscription, ownership, capital sources, construction contract, payment trail and relationship to the insurer must be established from original records before characterizing the financing structure.
Archival action, October 20, 2026: targeted requests sent to Jefferson County and the Alabama Department of Archives and History for original deed, charter, related corporate records and early financial statements; responses pending.
HISTORY WITH RECEIPTS™
Claims remain subject to individual source review. Additional archival material will be added as evidence is recovered.
ARCHIVAL CERTIFICATION & PUBLIC RECORD INTEGRITY
All company records presented in this repository have been cataloged according to the BEHI Company Records Classification System. Documents marked as Primary Sources are drawn from certified state and county archives, corporate filings, and recognized institutional repositories. Where physical scans are currently in the acquisition pipeline, verified archival metadata, source citations, and holding locators are provided to facilitate scholarly research.
| Document & ID | Evidence Type | Date | Description & Location | Source Repository | Action |
|---|---|---|---|---|---|
|
Gaston — 1925 burial-society state registration
BEHI-P015-S15
Arthur George (A. G.) Gaston
|
Primary Archival
Formation & Governance
|
July 16, 1925 |
State registry reproduction examined. Incorporators: Creola A. Gaston, Bessie Smith and Ella Fulton; dissolved January 26, 1932. A. G. Ga...
|
Alabama Secretary of State, entity 000-808-981
|
|
|
Gaston — 1928 burial-society state registration
BEHI-P015-S16
Arthur George (A. G.) Gaston
|
Primary Archival
Formation & Governance
|
December 4, 1928 |
State registry reproduction examined. Incorporators: A. G. Gaston, Creola Gaston, A. L. Smith and Bessie Smith. Authorized capital $20,00...
|
Alabama Secretary of State, entity 000-808-983
|
|
|
Gaston — 1931 insurance-company state registration
BEHI-P015-S17
Arthur George (A. G.) Gaston
|
Primary Archival
Formation & Governance
|
December 22, 1931 |
State registry reproduction examined. Incorporators: A. G. Gaston, Creola Gaston and Abe L. Smith. Database capital figures are not neces...
|
Alabama Secretary of State, entity 000-019-662
|
|
|
Gaston — 1926 Alabama insurance report
BEHI-P015-S18
Arthur George (A. G.) Gaston
|
Primary Archival
Financial
|
Year ending December 31, 1926 |
Source scan inspected, as documented in the Profile. Identifies Booker T. Washington Burial Society of Fairfield, president A. G. Gaston,...
|
Alabama Superintendent of Insurance, Annual Report for 1926, printed p. 414; PDF p. 415
|
|
|
Gaston — 1931 Alabama insurance report
BEHI-P015-S19
Arthur George (A. G.) Gaston
|
Primary Archival
Financial
|
1931 |
Profile records a December 31, 1931 reinsurance transition and company statement: capital $5,000; income $32,485.16; disbursements $32,58...
|
Alabama Superintendent of Insurance, 1931 annual report
|
|
|
Gaston — 1933 Alabama insurance report
BEHI-P015-S20
Arthur George (A. G.) Gaston
|
Primary Archival
Financial
|
1933 |
Profile records capital $5,000; income $29,022.47; disbursements $26,976.52; admitted assets $19,002.73; liabilities excluding capital $5...
|
Alabama Superintendent of Insurance, 1933 annual report
|
|
|
Gaston — 1936 Alabama insurance report
BEHI-P015-S21
Arthur George (A. G.) Gaston
|
Primary Archival
Financial
|
1936 |
Original source reproduction inspected, as documented in Receipts. Coverage comparison and burial-insurer financial summary support the P...
|
Alabama Superintendent of Insurance, 1936 report, printed pp. 146 and 176; PDF pp. 151 and 181
|
|
|
Gaston — 1932 Smith & Gaston invoice and sworn statement
BEHI-P015-S22
Arthur George (A. G.) Gaston
|
Primary Archival
Contracts & Transactions
|
June 2, 1932 |
Existing Profile documents an itemized funeral-service invoice totaling $159 and a sworn account statement attributed to A. G. Gaston. An...
|
Jefferson County Probate Court, Pink Neely estate; FamilySearch image group 007824432
|
|
|
Gaston — 1933 burial-society collection card
BEHI-P015-S23
Arthur George (A. G.) Gaston
|
Primary Archival
Ledgers & Accounts
|
1933 |
Existing Profile documents a certificate/payment card naming Smith & Gaston Undertaking Co., president A. G. Gaston, weekly dues of 2...
|
Jefferson County Probate Court, James Harris estate; FamilySearch image group 007738062; certificate 4090
|
|
|
Gaston — 1946 NAACP advertising correspondence
BEHI-P015-S07
Arthur George (A. G.) Gaston
|
Primary Archival
Contracts & Transactions
|
1946 |
Inspected correspondence, advertising statements, payment acknowledgments and envelopes concern Smith & Gaston, Booker T. Washington ...
|
Library of Congress, NAACP Records, Box II:F4, supplied PDF pp. 1–4
|
|
|
Gaston — Citizens Federal charter and conversion history — SEC filing
BEHI-P015-S11
Arthur George (A. G.) Gaston
|
Primary Archival
Formation & Governance
|
May 30, 2002 |
Issuer release reports September 1956 federal charter, March 28, 1983 mutual-to-stock conversion with 130,000 shares, October 10, 1983 ba...
|
Citizens Bancshares Corporation, SEC Exhibit 99.2
|
|
|
Gaston — Citizens Federal acquisition — 2004 Form 10-K
BEHI-P015-S12
Arthur George (A. G.) Gaston
|
Primary Archival
Contracts & Transactions
|
2004 filing; acquisition February 28, 2003 |
Company filing documents completion of the CFS Bancshares acquisition and Citizens Federal merger into Citizens Trust Bank. Approximately...
|
Citizens Bancshares Corporation, 2004 Form 10-K, Note 2 — Acquisition
|
|
|
Gaston — 2004 insurance-company examination report
BEHI-P015-S01
Arthur George (A. G.) Gaston
|
Primary Archival
Legal & Regulatory
|
December 31, 2004 examination date |
Existing Profile cites the regulator report for corporate history, finances and recordkeeping. This later examination does not replace or...
|
Alabama Department of Insurance, Booker T. Washington Insurance Company examination report
|
|
|
Gaston — 1966 business-college letters and curricula
BEHI-P015-S05
Arthur George (A. G.) Gaston
|
Primary Archival
Reports & Correspondence
|
1966 |
Existing Profile cites published college curricula, recruitment material and letters. These document stated offerings and correspondence;...
|
U.S. congressional hearing volume CHRG-89shrg69451O
|
|
|
Gaston — 1972 business-college accreditation listing
BEHI-P015-S06
Arthur George (A. G.) Gaston
|
Primary Archival
Operational
|
1972 |
Existing Profile identifies the college in an accreditation listing. A listing does not establish corporate formation date, enrollment to...
|
Accreditation listing cited in Profile; ERIC ED087354
|
No verified records are currently published in this category.
Receipts
TAKEAWAY: Gaston’s evidence distinguishes inspected institutional records from pending requests and private leads. Research correspondence and record requests are not proof of the underlying financial claims.
RECEIPTS & EVIDENCE
HOW TO READ THE EVIDENCE
Follow the claim to its source, then read the evidence status and limits. A source may support one narrow fact while leaving a larger conclusion unresolved.
Content condition describes whether the question can currently be answered. Evidence classification describes the support for a documented finding.
- Documented: A finding is presented with its source, evidence classification and limits. Documented does not automatically mean Verified.
- Not yet established: The answer remains unresolved. The entry identifies missing evidence and connects to Research Gaps.
- Not applicable: The measure does not fit the person or enterprise being examined; an explanation must state why. Missing evidence alone never makes a question not applicable.
Shared section headings remain visible. Relevance that is uncertain is treated as Not yet established until resolved.
Evidence labels and source access
- Verified
- The specific fact or record described has been checked against the cited material. Read the limit: an inspected reproduction, index or catalog entry does not mean every underlying document or broader claim has been verified.
- Attributed
- The statement is credited to the named source. Independent confirmation or the underlying original may still be outstanding.
- Disputed
- Sources or interpretations conflict. Read the competing evidence and the unresolved question.
- Estimated
- The figure is an approximation or qualified valuation, not an exact measured total. Read its basis, date and uncertainty.
- Institute Analysis
- BEHI’s interpretation or calculation from identified evidence. It is separate from what the historical source directly states.
Source access: A link may lead to an original scan, a published transcription, a finding aid, or a repository page. Use the source ID, collection, box, folder and page locator where supplied. A catalog listing or repository confirmation is not inspection of the item itself.
Images and permissions: Historical support and reproduction permission are separate questions. Read each image credit and rights note; a source link does not itself grant permission to republish.
Open questions: See Research Gaps & Open Questions below for missing records and unresolved claims.
Every receipt is classified by whether it is an inspected published record, a contemporary statement reporting a claim, or an archival locator that still requires retrieval. Research assignments remain open; the public should not confuse a pending inquiry with a completed source review.
DOCUMENTS
ESOP filings — partial packages
Booker T. Washington Insurance Co., Inc., EIN 63-0220465, plan 002. DOL/EBSA FOIA 2027-F-00524 release, November 3, 2026. Public-inspection filings; plan-reported figures. Missing: 1992 audit/notes and investment detail; 2009 H and R. Extracts and limits.
1992 Form 5500 (6 pages)
1992 Schedule C (3 pages)
2009 Form 5500 (2 pages)
Motel property transaction entry — March 29, 1954
Content condition: Documented. Evidence classification: Verified — limited to the inspected archival record reproduction.
The entry records “BOOKER T WASHINGTON INS CO TO A G GASTON MOTELS INC,” dated March 29, 1954, with a listed amount of $64,637.72. The property line identifies lots 17, 18, 19 and 20, block 43, Elyton Land Co. A book/page-style reference reads “5164–368”; confirm its function against the underlying recorded instrument.
Citation: Birmingham, Alabama, Birmingham Public Library Archives, Jefferson County Board of Equalization Records. Reproduction supplied by David B. Schneider, Schneider Historic Preservation, LLC; inspected by BEHI November 3, 2026. Exact box, folder and item locator requested.
Evidence limits: This transaction entry corroborates the named corporate parties, date and listed amount. It is not the signed deed or proof of payment, personal ownership, actual construction cost, or the source of financing.
Image access and rights: Reproduction received for research. Public image display and download arrangements are awaiting clarification; the image is not published here.
Read the record — burial society and insurance reports
These scanned regulator reports document company activity and finances; they do not establish A. G. Gaston’s personal net worth or, by themselves, legal continuity among similarly named entities.
Booker T. Washington Burial Society statement, 1926
Readable text — Selected financial extract
Use the Booker T. Washington Burial Society section in the lower part of page 414; the section above concerns another insurer. The report names A. G. Gaston as president and Creola Gaston as secretary.
| Entry | Recorded value |
|---|---|
| Income | $11,597.66 |
| Disbursements | $12,103.24 |
| Admitted assets | $1,345.17 |
| Liabilities excluding capital | $531.64 |
| Surplus | $813.53 |
Selected printed totals only; labels shortened. These are society accounts, not Gaston’s personal assets. Checked against the source images by BEHI, October 28, 2026.
Preview: Supplied document image; see citation for coverage.
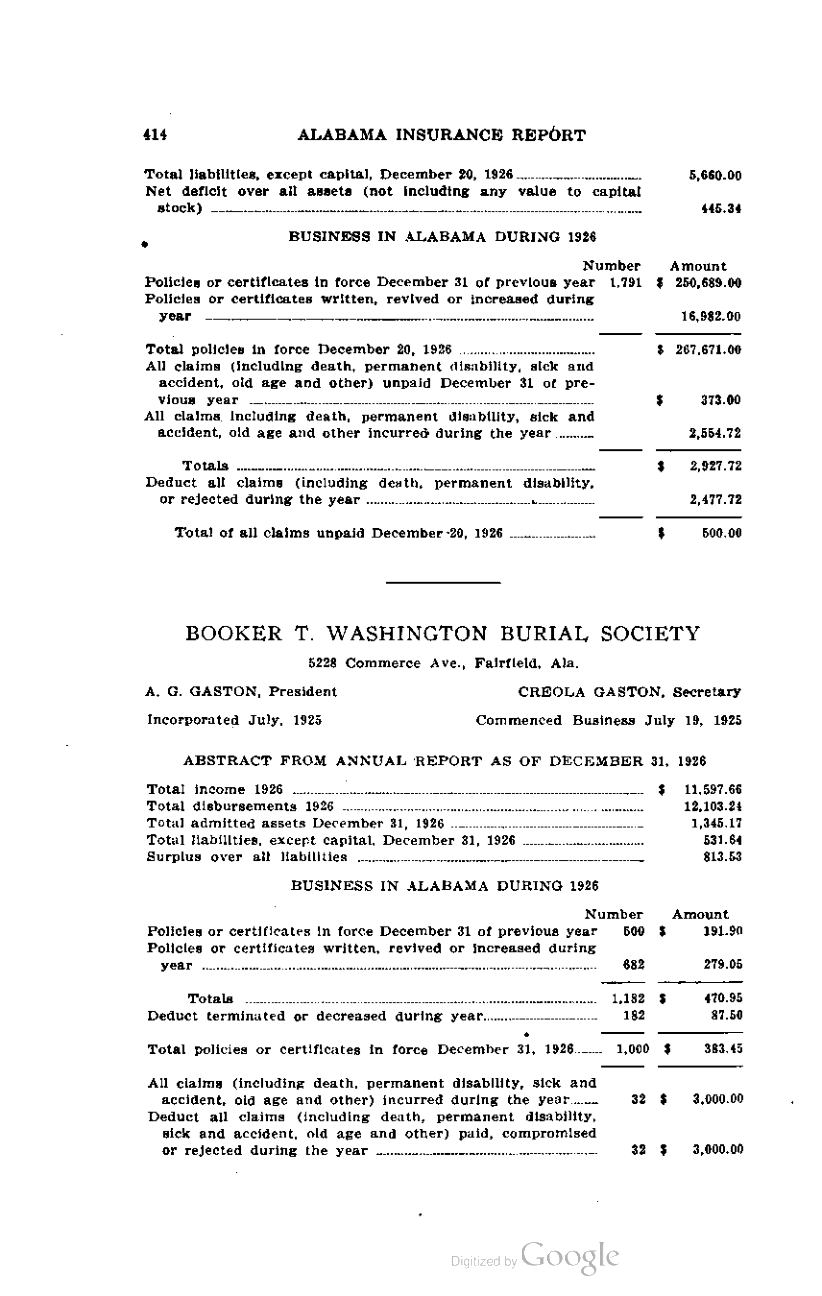
Full file: Open full-size file
Evidence classification: Inspected primary regulatory statement; company-reported figures, not an independent audit or personal earnings.
Rights note: Historical Alabama government publication; retain publication and repository credit.
Booker T. Washington Burial Insurance Company tables, 1936
Readable text — Selected financial extract
On both displayed pages, use the Booker T. Washington Burial Insurance Company row, rather than adjacent companies. Page 146 records Alabama business; page 176 gives financial totals.
| Entry | Recorded value |
|---|---|
| Premiums received, Alabama business (p. 146) | $54,757.92 |
| Capital stock (p. 176) | $6,000.00 |
| Income (p. 176) | $57,363.60 |
| Disbursements (p. 176) | $49,807.34 |
| Total admitted assets (p. 176) | $52,313.54 |
| Liabilities excluding capital (p. 176) | $28,755.52 |
| Surplus (p. 176) | $17,558.02 |
Selected entries only; company abbreviations expanded and labels shortened. Premiums for Alabama business and total income have different scopes. These figures do not measure personal wealth. Checked against the source images by BEHI, October 28, 2026.
Preview: 2 selected page images; see citation for coverage.
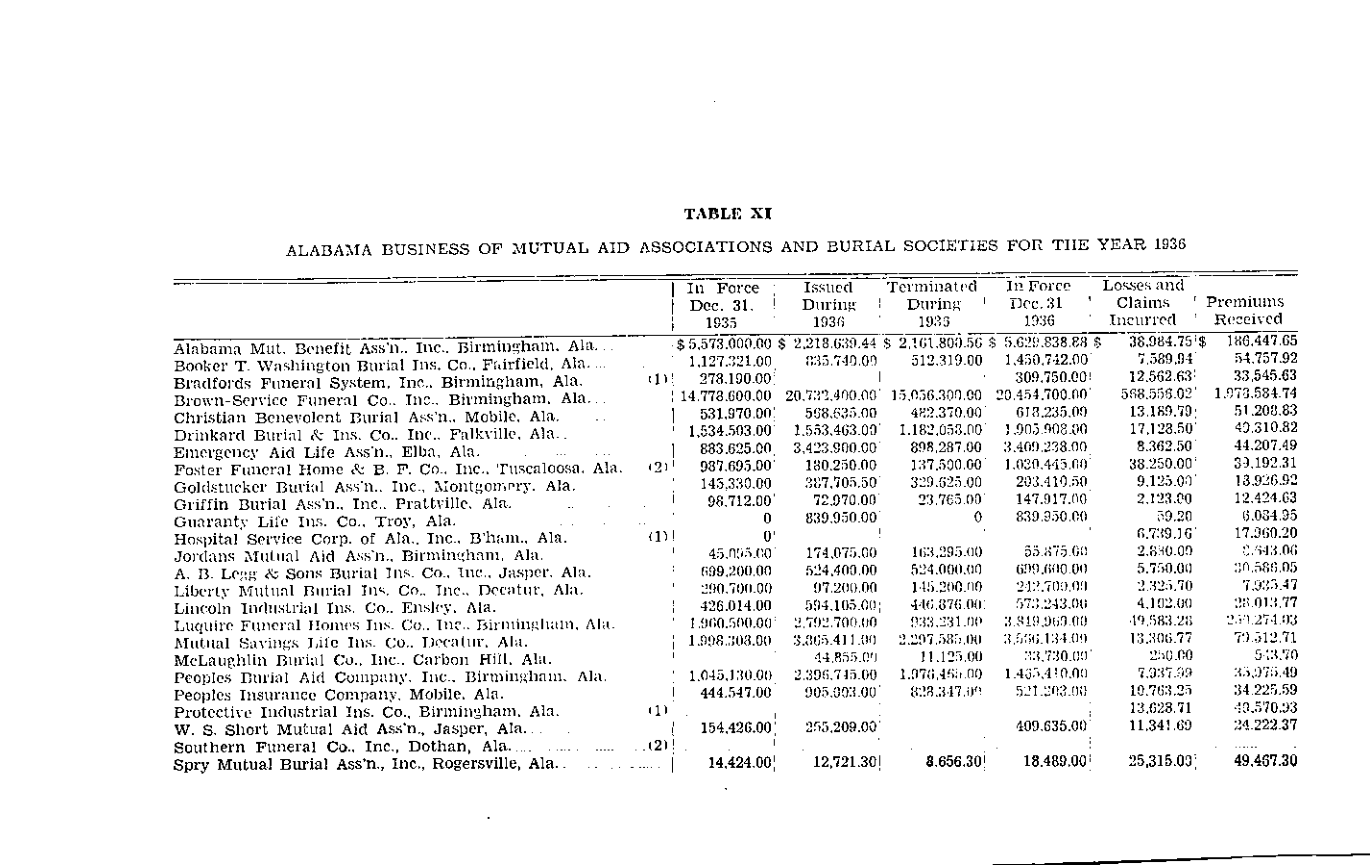
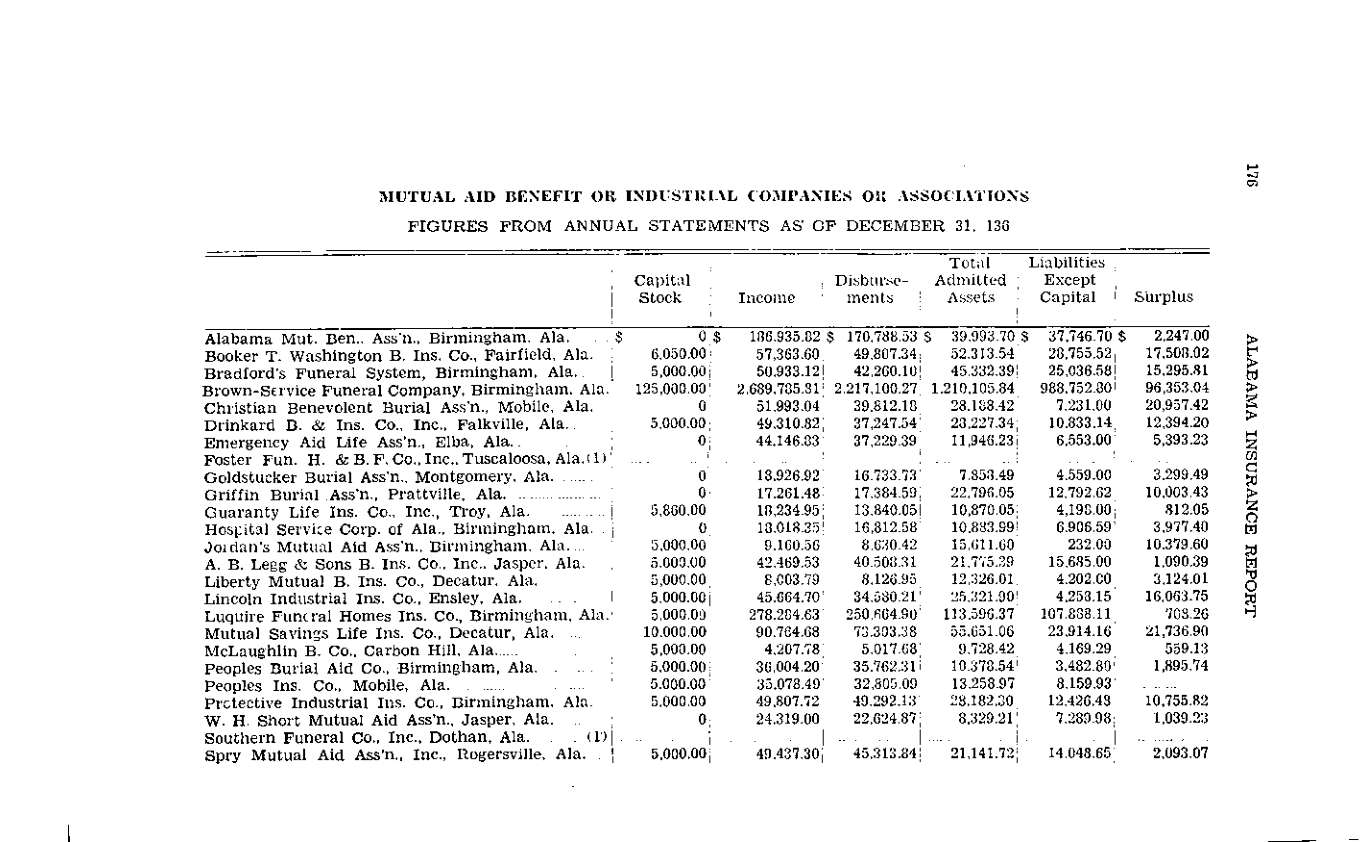
Full file: Open full-size page 1 · Open full-size page 2
Evidence classification: Inspected primary regulatory tables; read the correct company row; not personal wealth or proof of legal succession.
Rights note: Historical Alabama government publication; repository access and reuse notices remain applicable.
The 1936 pages are rotated for readability, with full page content retained. These are source scans, not reconstructed documents. The existing correction notes concerning the disputed 1935 tables remain applicable.
State-incorporation records and 1936 regulator report — inspected original source reproductions
Registry screenshots, October 14, 2026: Alabama Secretary of State company entries 000-808-981 (1925 nonprofit; Creola A. Gaston, Bessie Smith, Ella Fulton); 000-808-983 (1928 corporation; A. G. Gaston, Creola Gaston, A. L. Smith, Bessie Smith); and 000-019-662 (1931 insurance corporation, with a 1946 change of name). The state summaries have been examined; signed charters and succession filings are not yet inspected.
1936 report: Alabama Superintendent of Insurance annual report, HathiTrust digital volume hvd.hl2d7u, printed p. 146 (digital PDF p. 151, insurance-coverage comparison) and printed p. 176 (digital PDF p. 181, burial insurer financial summary). The report supports the 1936 values published in Economic Impact and a comparative 1935 year-end insurance in force of $1,127,321. The report for 1925 was previously supplied under a mistaken 1929 filename; no 1929 report is inferred from that copy.
Correction log: The earlier 1935 summary in the Economic Impact tab mistakenly associated the $278,190 coverage figure and linked summary with Gaston's company. Those claims have been withdrawn pending reconciliation. The existing 1935 research scans remain preserved, but should be reviewed at row level before use as receipts.
Record custody: PDFs and official registry screen reproductions received from Gerry Waters, October 2026. They are reference copies, not certified original incorporation instruments. Status: PRIMARY GOVERNMENT SOURCE INSPECTED / LEGAL ENTITY SUCCESSION NOT YET ESTABLISHED.
Original insurance regulatory receipt — Gaston's Booker T. Washington Burial Society (1926)
Source: Alabama Superintendent of Insurance, Annual Report for the Year Ending December 31, 1926 (published 1927), printed p. 414, uploaded digital copy PDF p. 415 of 457, section Industrial, Assessment and Mutual Aid Companies and Associations of This State. BEHI examined this original government-published financial abstract in the digital scan provided by research correspondent Gerry Waters, October 14, 2026. The report is cataloged in the Alabama Department of Archives and History, State Publications Database; the public catalog identifies the publication, not this specific PDF reproduction.
Directly documented: The entry names Booker T. Washington Burial Society, 5228 Commerce Avenue, Fairfield, Alabama; A. G. Gaston, president; Creola Gaston, secretary; incorporated July 1925; and commenced business July 19, 1925. For calendar 1926 it reports income of $11,597.66, disbursements of $12,103.24, admitted assets of $1,345.17, liabilities excluding capital of $531.64, surplus of $813.53, and 1,000 certificates in force at December 31.
Entity identity control: The next printed page, p. 415 (PDF p. 416), identifies Booker T. Washington Life Insurance Company, incorporated in 1921, under president B. L. Windham and secretary J. W. Gillispie. Its figures are not attributed to Gaston. The relationship between the 1925 Burial Society and the later 1931-incorporated burial-insurance enterprise still requires examination of original articles, amendments, transfer records and regulators' files.
Evidence limits: These are company-reported amounts reproduced in a government annual report; they are not independent audit conclusions, proof of every disbursement, Gaston's personal earnings, or final evidence of corporate succession. The supplied file labeled Alabama_Insurance_Report 12_31_1929.pdf is actually the state's report for the year ending December 31, 1925, as shown on its title page; the true 1929 report remains outstanding. Status: PRIMARY REGULATORY SOURCE INSPECTED — ENTITY CONTINUITY UNDER INVESTIGATION. The inspected page image, full-file link and citation are available in the 1926 document card.
Original 1946 business correspondence and advertising records — Library of Congress
Source: NAACP Records, Manuscript Division, Library of Congress, Box II:F4; four-page scan supplied by reference librarian Loretta Deaver, October 2026. The scanned folder material includes January 1946 Smith & Gaston stationery and Booker T. Washington Business College correspondence (PDF pp. 1–2), statements concerning advertising in The Crisis (p. 2), payment acknowledgments/receipts (p. 3), and envelopes bearing Smith & Gaston's contemporary stationery and building illustration (p. 4).
Documented narrow finding: These contemporary records connect business correspondence involving Smith & Gaston and Booker T. Washington Business College with advertising activity in the NAACP's The Crisis. Several entries show $4.90 amounts; invoices and acknowledgments must be reconciled before calculating total spending or asserting distinct payments. The records do not establish corporate ownership, the school's incorporation, or total advertising expenditures.
Preservation and rights: Original PDF retained in BEHI's nonpublic research archive; scanned pages are not reproduced on this public Profile pending permissions review. Classification: PRIMARY SOURCE INSPECTED — TRANSACTION INTERPRETATION LIMITED TO DOCUMENTED ENTRIES.
New receipts — original records (1932–1935)
- 1932 Smith & Gaston funeral invoice — Pink Neely estate. June 2, 1932; itemized funeral charges totaling $159. Open original image. Jefferson County Probate Court, FamilySearch image group 007824432, image 1119 of 1633.
- 1932 sworn account — A. G. Gaston. Gaston attests that the firm's account concerns Pink Neely's burial. Open original image. Same image group, image 1123 of 1633.
- 1933 Booker T. Washington Burial Society dues card — James Harris estate. Certificate 4090; weekly dues of 25 cents; handwritten collection entries. Card front and card reverse. Jefferson County Probate Court, image group 007738062, images 1620–1621 of 1638.
- 1935 Alabama insurance regulatory annual report. These state tables are preserved as research material. The earlier attribution of selected rows to Booker T. Washington Burial Insurance Co. was withdrawn; no financial values should be taken from these displayed pages until the company rows are reconciled. Open HathiTrust scan. Alabama Superintendent of Insurance, Annual Report for Year Ending December 31, 1935, Table XI and Part IX, p. 152.
Research status: These original sources support the specifically cited claims; the entire profile remains Research in Progress. The complete regulatory annual-report series and further probate records are under investigation. FamilySearch may require a free account to view its images.
View the original documents — 1932–1935
Digitized reproductions of primary-source records provided to BEHI by research correspondent Gerry Waters. Select an image to view it at full resolution; use the archival-source link for context and provenance.
Pink Neely funeral invoice, 1932
Readable text — Selected itemized transcription
| Entry | Recorded value |
|---|---|
| Casket | $85.00 |
| Box | $10.00 |
| Embalming | $20.00 |
| Hearse | $10.00 |
| Cars (2) | $14.00 |
| Total | $159.00 |
Itemized charges transcribed from the displayed invoice; currency formatting normalized. Letterhead and marginal handwriting omitted. The invoice records charges, not proof that the bill was paid. Checked against the source images by BEHI, October 28, 2026.
Preview: Supplied document image; see citation for coverage.
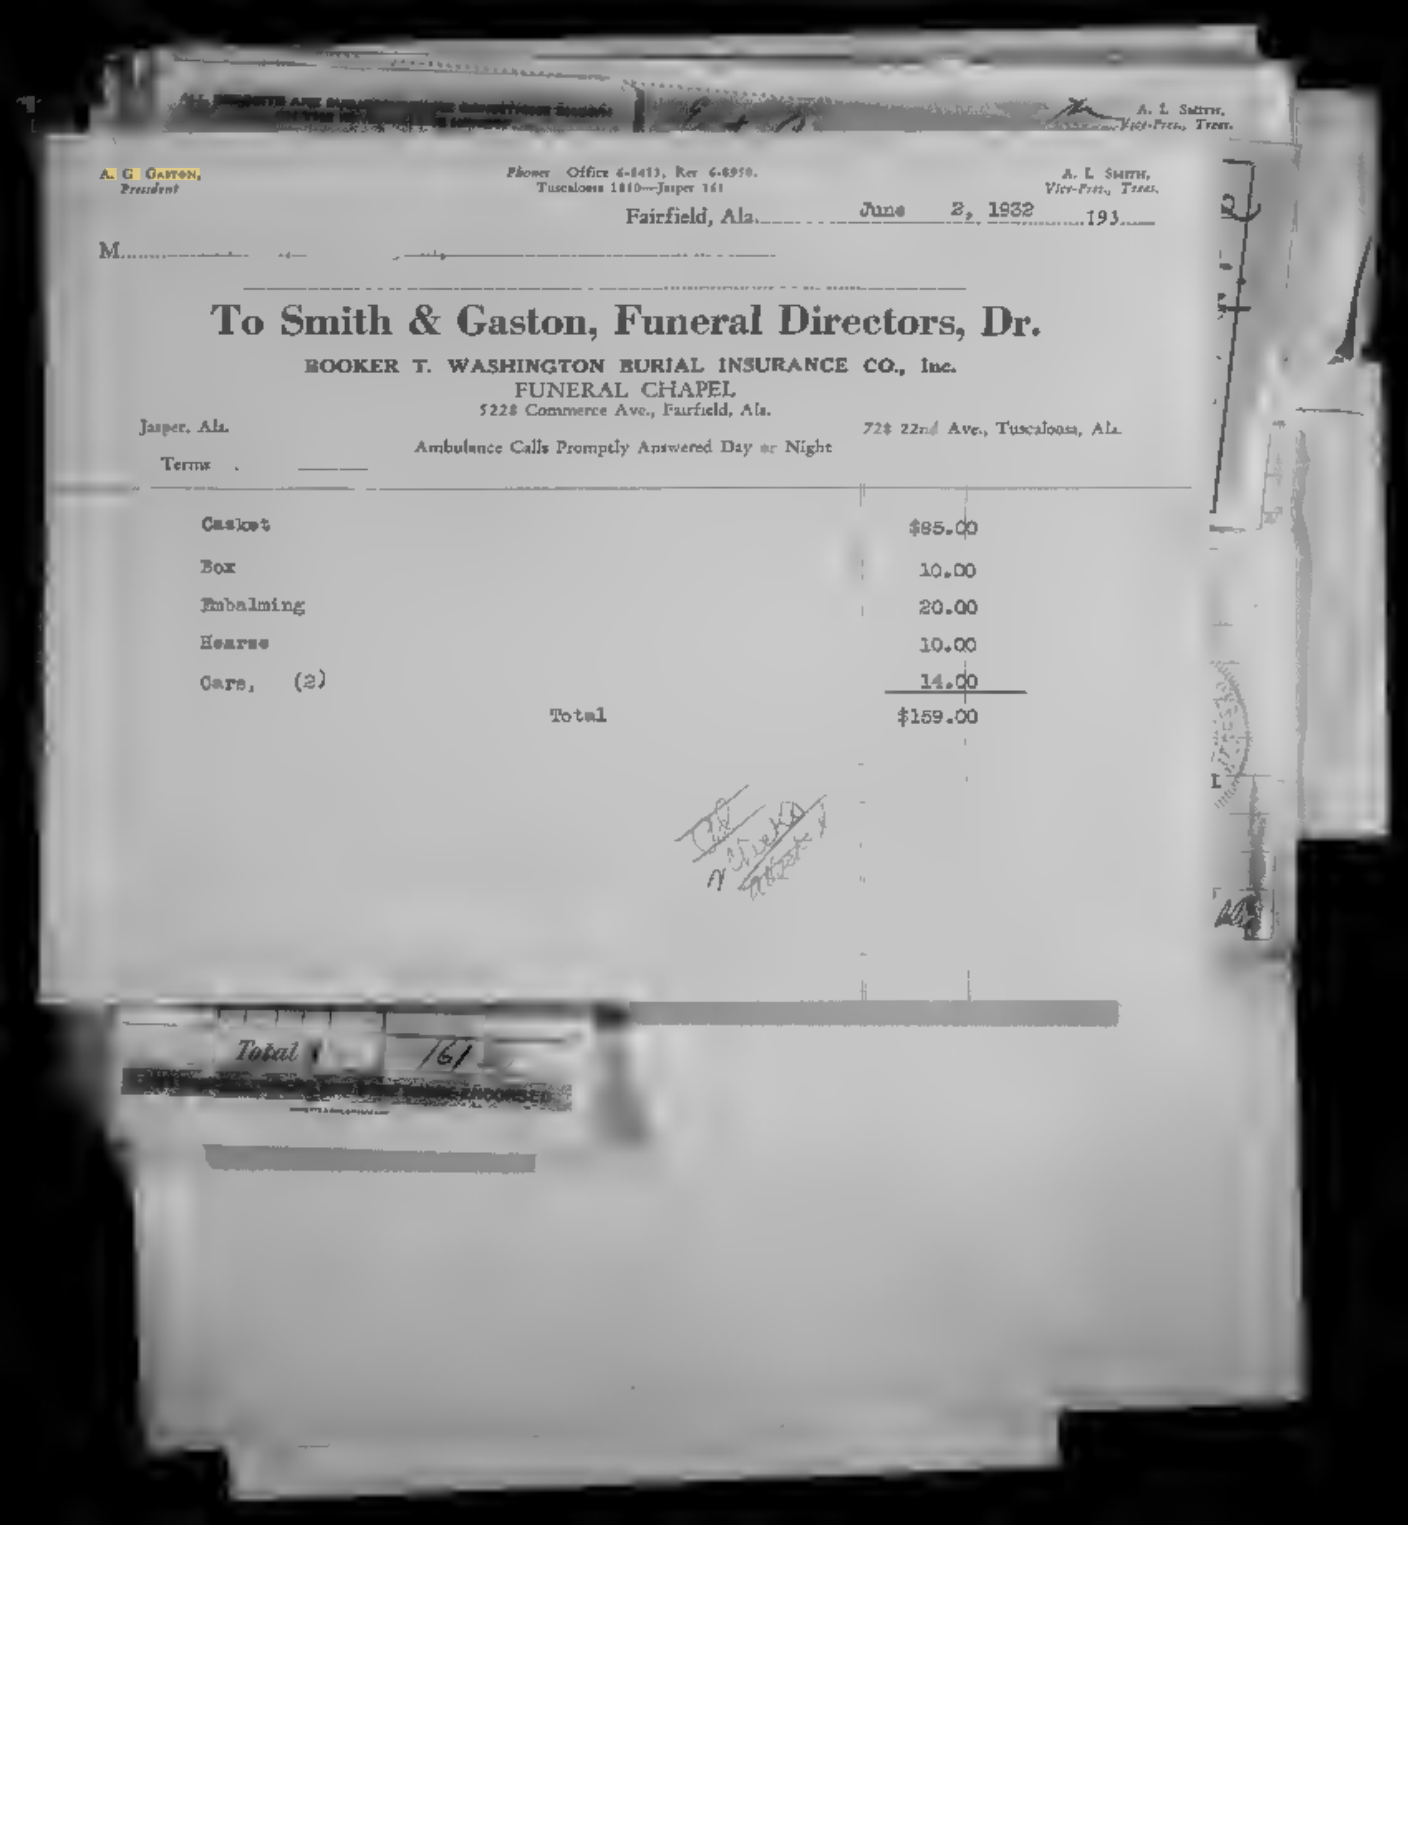
Full file: Open full-size file
Evidence classification: Primary itemized account; billed charges do not alone establish payment.
Rights note: Existing court-record research reproduction supplied to BEHI. FamilySearch access and reuse terms apply; no blanket third-party republication permission is asserted.
Pink Neely sworn funeral account, 1932
Readable text — Readable summary
In the lower portion, A. G. Gaston attests that the Smith & Gaston account concerns the burial of Pink Neely, deceased, and that the account is true and correct to his personal knowledge. The attestation is sworn in June 1932.
A separate Ensley National Bank receipt is attached over the upper portion. Its $3 amount must not be treated as proof of payment of the $159 funeral invoice.
BEHI summary of the lower attestation and identification of the attached receipt. Handwritten day, signatures and partly covered wording are not fully transcribed; uncertain readings are not supplied. Checked against the source images by BEHI, October 28, 2026.
Preview: Supplied document image; see citation for coverage.
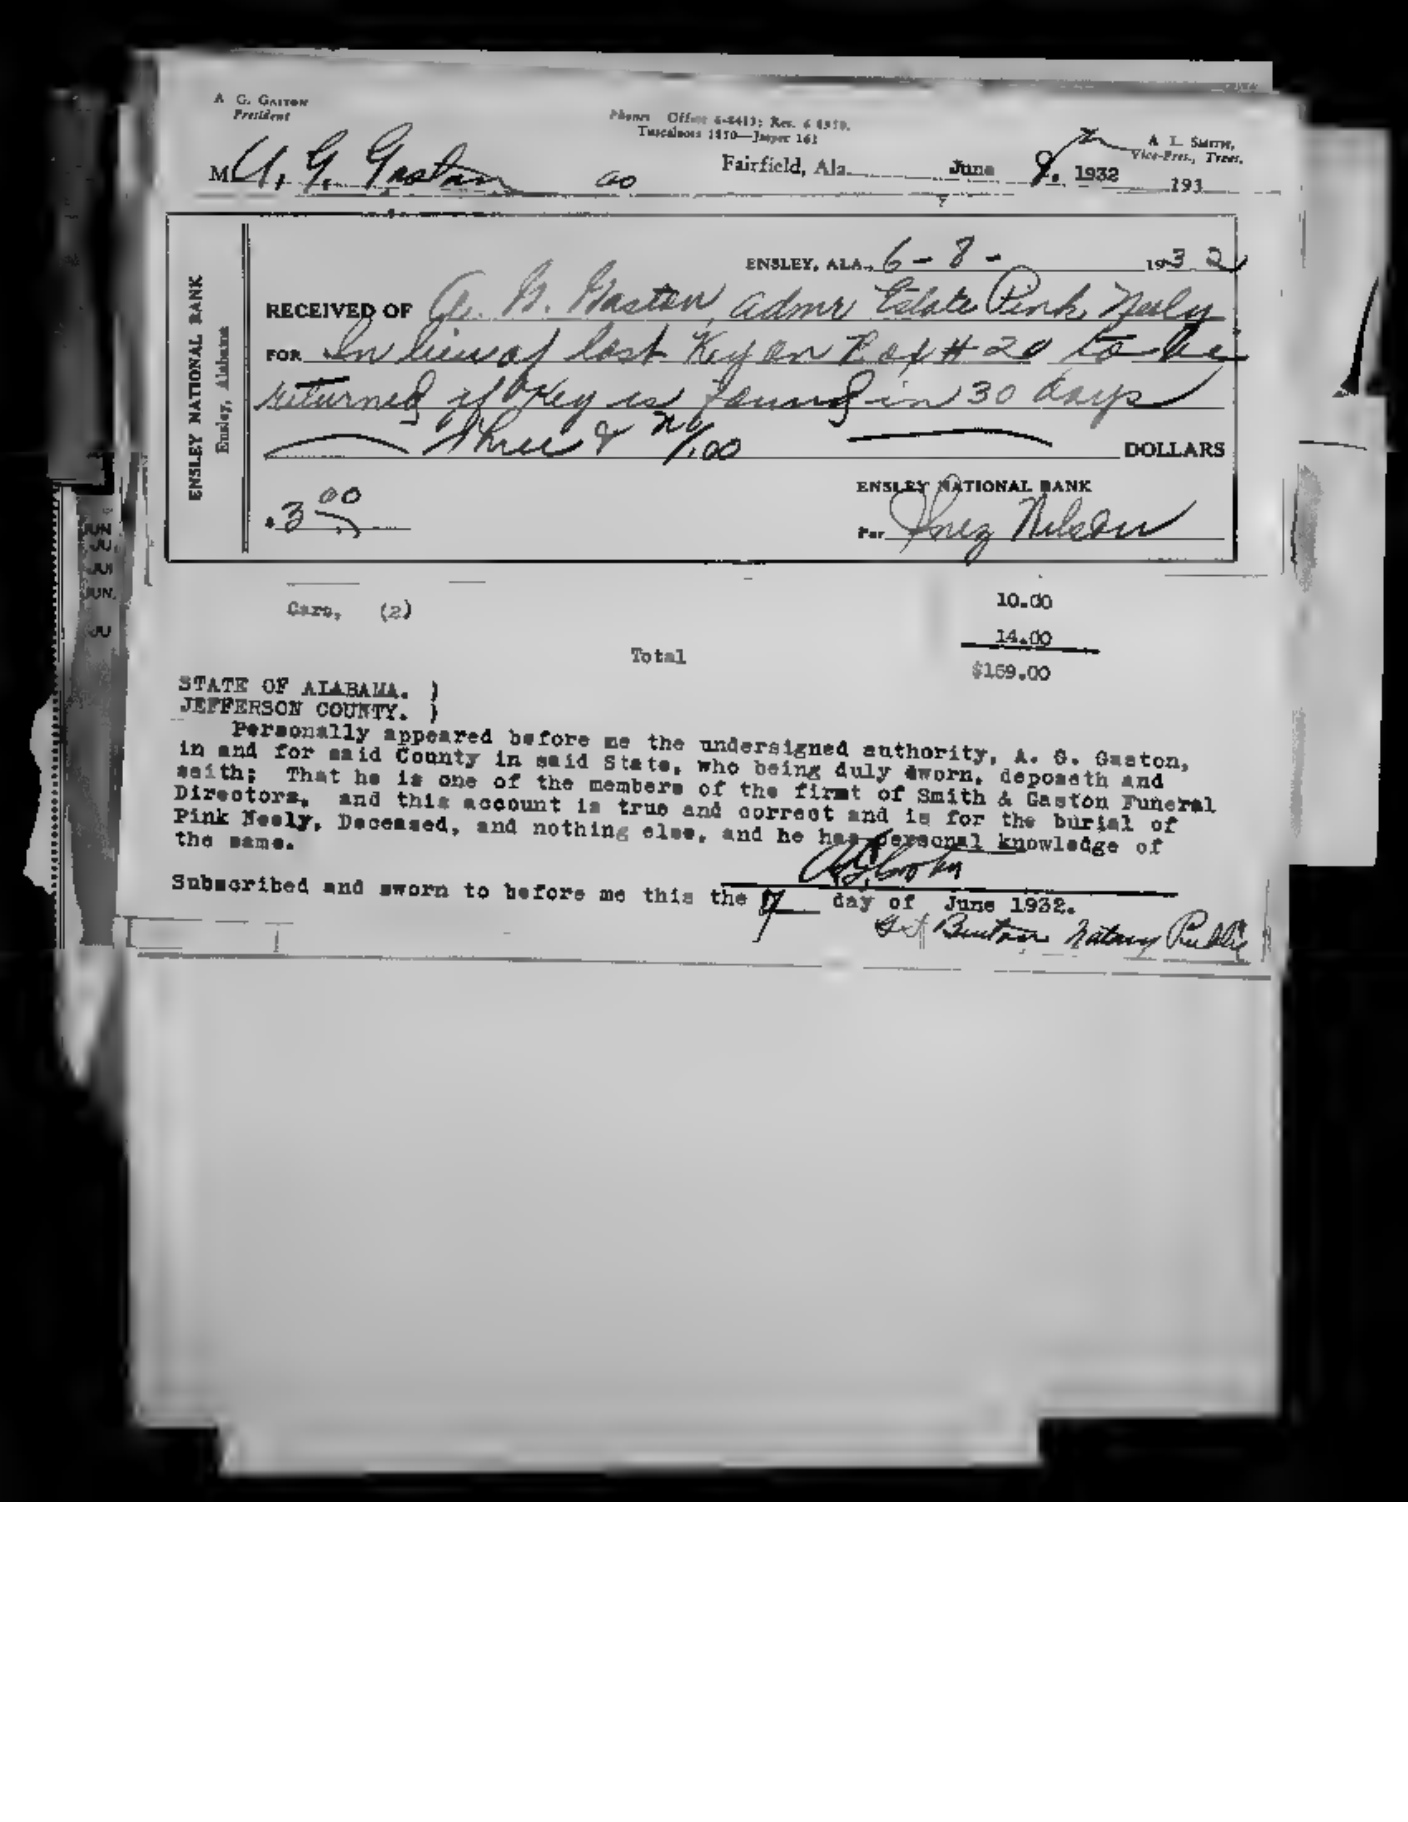
Full file: Open full-size file
Evidence classification: Primary sworn account; distinguishes an attestation from proof of payment.
Rights note: Existing court-record research reproduction supplied to BEHI. FamilySearch access and reuse terms apply; no blanket third-party republication permission is asserted.
James Harris burial-society dues card, 1933
Readable text — Selected fields and reading guide
| Entry | Recorded value |
|---|---|
| Society | Booker T. Washington Burial Society |
| Undertaking company | Smith & Gaston Undertaking Co. |
| President | A. G. Gaston |
| Head of family | James Harris |
| Address | Warrior, Ala. |
| Certificate number | 4090 |
The front payment columns are blank. The reverse has handwritten payment entries from July through December, with “25” entered repeatedly in the amount column. Printed instructions warn that a certificate falls out of benefit after three weeks of nonpayment.
Selected fields transcribed and ledger summarized. Partly obscured instructions, collector signatures and individual payment dates are not fully transcribed. Do not infer a complete year of payments or total revenue from this card. Checked against the source images by BEHI, October 28, 2026.
Preview: 2 selected page images; see citation for coverage.
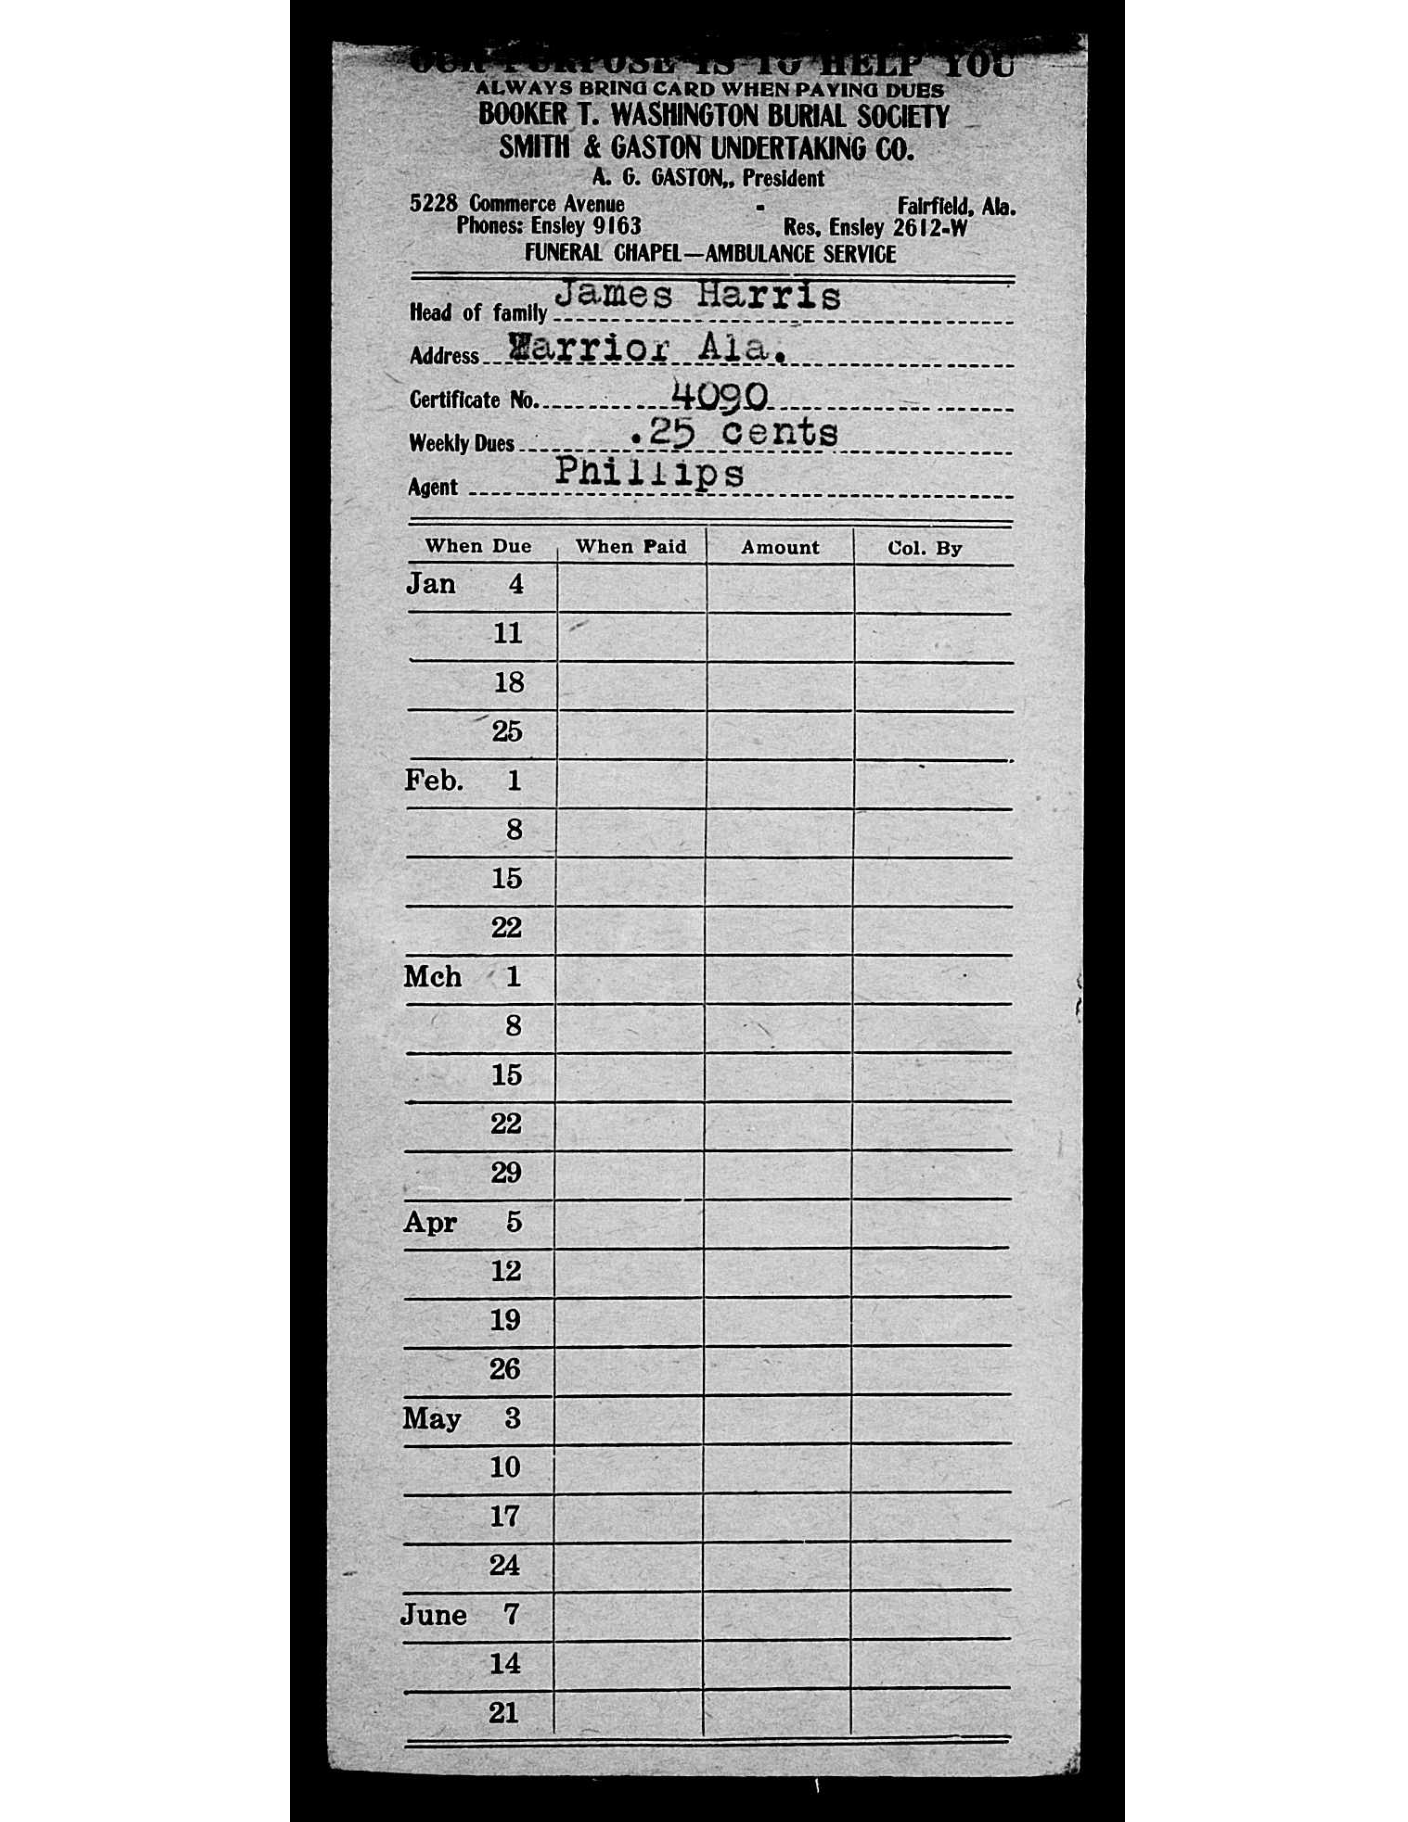
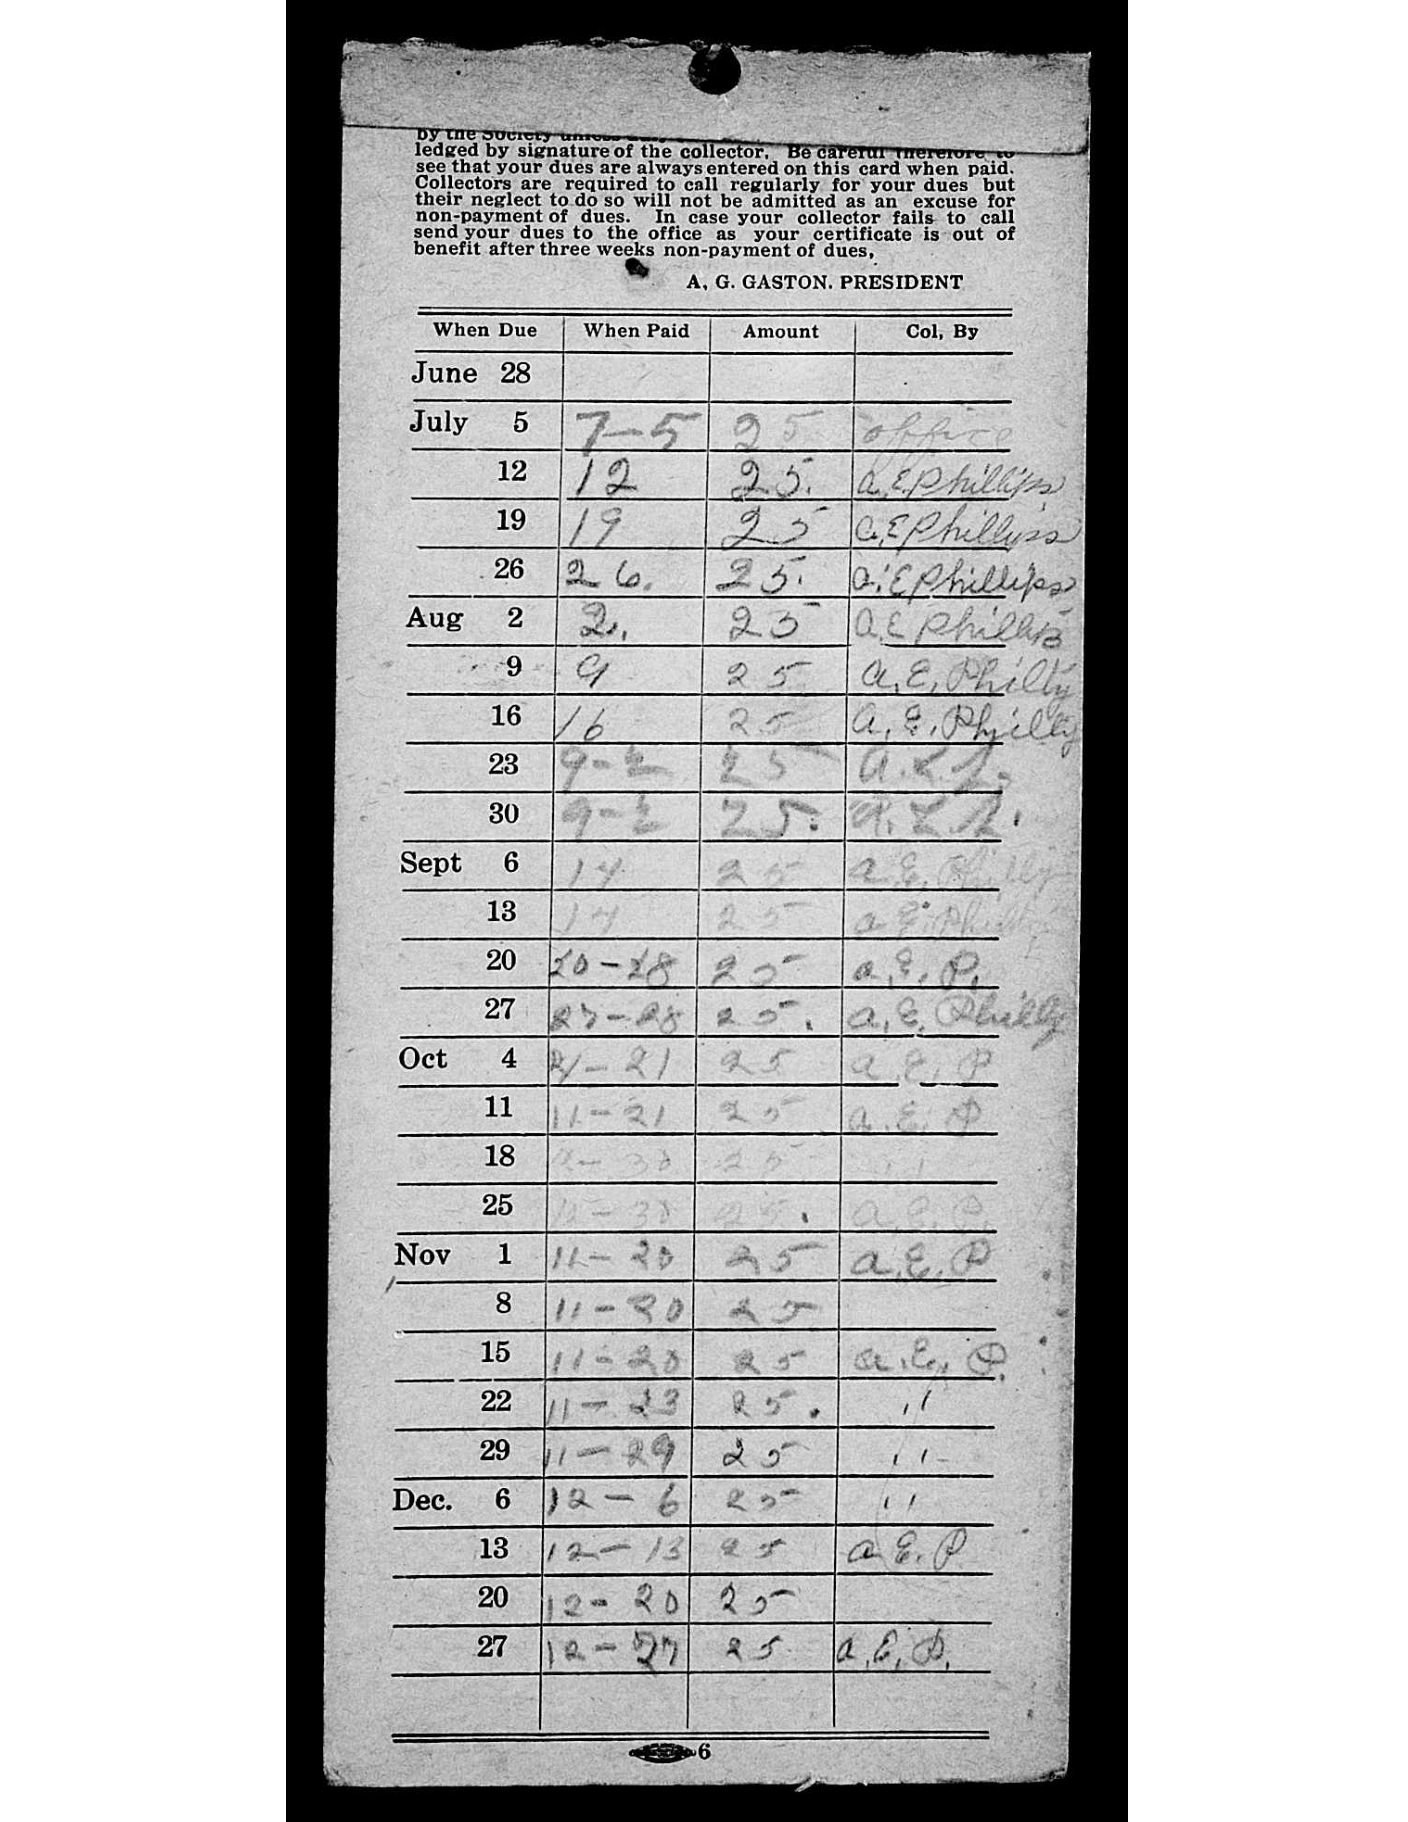
Full file: Open full-size page 1 · Open full-size page 2
Evidence classification: Primary membership and collection record; not proof of company-wide revenue or ownership.
Rights note: Existing court-record research reproduction supplied to BEHI. FamilySearch access and reuse terms apply; no blanket third-party republication permission is asserted.
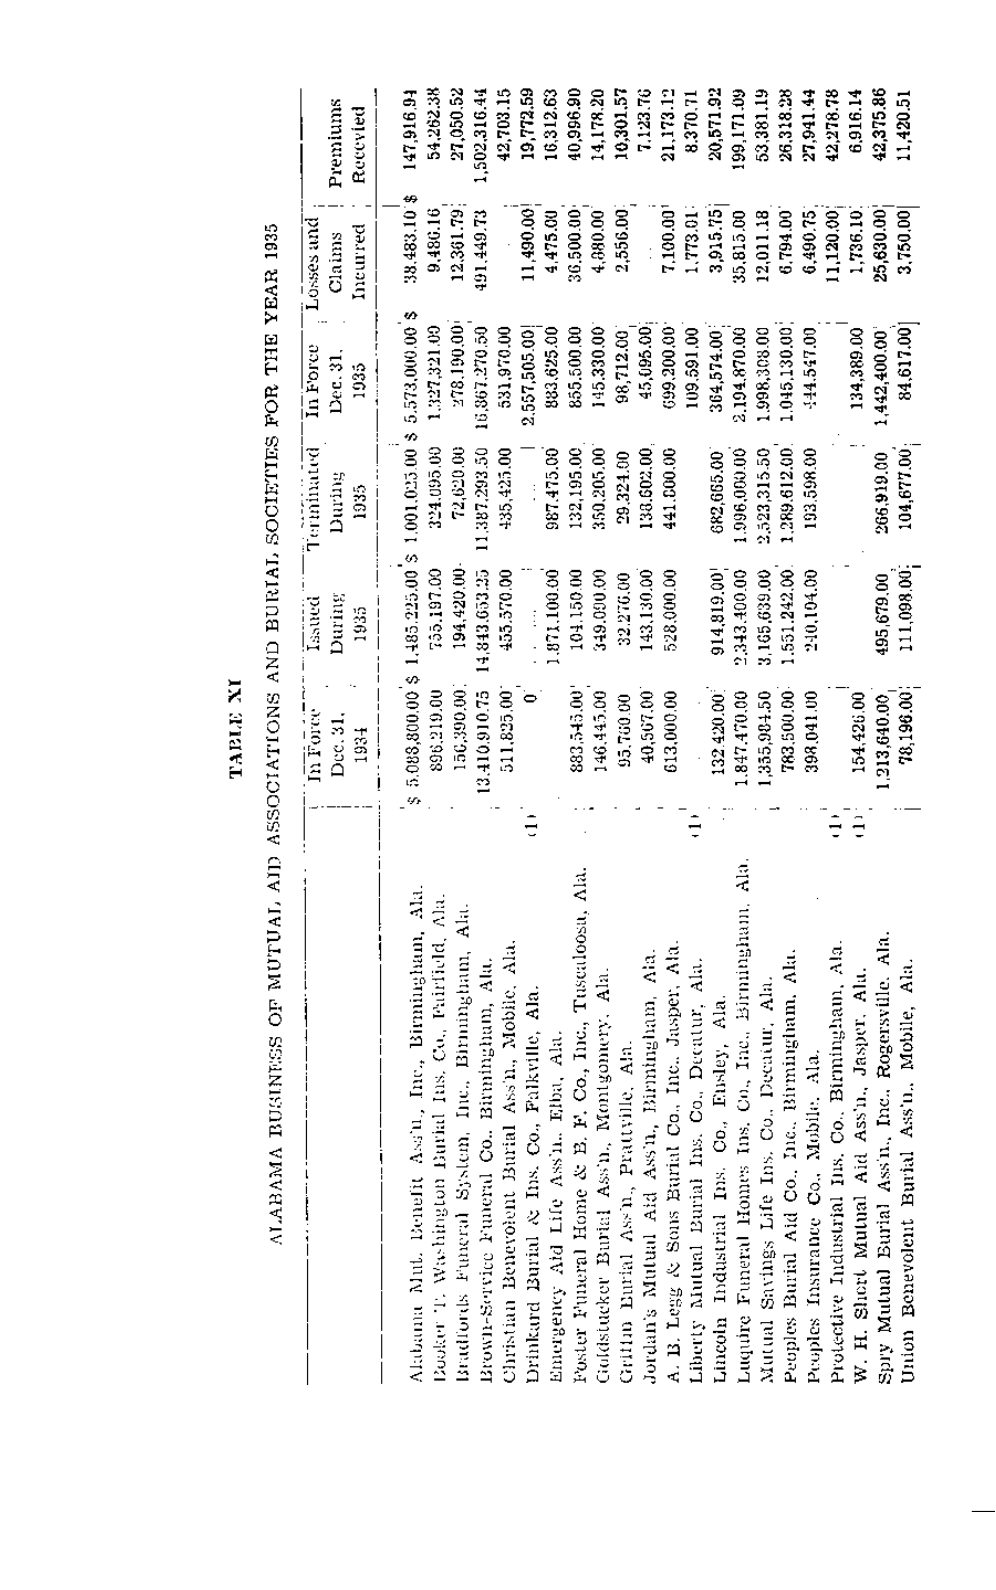
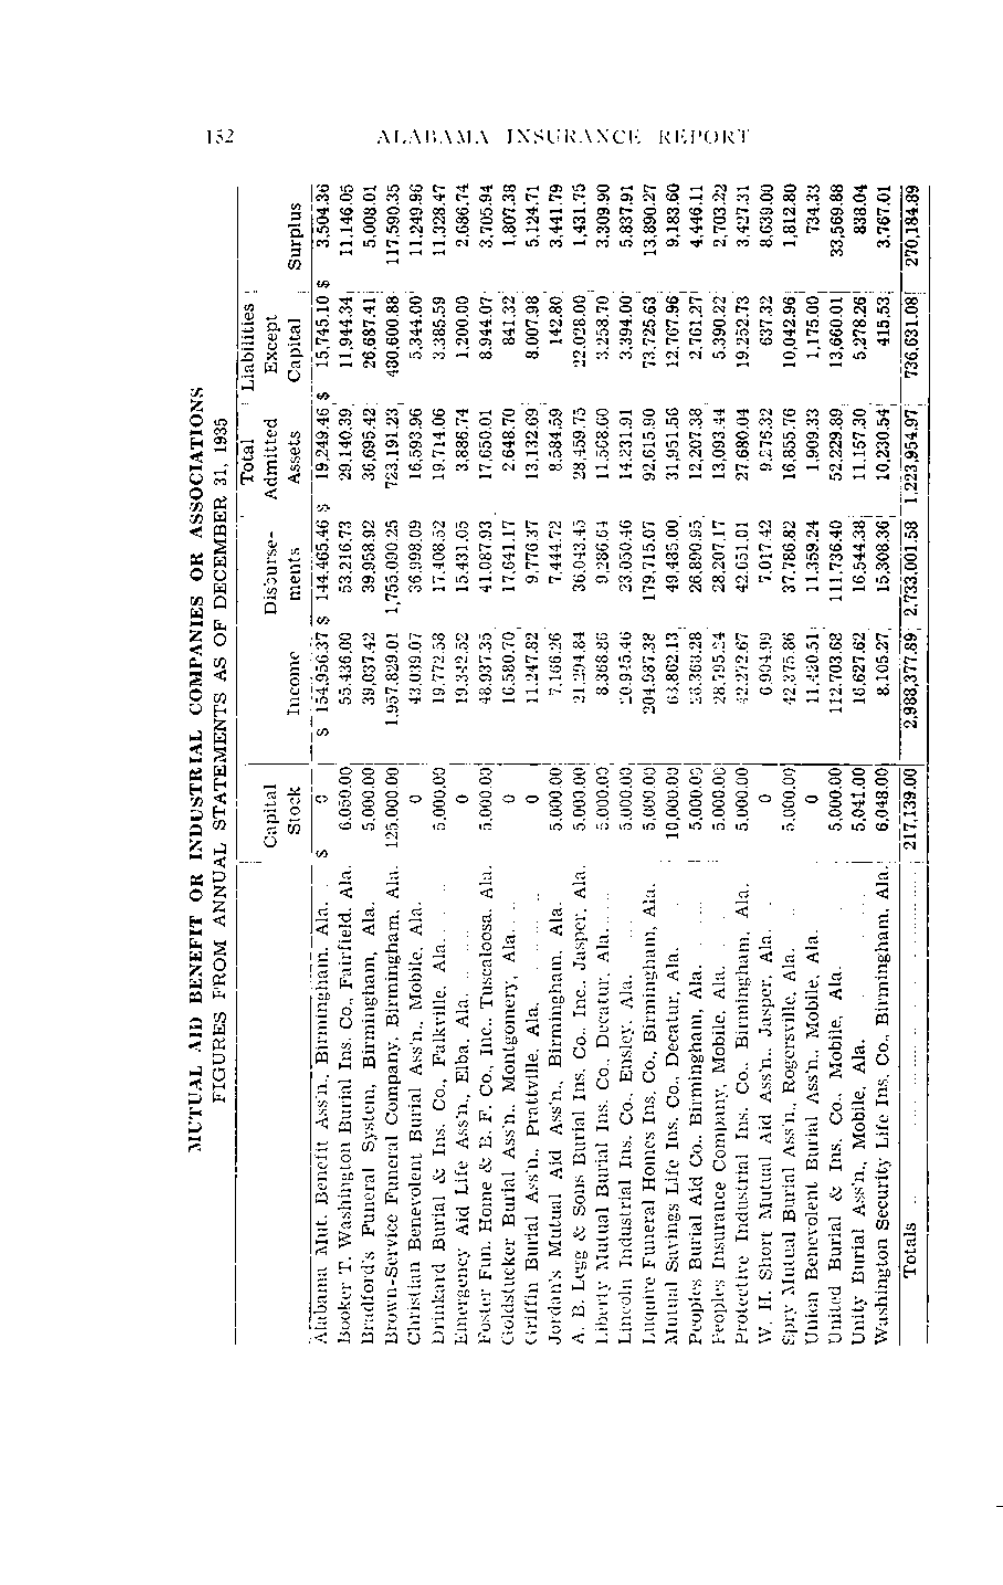
Sources: Jefferson County, Alabama Probate Court estate files, FamilySearch image groups 007824432 and 007738062; Alabama Superintendent of Insurance, Annual Report for Year Ending December 31, 1935, Table XI and Part IX. The public document reproductions are evidence for individual claims; BEHI Profile №15 remains Research in Progress.
Receipt — Alabama insurance regulatory record, 1931–1933
Source: Reports of the Superintendent of Insurance of the State of Alabama.
- 1931: records the Booker T. Washington Burial Society → Booker T. Washington Burial Insurance Co. reinsurance transition and reports company financial figures from the annual statement.
- 1933: reports the company's capital, income, disbursements, admitted assets, liabilities and surplus; the volume also explains that no separate 1932 annual report was published.
Open 1931 digitized original · Open 1933 digitized original
BEHI classification: contemporaneous government regulatory evidence. These tables support claims about the enterprise; they do not, by themselves, prove Gaston's personal ownership percentage, compensation, or net worth.
SOURCE REGISTER & EVIDENCE LIMITS
Primary-source and archival register
| Receipt | Record and source | Classification | Scope / limitation |
|---|---|---|---|
| BEHI-P015-S01 | 2004 insurer examination report Alabama Department of Insurance | VERIFIED | Primary regulatory record; distinguishes original incorporation and later financial conditions. |
| BEHI-P015-S02 | A. G. Gaston Motel historical research National Park Service | VERIFIED | Historic site chronology and corporate development; inspect original citations for deed figures. |
| BEHI-P015-S03 | Smith & Gaston Funeral Directors v. Wilson, 79 So.2d 48 (1955) Alabama Supreme Court | VERIFIED | Published opinion states Grace Hill Cemetery acquired in 1948. |
| BEHI-P015-S04 | Smith & Gaston Funeral Directors v. Dean, 80 So.2d 227 (1955) Alabama Supreme Court | VERIFIED | Published legal opinion on cemetery operations. |
| BEHI-P015-S05 | Manpower Development and Training Act Amendments of 1966 U.S. Senate | VERIFIED | Minnie Gaston letters and employer demand, printed pp.40–41. |
| BEHI-P015-S06 | Specialized Accreditation and Preaccreditation (1972) U.S. Office of Education | VERIFIED | Federal accreditation listing; not initial accreditation certificate. |
| BEHI-P015-S07 | NAACP Records, Crisis File 1940–1955 Library of Congress | VERIFIED | Correspondence scans have since been inspected and are held privately pending rights review. This link identifies the collection, not the delivered scans. Invoices and acknowledgments must be matched before totaling payments. |
| BEHI-P015-S08 | National Vocational Student Loan Insurance Act of 1965 hearings U.S. House | VERIFIED | Digitized hearing volume; exact testimony pages pending. |
| BEHI-P015-S09 | Higher Education Act of 1965 hearings, Part III U.S. Senate | VERIFIED | Prepared statement identified near printed p.1076; complete examination pending. |
| BEHI-P015-S10 | 1949–1952 college catalog listing Booker T. Washington Business College | ATTRIBUTED | Original catalog offered for sale; not inspected by BEHI. |
Evidence standard: VERIFIED means the cited record substantiates the limited statement shown. A record that reports a person's claim does not independently verify that claim's underlying quantity.
Citizens Federal — documentary receipts and provenance
BEHI-P015-S11 — PRIMARY SEC-FILED COMPANY STATEMENT: Citizens Federal / CFS Bancshares acquisition announcement, May 30, 2002 (Exhibit 99.2). Identifies September 1956 federal charter, March 28 and October 10, 1983 conversions, June 30, 1998 holding-company structure and announced 2002 acquisition. Classification: SEC-FILED CORPORATE STATEMENT; underlying original charters not yet inspected.
BEHI-P015-S12 — PRIMARY SEC-FILED CORPORATE REPORT: Citizens Bancshares Corporation, 2004 Form 10-K, Note 2. Documents February 28, 2003 acquisition closing, bank merger and stated acquisition costs of approximately $9.055 million. Classification: SEC-FILED CORPORATE REPORT; acquisition consideration is not Gaston's personal wealth.
BEHI-P015-S13 — SECONDARY LOCAL HISTORY LEAD: Bhamwiki, “Citizens Federal Savings Bank”, one-page reference copy forwarded by historical correspondent Gerry Waters, October 2026. Mentions Arthur Shores and John Drew, initial capitalization, 1967 reported assets, membership/shareholder count and dividends. Classification: SECONDARY SOURCE — independent underlying documentation still required. In particular, the claim of 13,000 “shareholders” by 1967 conflicts with the SEC description of a mutual institution until 1983; do not present it as verified stock ownership.
Banking predecessor — new secondary-source receipt
BEHI-P015-S14 — SECONDARY INTERPRETIVE SOURCE: Karen D. Brame, “A. G. Gaston,” BLACKListed Culture, particularly article p. 6 (PDF copy received October 2026 through Gerry Waters). The article attributes to historian David T. Beito the description of Citizens Federal as Birmingham's first Black-owned financial institution since Alabama Penny Savings Bank closed. This is evidence of a published historical interpretation, not an original bank record or proof of an exact ordinal ranking.
Related institutional context: Encyclopedia of Alabama history of Penny Savings Bank; City of Birmingham account of historic Black Main Street. The City's account of Gaston's eventual purchase of the former bank building remains unverified at deed level.
Preservation and publication boundary: Gerry's 16-page PDF should be retained intact in BEHI's internal reference archive with provenance; do not upload the full copyrighted article or embedded images to the public Profile without permission. Cite and link the original publication instead.
SOURCE PROVENANCE AND RESEARCH GAPS
Alabama insurance annual reports, probate-file invoices and card images can support precise financial and operational claims.
Filed bank statements and annual reports support defined milestones but are not Gaston's original ownership ledgers.
BLACKListed Culture, Bhamwiki, Encyclopedia of Alabama and Birmingham municipal history provide leads requiring corroboration.
EVIDENCE & CONTEXT
| Evidence class | Examples already cited | How it is used |
|---|---|---|
| Primary inspected | 1926 / 1931 / 1933 / 1936 insurance records; probate exhibits | Claim-level evidence with year, entity and scope |
| Primary reported by issuer | 2002 SEC statement; 2004 buyer Form 10-K | Reported corporate milestones and valuation context |
| Secondary interpretation | BLACKListed Culture, Bhamwiki and municipal histories | Cited historical context, not original title-chain proof |
| Outstanding archival evidence | 1965 House hearing pp. 104–107; original ESOP transfer instruments and federal charter | Remain visibly marked as research gaps |
Do not republish Gerry Waters' complete third-party PDF on the public Profile without authorization. Link the original article while preserving its provenance in the private research archive.
RESEARCH GAPS & OPEN QUESTIONS
ECONOMIC INDICATORS — MISSING EVIDENCE
Verified employment placements
Content condition: Not yet established. Booker T. Washington Business College
Reporting period not established
Evidence needed / present limit: Reported employer requests and graduates do not establish hires, placement rates or wage outcomes.
Penny Savings Bank historical property chain: Search Birmingham/Jefferson County deeds and tax or building records for the former Eighteenth Street bank headquarters, identify the transfer to A. G. Gaston and every intervening owner, and record the parties, date, consideration, legal description and financing. Review contemporary Penny Savings/Prudential Savings closure and merger reports. Do not treat a municipal historical statement as an examined deed.
- Booker T. Washington Insurance: original 1931 formation record, early annual reports and detailed 1987 ESOP transaction and Form 5500 filings.
- Smith & Gaston: original 1937–1940 deed and mortgage; claimed Brown-Service financing; early corporation records.
- Grace Hill Cemetery: original 1947–1949 acquisition deed, sellers, mortgage and consideration.
- Booker T. Washington Business College: original 1966 corporation articles, 1949–1952 catalog, accreditation and school-license files, full 1965 testimony, 1946 NAACP correspondence, graduate placement totals.
- Citizens Federal: original federal charter, financial reports and 1983 conversion records.
- A. G. Gaston Motel: 1954 acquisition chain, building records, historic appraisal sheets and construction financing.
- WENN/WENN-FM: complete FCC BAL-8439 and BALH-2151 applications, ownership exhibits and purchase agreement.
- Ownership and wealth: original estate inventory, stock registers and entity-level consolidated records.
Historical property transaction — source recovered November 3, 2026
David B. Schneider supplied the Jefferson County Board of Equalization transaction entry referenced on page 9 of his report. Read the inspected entry, citation and evidence limits. The signed conveyance, complete title chain and financing records remain acquisition targets.
1954 motel construction and appraisal evidence — verification pending
Contemporary photographic lead: National Park Service historic documentation identifies photographs dated December 27, 1954, attributed to Jefferson County Board of Equalization appraisal records; investigate Birmingham Public Library Archives Collection AR270 (1939–1977) for the exact original photographs, corresponding property card, valuation, ownership details, and image permission. Archival originals have not been obtained or cleared for publication.
Original permits not recovered: Locate Birmingham 1953–1954 original motel permit, declared estimated construction valuation, inspection reports and certificate of occupancy; separately seek December 1954 restaurant-addition permit, valuation and inspection file. Declared permit values and assessed values must not be treated as proof of actual construction cost.
Research workflow: Existing inquiries to Jefferson County, Alabama Department of Archives and History and Birmingham's A. G. Gaston Motel Preservation Team are pending. Do not duplicate these requests; allow responses to determine the next targeted acquisition.
Research gaps — motel conveyance and initial corporate financing (October 20, 2026)
Updated November 3, 2026: An inspected Jefferson County Board of Equalization transaction entry corroborates the March 29, 1954 corporate transfer and listed $64,637.72 amount. See the recovered transaction evidence. The signed deed, proof of payment and claim of personal construction financing remain unverified against original conveyances, accounting records or payment documents.
- Original March 29, 1954 conveyance: grantor/grantee index entries, recording date, deed book and page, signatures and legal description
- Earlier deed copies: Book 3436 p. 545; Book 3637 p. 176; Book 4985 p. 501
- Original A. G. Gaston Motels, Inc. incorporation certificate, incorporators, initial capital stock and subscriptions
- Insurer board authorization, related mortgage or loan instruments, and any intercompany financial arrangements
- 1953–1954 Steel City Construction Company contracts, invoices and payment records; Stanley B. Echols architectural documentation
- 1954–1955 balance sheets, income statements, capitalization, general ledger and operating records
Requests sent October 20, 2026: Jefferson County records inquiry and Alabama Department of Archives and History corporate-records inquiry. Both awaiting replies; do not duplicate these requests.
Evidence classification: historical report / research lead. No signed 1954 deed or original early motel financial statements acquired as of this update.
RESEARCH UPDATES & RECONCILIATION
Evidence status: Private-material authentication and reproduction permissions remain pending. ESOP filings have been received and reviewed; original transfer instruments and missing attachments remain outstanding.
Read full note: Private collections, banking, ESOP, and local archival leads
Private collection lead — October 24, 2026: Collector Jimmie L. Robinson supplied photographs showing Citizens Federal Savings & Loan Association staff-meeting minutes dated March 26, 1974; a Booker T. Washington Insurance Company advertisement announcing an Ordinary Insurance Department; a Gaston/Thacker Joint Venture Construction Company brochure; and additional business and commemorative materials. BEHI has requested complete scans, provenance information, and clarification about possible early Smith & Gaston formation papers. Authentication and reproduction permissions remain pending.
Citizens Federal source-recovery leads (October 2026): Research correspondent Gerry Waters offered to seek an introduction to John Drew, described as a former bank official and a collaborator on Barbara Shores' book. He also suggested contacting successor Citizens Trust Bank about historical files retained from the acquisition and checking the Alabama state banking regulator. Status: Introductions, record holdings and responses pending; any oral recollections require documentary corroboration. Recover the September 1956 federal charter and opening records, the complete March/October 1983 conversions and share-register evidence, institution-level annual reports, the 1998 holding-company filings and the definitive 2002–2003 merger agreement and appendices. Explore federal thrift regulator records because original charter was federal. Keep possible sponsorship separate from record access.
ESOP FOIA 2027-F-00524 — records released: EBSA’s November 3, 2026 response supplied 1992 and 2009 filings plus 1992 Schedule C. See source coverage and missing attachments. Completeness follow-up sent.
Birmingham Historical Society research leads (October 2026): Researcher and trustee Gerry Waters reports that Smith & Gaston Funeral Home may retain original daybooks and identifies current owner Paul Gardner as a prospective contact; Waters also identifies Arthur Shores's daughter Barbara as a potential guide to Shores family papers. He reports that historical Jefferson County incorporation filings, deed records and deed indexes require on-site archive research, and points to potentially relevant Birmingham Public Library unpublished holdings, unscanned African American newspapers, and Alabama insurance regulatory records. BEHI has requested introductions and guidance. Status: research leads only; holdings, contents, access, and their relevance to specific transactions remain unverified.
1965 congressional employer-placement evidence — original pages requested
Evidence status: The hearing is identified, but its original pages and named-employer entries have not been inspected. Reported placements are not individually verified.
Read full note: 1965 congressional employer-placement source request
Source identified: U.S. House of Representatives, Committee on Education and Labor, Select Subcommittee on Education, National Vocational Student Loan Insurance Act of 1965, hearing on H.R. 6468, 89th Congress, 1st Session, April 5–7, 1965, pp. 104–107 (SuDoc Y 4.Ed 8/1:N 21 v).
A subsequent 1966 Senate hearing identifies these pages as containing a partial list submitted by Minnie L. Gaston of government agencies and business corporations employing Booker T. Washington Business College graduates. Evidence classification: hearing bibliographic identification established; the four original pages and named-employer entries have not yet been inspected or attached. A digital reproduction has been targeted for recovery. Do not treat reported placements as individually verified until these pages and supporting records are examined.
THE RECORD & ITS LIMITS
BEHI will date and log each additional inspection and revise individual claims without automatically promoting the overall profile to Verified.
HISTORY WITH RECEIPTS™
Claims remain subject to individual source review. Additional archival material will be added as evidence is recovered.
No verified records are currently published in this category.
Cite This Profile
The Black Economic History Institute (BEHI) Digital Archive