Profile №14 BEHI-P014-JM
John Merrick
1859–1919
Insurance Founder · Barber · Business Organizer
Overview
TAKEAWAY: Merrick connected Durham service businesses and insurance experience with North Carolina Mutual’s founding. His collaborators’ roles and company finances remain distinct from personal wealth.
BEHI PROFILE — RESEARCH IN PROGRESS — UPDATED NOVEMBER 4, 2026. EVIDENCE IS CLASSIFIED CLAIM BY CLAIM; ATTRIBUTED ACCOUNTS AND UNRESOLVED RESEARCH QUESTIONS ARE IDENTIFIED THROUGHOUT.
OVERVIEW
John Merrick helped turn Durham barbering, property ownership and fraternal insurance experience into a durable insurance institution. Born enslaved in 1859, he became the founding president of the North Carolina Mutual and Provident Association. This Profile follows his work with Aaron M. Moore, C. C. Spaulding and other collaborators, while keeping company finances distinct from personal wealth.
From local services to a financial institution
A base in skilled work
Barbering placed Merrick in a recurring service business with customers and collaborators. The reported shops and property interests form a business history that preceded the insurance company.
Experience in collective protection
The retrospective Royal Knights account describes participation in a separate fraternal assessment organization. It provides context for insurance organizing without merging the two institutions.
A legally constituted association
The 1899 act’s inspected first page identifies Merrick among eight incorporators and names death, sickness, accident, and burial benefits as purposes.
An institution beyond one life
Premium collections, payments, and year-end accounts show company activity on a measurable scale. The 1919 figures also include months under successor leadership after Merrick’s death.
Evidence register: BEHI-P014-S01, S04, S06, S12. Sources: 1899 act reproduction; Andrews, John Merrick: A Biographical Sketch (1920), pp. 31–34, 43–45, 228–229. BEHI analysis connects these activities while preserving the separate evidence and ownership of each enterprise.
From service businesses to insurance and allied institutions.
Merrick’s initiative within a collaborative organization.
Charter, company publication and reproduced regulatory accounts.
EXACT ACCOMPLISHMENTS
The inspected first page of the 1899 act names John Merrick among eight incorporators of the North Carolina Mutual and Provident Association.
The inspected 1914 anniversary publication identifies Merrick as founder and president alongside A. M. Moore and C. C. Spaulding in named leadership roles.
The reproduced year-end 1919 statement reports premiums of $1,224,541.69 and admitted assets of $755,744.26. These company figures include months after Merrick’s death.
THE RECORD & ITS LIMITS
Barbershops supplied customers, working experience and business relationships. Reported property and product ventures broaden the story, but their contracts and ledgers remain acquisition targets.
The 1899 act names eight incorporators; the biography names seven earlier organizers. These lists describe different stages and should retain their separate identities.
The 1919 appendix reports company premiums, assets and claims. It does not measure Merrick’s personal net worth or isolate only the months of his presidency.
READING THE EVIDENCE
Merrick’s significance lies in organizing recurring payments, risk protection and a working financial institution within a segregated economy. The evidence supports studying institutional capital and collective management without converting corporate totals into a personal fortune.
What Would Move This Profile Forward?
These are the next evidence priorities for strengthening this Profile. Each identifies a concrete research step and what it could help establish.
- Retrieve the deeds behind the acquired indexes
Use the Durham deed and mortgage index locators to obtain complete instruments, including consideration, legal descriptions and releases. These would establish transactions and financing rather than index references alone.
- Complete the estate record
Obtain John Merrick’s 1919 estate file and Martha Merrick’s 1939 will and associated probate records. Inventories, debts and settlements would help establish personal holdings and succession separately from company assets.
- Trace founding capital and legal organization
Acquire the complete 1899 charter, early minutes, signed subscriptions, cash books and deposits. These would test the reported founding contributions and distinguish organizers from legal incorporators.
- Reconcile company financial milestones
Inspect original annual returns and regulatory examinations, especially the 1913 and 1918–1920 records. These would clarify reporting dates, financial measures and discrepancies in published totals.
Read the Research Gaps & Open Questions for the unresolved issues and evidence limits. New material is reviewed before claims or classifications change.
THE RECEIPTS OR EVIDENCE SUPPORTING THIS PROFILE
Evidence labels apply to individual claims. Read the evidence guide and content-condition definitions.
| SOURCE / LOCATOR | RECORD / CONTEXT | DATE / PERIOD | EVIDENCE STATUS | SUPPORT / LIMITS |
|---|---|---|---|---|
| Incorporation act — first-page reproduction BEHI-P014-S01 | Private Laws of North Carolina, 1899, chapter 156; reproduced first page | 1899 | VERIFIED | The inspected first page names John Merrick, A. M. Moore, J. E. Shepard, W. G. Pearson, D. T. Watson, T. O. Fuller, E. A. Johnson and W. C. Bruce. It creates the North Carolina Mutual and Provident Association for sixty years and describes death, sickness, accident and burial benefits. The reproduction ends during section 2. The remaining act, ratification date and later amendments were not inspected. Named incorporators are not automatically a cash subscription ledger. |
| Fifteenth-anniversary premium-income spread BEHI-P014-S02 | Duke exhibit item 8537; anniversary spread, 1899–1914 | April 1, 1914 | VERIFIED | The inspected company publication labels John Merrick founder and president, A. M. Moore secretary-treasurer and C. C. Spaulding vice-president/general manager. Its premium chart ends at $358,311. Andrews’s annual table assigns that figure to 1913, and $404,766 to 1914. The anniversary date is not proof that the last chart figure covers calendar 1914. Published company claims are not an independent audit or personal wealth. |
| Regulatory examination — reproduced extracts BEHI-P014-S11 | Andrews, pp. 223–227; PDF pp. 253–257 | April 21–24, 1920; condition December 31, 1919 | VERIFIED | The inspected book prints report extracts signed in print by E. T. Burr and S. F. Campbell, approved by J. R. Young April 24. They report a 1913 charter amendment and April 7, 1919 name amendment, test checks for 1916–1918 and a detailed 1919 check through agents’ reports, agency registers, cash journal and checks. This is an inspected printed reproduction; the original signed report and underlying books were not inspected. Andrews’s narrative May 12 announcement is a different event from the reported April 7 legal change. |
| 1919 financial statement — reproduced appendix BEHI-P014-S12 | Andrews, pp. 228–229; PDF pp. 258–259 | December 31, 1919; published 1920 | VERIFIED | The visually inspected statement prints premiums $1,224,541.69; rents/interest $42,497.93; opening balance $395,487.66; gross assets $774,935.32; admitted assets $755,744.26; liabilities $639,278.42; surplus $116,465.84; policyholder payments $401,240.66 and commissions $445,577.87. Its $1,662,527.28 total includes the opening balance and is not annual revenue. Premiums plus rents/interest equal $1,267,039.62 (Institute Analysis). The liabilities-plus-surplus total is printed $755,744.25, one cent below the assets-side total. No silent correction is made. This year-end account includes months after Merrick’s August death. |
| Institutional biography and historical marker BEHI-P014-S13 | NC DNCR, John Merrick 1859–1919 (G-109) | 2023; inspected October 4, 2026 | ATTRIBUTED | The state historical account describes his Durham move in 1880, the October 20, 1898 organizing meeting, February 1899 incorporation, subsequent Moore presidency, 1926 reinterment and July 11, 1943 launch of the Liberty ship John Merrick. These are institutional historical accounts. They do not establish personal net worth, an inspected estate inventory or present-day company operations. |
Background
TAKEAWAY: Institutional histories trace Merrick’s path from enslavement through skilled work and barbering to Durham business leadership. His insurance career developed within those earlier relationships.
BACKGROUND
Merrick was born on September 7, 1859, in Sampson County, North Carolina. Institutional histories describe his birth into slavery, work in bricklaying and barbering, and move to Durham in 1880. His business career developed through customers, partnership, family life and local institutions before the insurance association began.
Trade, customers, and the making of a business career
Working experience
Institutional and memorial accounts describe bricklaying before barbering. The transition matters because it places Merrick’s later leadership within a working life, rather than beginning his story at incorporation.
Durham · 1880
The state historical account dates his move to Durham to 1880. The growing commercial town supplied the setting for shops, customer relationships, and later collaborative institutions.
Partnership · 1892 account
John Wright’s retrospective account describes their shop partnership and dates his sale to Merrick to 1892. Recovering the agreement would clarify what assets, obligations, and goodwill changed hands.
Household & property
The biography reports a Fayetteville Street cottage and rental-house activity. Deeds and probate are needed to reconstruct how household property, business premises, and financing fitted together.
Evidence register: BEHI-P014-S03–S04, S13, S15. Andrews, John Merrick: A Biographical Sketch (1920), pp. 31–34; NC DNCR institutional biography. Early-life and shop narratives remain attributed; this is not a verified account of personal capital accumulation.
HISTORICAL & ECONOMIC CONTEXT
Sampson County and emancipation-era North Carolina.
Bricklaying and barbering as working experience.
A commercial base from 1880.
THE RECORD & ITS LIMITS
Andrews’s 1920 memorial supplies much of the detailed narrative. Its recollections require comparison with directories, employment records and contemporary property instruments.
Wright’s quoted account identifies the partnership and a reported 1892 sale. Multiple shops are reported, but an original sale agreement and complete employee roster remain unexamined.
The reported 1887 cottage and rental-house activity require deeds and estate accounts. Household property, personal liabilities and corporate assets must be reconciled separately.
READING THE EVIDENCE
A skilled service trade could create income and relationships across Durham’s segregated business environment. The exact accumulation of Merrick’s capital remains a documentary question, rather than a reason to omit the working life that preceded insurance.
EVIDENCE & CONTEXT
| Source | Description | Date | Evidence Classification | Notes |
|---|---|---|---|---|
| 1920 memorial biography — source and interpretation BEHI-P014-S03 | R. McCants Andrews, John Merrick: A Biographical Sketch, Durham: Seeman Printery; 264-page scan | 1920 | VERIFIED | The book and OCR were recovered. Relevant business passages were reviewed; selected financial, regulatory and portrait pages were inspected visually. This is a memorial biography, not a complete original business archive. Pages 42–43 acknowledge faulty memory and conflicting accounts. Verification here establishes the inspected publication and its wording, not every narrated event. |
| Barbering, shops and household real estate BEHI-P014-S04 | Andrews, pp. 31–34 | 1880–1892; published 1920 | ATTRIBUTED | John Wright’s retrospective account describes their Durham shop partnership and his 1892 sale to Merrick. Andrews reports three shops serving white customers, two serving Black customers, rental-house activity and an 1887 Fayetteville Street cottage. Original partnership agreements, sale instruments, payroll and property deeds were not recovered. Earlier 1887 and 1889–90 directory leads remain acquisition targets. |
| Institutional biography and historical marker BEHI-P014-S13 | NC DNCR, John Merrick 1859–1919 (G-109) | 2023; inspected October 4, 2026 | ATTRIBUTED | The state historical account describes his Durham move in 1880, the October 20, 1898 organizing meeting, February 1899 incorporation, subsequent Moore presidency, 1926 reinterment and July 11, 1943 launch of the Liberty ship John Merrick. These are institutional historical accounts. They do not establish personal net worth, an inspected estate inventory or present-day company operations. |
| Duke exhibit — founders and growth BEHI-P014-S14 | Soul & Service: early years and founder page | Modern exhibit; inspected October 4, 2026 | ATTRIBUTED | Duke describes Merrick’s enslaved origins, barbering and insurance leadership and joint Duke/NCCU archival custody. The early-years exhibit states premium income exceeded $1 million by 1918, conflicting with the 1920 table’s $819,771. The 1921 six-story building belongs to the successor period, after Merrick’s death. The exhibit is a research guide, not a substitute for annual returns. |
| Estate and deed reconciliation — acquisition register BEHI-P014-S15 | Durham probate and Register of Deeds research targets; earlier correspondence leads | 1881–1925 deeds; 1919/1939 estates | ATTRIBUTED | Durham County Register of Deeds supplied an eleven-page historical index PDF, which BEHI inspected: mortgage indexes on PDF pp. 1–4 and deed indexes on pp. 5–11, covering the requested 1881–1925 period. These are index locators, not the underlying deeds or mortgages, and do not establish transaction terms or an ownership chain. Original probate files also remain unrecovered: Merrick’s 1919 will, inventory, accounts and business interests, and Martha Merrick’s 1939 Will File No. 1441, identified in the State Archives published index; the original will and related estate-administration file remain uninspected. The 1901 Parrish sheriff-sale, 1887 cottage, 1911 Carr financing, Fidelity/Home Savings loans and $550 rent lead still require instrument-by-instrument reconciliation. |
The Problem
TAKEAWAY: The association addressed death, illness, injury, and burial expenses under unequal access to financial services. Charter purposes are distinct from measured household outcomes.
THE PROBLEM
Death, sickness and injury could interrupt wages and impose burial costs on families. The 1899 act states a purpose of relief for widows, orphans, sick or injured members and burial of the dead. Merrick and his collaborators built within a racial order that constrained access to capital, professional opportunity and financial services.
Insurance turned household risks into organizational duties
Death & burial
The charter describes death and burial benefits. BEHI analysis: these purposes addressed expenses and losses that a household might struggle to meet from current income alone.
Sickness & accident
The act also describes sickness and accident protection. The charter establishes authorized purposes; policy forms and claims records are needed to show actual coverage and eligibility.
Collect & account
Premiums had to move through agents and company records. The reproduced examination describes checking agent reports, registers, the cash journal, and checks for the 1919 account.
Hold resources for obligations
The year-end statement distinguishes admitted assets, liabilities, and surplus. Collections could not responsibly be read as freely available profit when the company also owed benefits and other obligations.
Evidence register: BEHI-P014-S01, S11–S12. 1899 act reproduction; Andrews, John Merrick: A Biographical Sketch (1920), pp. 223–229. This risk-and-administration diagram is BEHI analysis of stated purposes and reproduced accounts, not a claim about every policy or household outcome.
DIMENSIONS OF THE PROBLEM
Income interruption and funeral expenses.
Recurring premiums and regulatory deposits.
Reliable collection, records and payment.
HOW THE PROBLEM SHOWED UP
The inspected charter page establishes the association’s stated benefit purposes. It does not establish every policy term or the outcome of every claim.
The biography describes a $10,000 South Carolina deposit and mortgages supporting a bank draft. Recovering the actual instruments will establish who pledged what and on which terms.
The reproduced 1920 examination describes agents’ reports, registers, cash journals and checks. It illuminates the company’s later controls, while the underlying books remain uninspected.
READING THE EVIDENCE
Insurance required more than an inspiring founding story: it required collections, reserves, administration and confidence that benefits would be paid. The sources allow those business problems to be studied at different levels of evidence.
EVIDENCE & CONTEXT
| Source | Description | Date | Evidence Classification | Notes |
|---|---|---|---|---|
| Incorporation act — first-page reproduction BEHI-P014-S01 | Private Laws of North Carolina, 1899, chapter 156; reproduced first page | 1899 | VERIFIED | The inspected first page names John Merrick, A. M. Moore, J. E. Shepard, W. G. Pearson, D. T. Watson, T. O. Fuller, E. A. Johnson and W. C. Bruce. It creates the North Carolina Mutual and Provident Association for sixty years and describes death, sickness, accident and burial benefits. The reproduction ends during section 2. The remaining act, ratification date and later amendments were not inspected. Named incorporators are not automatically a cash subscription ledger. |
| Parrish Street offices and South Carolina deposit BEHI-P014-S08 | Andrews, pp. 87–89 | 1904–1905; published 1920 | ATTRIBUTED | The biography reports an $8,000 Parrish Street site and office project, and a $10,000 South Carolina deposit supported by Merrick and Moore mortgaging property and obtaining a Fidelity draft. This is not a recovered mortgage or bank entry. Earlier $6,000 Fidelity-loan and $550 monthly-rent leads remain separate unresolved transactions; they must not be substituted for the regulatory deposit. |
| Regulatory examination — reproduced extracts BEHI-P014-S11 | Andrews, pp. 223–227; PDF pp. 253–257 | April 21–24, 1920; condition December 31, 1919 | VERIFIED | The inspected book prints report extracts signed in print by E. T. Burr and S. F. Campbell, approved by J. R. Young April 24. They report a 1913 charter amendment and April 7, 1919 name amendment, test checks for 1916–1918 and a detailed 1919 check through agents’ reports, agency registers, cash journal and checks. This is an inspected printed reproduction; the original signed report and underlying books were not inspected. Andrews’s narrative May 12 announcement is a different event from the reported April 7 legal change. |
| 1919 financial statement — reproduced appendix BEHI-P014-S12 | Andrews, pp. 228–229; PDF pp. 258–259 | December 31, 1919; published 1920 | VERIFIED | The visually inspected statement prints premiums $1,224,541.69; rents/interest $42,497.93; opening balance $395,487.66; gross assets $774,935.32; admitted assets $755,744.26; liabilities $639,278.42; surplus $116,465.84; policyholder payments $401,240.66 and commissions $445,577.87. Its $1,662,527.28 total includes the opening balance and is not annual revenue. Premiums plus rents/interest equal $1,267,039.62 (Institute Analysis). The liabilities-plus-surplus total is printed $755,744.25, one cent below the assets-side total. No silent correction is made. This year-end account includes months after Merrick’s August death. |
What He Built
TAKEAWAY: Merrick’s central institution was organized in 1898 and incorporated in 1899. Barbering, products, property, and collaborative ventures require separate business histories.
WHAT HE BUILT
Merrick’s central institution was the North Carolina Mutual and Provident Association, organized in 1898 and incorporated in 1899. His broader reported business activity included barbering, property, a dandruff preparation, Royal Knights insurance, and collaborative bank and drugstore ventures. Each enterprise retains its own identity.
A network of enterprises with distinct roles
Barbering & products
Shops supplied services; the reported dandruff preparation added a product offer. The reproduced advertisement’s $1 bottle price is an offer, with sales, efficacy, and profitability still unverified.
Property & premises
The reported cottage, rental houses, and Parrish Street office project involve different kinds of property. Household ownership, rent collection, and company premises require separate instruments.
Fraternal & commercial insurance
Royal Knights and North Carolina Mutual represent different organizations and stages of experience. Their assessment funds, premium accounts, and ownership cannot be combined.
Banking & retail collaboration
The biography describes bank organizing in 1907 and Bull City Drug in 1908. These allied ventures show reported cooperation; stock, minutes, and sale records are needed to establish individual interests.
Merrick · founder & president
The 1914 anniversary publication identifies his founding and presidential role.
Moore · secretary-treasurer
The same publication identifies A. M. Moore’s office, making financial administration visible alongside founding initiative.
Spaulding · vice-president / general manager
The spread identifies C. C. Spaulding’s management role. Executive titles provide a dated leadership map, not percentages of ownership.
Evidence register: BEHI-P014-S02, S04–S06, S08–S09. 1914 anniversary spread; Andrews, John Merrick: A Biographical Sketch (1920), pp. 31–45, 54–63, 87–89. The enterprise network is a BEHI synthesis, not a verified consolidated company structure.
THE ENTERPRISE SYSTEM
Founding presidency and collaborative management.
Shops, rental houses and premises.
Fraternal, banking and retail activity.
THE RECORD & ITS LIMITS
Royal Knights preceded North Carolina Mutual and was a separate assessment organization. Its acquisition cannot be treated as Mutual’s incorporation.
The 1914 anniversary spread identifies Merrick, Moore and Spaulding in executive roles. A title or participation in an organizing meeting does not determine stock ownership.
The dandruff advertisement describes a product and price. It does not prove medical effectiveness, a patent, registered trademark or profitable sales.
READING THE EVIDENCE
Merrick’s businesses formed a network of services and institutions. The strongest interpretation preserves their connections while testing the ownership, financing and operating history of each one separately.
EVIDENCE & CONTEXT
| Source | Description | Date | Evidence Classification | Notes |
|---|---|---|---|---|
| Incorporation act — first-page reproduction BEHI-P014-S01 | Private Laws of North Carolina, 1899, chapter 156; reproduced first page | 1899 | VERIFIED | The inspected first page names John Merrick, A. M. Moore, J. E. Shepard, W. G. Pearson, D. T. Watson, T. O. Fuller, E. A. Johnson and W. C. Bruce. It creates the North Carolina Mutual and Provident Association for sixty years and describes death, sickness, accident and burial benefits. The reproduction ends during section 2. The remaining act, ratification date and later amendments were not inspected. Named incorporators are not automatically a cash subscription ledger. |
| Fifteenth-anniversary premium-income spread BEHI-P014-S02 | Duke exhibit item 8537; anniversary spread, 1899–1914 | April 1, 1914 | VERIFIED | The inspected company publication labels John Merrick founder and president, A. M. Moore secretary-treasurer and C. C. Spaulding vice-president/general manager. Its premium chart ends at $358,311. Andrews’s annual table assigns that figure to 1913, and $404,766 to 1914. The anniversary date is not proof that the last chart figure covers calendar 1914. Published company claims are not an independent audit or personal wealth. |
| Barbering, shops and household real estate BEHI-P014-S04 | Andrews, pp. 31–34 | 1880–1892; published 1920 | ATTRIBUTED | John Wright’s retrospective account describes their Durham shop partnership and his 1892 sale to Merrick. Andrews reports three shops serving white customers, two serving Black customers, rental-house activity and an 1887 Fayetteville Street cottage. Original partnership agreements, sale instruments, payroll and property deeds were not recovered. Earlier 1887 and 1889–90 directory leads remain acquisition targets. |
| Dandruff preparation and advertising BEHI-P014-S05 | Andrews, pp. 35–36; advertisements copied from a notebook | About 1890; published 1920 | ATTRIBUTED | Andrews reproduces promotional copy for John Merrick & Co., 104 West Main Street, with a $1 bottle price. He says the notebook was found after Merrick’s death. This supports an attributed trade-name and advertising account; efficacy, patent ownership, trademark registration, sales volume and profit remain unverified. |
| Royal Knights of King David acquisition BEHI-P014-S06 | Andrews, pp. 43–45; W. G. Pearson’s account | September 24, 1883; published 1920 | ATTRIBUTED | The retrospective account identifies Merrick, John Wright, W. A. Day, J. D. Morgan and T. J. Jones in the acquisition from Reverend Morris. Royal Knights was a separate fraternal assessment organization. Its experience is relevant context, but must not be represented as North Carolina Mutual’s 1899 incorporation or merged cash account. |
| Insurance organizers and reported subscriptions BEHI-P014-S07 | Andrews, pp. 64–66 | 1898–1899; published 1920 | ATTRIBUTED | Andrews names seven 1898 organizers and reports $50 each in capital stock, business beginning April 1, 1899, and a later offer to return $50 plus interest for releases. Seven times $50 equals $350 as Institute Analysis of reported subscriptions. No founding cash book, bank deposit, subscription instrument or executed release was inspected. The organizer list differs from the eight names on the charter’s first page. |
| Bank, drugstore and allied enterprise accounts BEHI-P014-S09 | Andrews, pp. 54–63 | 1907–1908; published 1920 | ATTRIBUTED | Andrews reproduces a July 29, 1907 bank-organizing notice and describes Bull City Drug’s 1908 organizers and later sale of stores. These are accounts of collaboration. Minutes, stock ownership, bank statements, drugstore sale contracts and manufacturing loss records were not inspected. Collective participation does not establish Merrick’s exclusive ownership. |
Accomplishments
TAKEAWAY: Merrick’s founding presidency helped establish an enduring insurance organization. The achievement was collaborative, and later growth belongs to succeeding leadership as well.
ACCOMPLISHMENTS
Merrick’s founding presidency helped establish an insurance organization that outlived him. Contemporary company material presents him as founder and president; the reproduced 1919 statement provides a concrete account of the company’s scale. The result was collaborative and continued under succeeding leadership.
Reported annual premium income: selected years
1899 · $840
1913 · $358,311
1914 · $404,766
1918 · $819,771
1919 · $1,224,541
Unit: nominal dollars of annual company premium income, as printed in Andrews’s annual table. Each bar starts at zero; the longest bar is $1,224,541. These are selected observations, not a complete annual series.
Evidence register: BEHI-P014-S10. Andrews, John Merrick: A Biographical Sketch (1920), pp. 105, 108–109. Verified scope: inspected publication and printed figures; original annual returns remain pending. The 1919 table uses rounded dollars, while the appendix reports $1,224,541.69. Duke’s modern exhibit dates the million-dollar threshold to 1918, in conflict with this table. Merrick died August 6, 1919, so the final bar includes successor-period activity.
Institutional growth
The printed series describes substantial expansion in premium collections. It does not establish an equivalent increase in profit, policy count, or Merrick’s personal wealth.
Collaborative achievement
The 1914 leadership spread names Merrick, Moore, and Spaulding. The company’s scale belongs to an organization with managers, agents, and policyholders as well as a founder.
ACCOMPLISHMENT LEDGER
Dates and evidence classifications apply to the specific findings below. Economic significance is BEHI analysis; evidence limits remain attached to each entry.
| DATE / PERIOD | ACCOMPLISHMENT | ECONOMIC SIGNIFICANCE | SOURCE / LOCATOR | EVIDENCE CLASSIFICATION | EVIDENCE LIMITS |
|---|---|---|---|---|---|
| 1899 | Participation in incorporation of the benefit association The inspected first page of the act names Merrick among eight incorporators. | Documents collective formation of an insurance institution. | Incorporation act — first-page reproduction BEHI-P014-S01 Private Laws of North Carolina, chapter 156, first page; BEHI-P014-S01. | VERIFIED | Only the first page was inspected; named incorporators are not a verified cash-subscription ledger. |
| April 1, 1914 publication | Documented founding presidency The anniversary publication identifies Merrick as founder and president alongside Moore and Spaulding. | Establishes a named leadership role within a collaborative operating institution. | Fifteenth-anniversary premium-income spread BEHI-P014-S02 Fifteenth-anniversary spread; BEHI-P014-S02. | VERIFIED | Verification covers the publication and its identification; its chart date is not automatically the year of each reported figure. |
| Year-end 1919 | Institution continued at a measurable operating scale The reproduced statement reports premiums of $1,224,541.69 and policyholder payments of $401,240.66. | Shows institutional operations and continuity beyond the founding president. | 1919 financial statement — reproduced appendix BEHI-P014-S12 Andrews, pp. 228–229; BEHI-P014-S12. | VERIFIED | Printed reproduction, not underlying ledgers. Full-year figures include successor leadership after Merrick’s August death and are not personal wealth. |
ACCOMPLISHMENT CATEGORIES
An incorporated benefit association.
A widening insurance operation.
Management and operations beyond the founder.
THE RECORD & ITS LIMITS
The inspected 1899 act names Merrick among the incorporators and defines the association’s benefit purposes; the 1914 company publication identifies his presidency.
The appendix gives 1919 premiums of $1,224,541.69 and policyholder payments of $401,240.66. Those amounts cover the full year, including months after his death.
Moore, Spaulding, agents, office staff and other organizers were part of the institution. The 1921 six-story building belongs to the successor period and is not a completed lifetime accomplishment of Merrick.
READING THE EVIDENCE
The achievement was an operating institution capable of collecting premiums, administering benefits and continuing through leadership change. Claims about being the largest or first require a stated date, measure and comparison set.
EVIDENCE & CONTEXT
| Source | Description | Date | Evidence Classification | Notes |
|---|---|---|---|---|
| Incorporation act — first-page reproduction BEHI-P014-S01 | Private Laws of North Carolina, 1899, chapter 156; reproduced first page | 1899 | VERIFIED | The inspected first page names John Merrick, A. M. Moore, J. E. Shepard, W. G. Pearson, D. T. Watson, T. O. Fuller, E. A. Johnson and W. C. Bruce. It creates the North Carolina Mutual and Provident Association for sixty years and describes death, sickness, accident and burial benefits. The reproduction ends during section 2. The remaining act, ratification date and later amendments were not inspected. Named incorporators are not automatically a cash subscription ledger. |
| Fifteenth-anniversary premium-income spread BEHI-P014-S02 | Duke exhibit item 8537; anniversary spread, 1899–1914 | April 1, 1914 | VERIFIED | The inspected company publication labels John Merrick founder and president, A. M. Moore secretary-treasurer and C. C. Spaulding vice-president/general manager. Its premium chart ends at $358,311. Andrews’s annual table assigns that figure to 1913, and $404,766 to 1914. The anniversary date is not proof that the last chart figure covers calendar 1914. Published company claims are not an independent audit or personal wealth. |
| Regulatory examination — reproduced extracts BEHI-P014-S11 | Andrews, pp. 223–227; PDF pp. 253–257 | April 21–24, 1920; condition December 31, 1919 | VERIFIED | The inspected book prints report extracts signed in print by E. T. Burr and S. F. Campbell, approved by J. R. Young April 24. They report a 1913 charter amendment and April 7, 1919 name amendment, test checks for 1916–1918 and a detailed 1919 check through agents’ reports, agency registers, cash journal and checks. This is an inspected printed reproduction; the original signed report and underlying books were not inspected. Andrews’s narrative May 12 announcement is a different event from the reported April 7 legal change. |
| 1919 financial statement — reproduced appendix BEHI-P014-S12 | Andrews, pp. 228–229; PDF pp. 258–259 | December 31, 1919; published 1920 | VERIFIED | The visually inspected statement prints premiums $1,224,541.69; rents/interest $42,497.93; opening balance $395,487.66; gross assets $774,935.32; admitted assets $755,744.26; liabilities $639,278.42; surplus $116,465.84; policyholder payments $401,240.66 and commissions $445,577.87. Its $1,662,527.28 total includes the opening balance and is not annual revenue. Premiums plus rents/interest equal $1,267,039.62 (Institute Analysis). The liabilities-plus-surplus total is printed $755,744.25, one cent below the assets-side total. No silent correction is made. This year-end account includes months after Merrick’s August death. |
| Institutional biography and historical marker BEHI-P014-S13 | NC DNCR, John Merrick 1859–1919 (G-109) | 2023; inspected October 4, 2026 | ATTRIBUTED | The state historical account describes his Durham move in 1880, the October 20, 1898 organizing meeting, February 1899 incorporation, subsequent Moore presidency, 1926 reinterment and July 11, 1943 launch of the Liberty ship John Merrick. These are institutional historical accounts. They do not establish personal net worth, an inspected estate inventory or present-day company operations. |
| Duke exhibit — founders and growth BEHI-P014-S14 | Soul & Service: early years and founder page | Modern exhibit; inspected October 4, 2026 | ATTRIBUTED | Duke describes Merrick’s enslaved origins, barbering and insurance leadership and joint Duke/NCCU archival custody. The early-years exhibit states premium income exceeded $1 million by 1918, conflicting with the 1920 table’s $819,771. The 1921 six-story building belongs to the successor period, after Merrick’s death. The exhibit is a research guide, not a substitute for annual returns. |
Economic Impact
TAKEAWAY: Collections, benefits, assets, and administration measure the insurance institution. Company statements do not supply an audited personal fortune for Merrick.
ECONOMIC IMPACT
Read the reproduced examination and December 31, 1919 financial statement in Receipts → Documents. The document card preserves selected-page coverage and distinguishes company figures from personal wealth.
Merrick’s economic contribution is best examined through the insurance company’s collections, benefit payments, assets and administration, alongside his separately reported shop and property interests. The financial appendix offers measurable institutional scale; it does not provide an audited personal fortune.
1919: resources, obligations, and money paid out
Liabilities and surplus — December 31, 1919
Company liabilities
$639,278.42 · about 84.6% of the sum of the listed components.
Company surplus
$116,465.84 · about 15.4% of that same sum.
BEHI calculation: listed components sum to $755,744.26, matching admitted assets. The publication prints their total as $755,744.25, one cent lower; that discrepancy remains unresolved. Surplus is a company balance-sheet category, not a personal estate or an annual profit figure.
Annual receipts categories
$1,224,541.69 premiums plus $42,497.93 rents and interest = $1,267,039.62 by BEHI calculation. The $395,487.66 opening balance is carried forward, rather than new annual revenue.
Policyholder payments
$401,240.66 in sick/death claims and other policyholder payments. This shows a flow to policyholders; the statement does not identify how many households received payments.
Agent commissions
$445,577.87 in commissions. This is a distribution expense category, not an employee count or a complete payroll figure.
Assets at year end
Gross assets are printed as $774,935.32 and admitted assets as $755,744.26. They are separate measures; neither is Merrick’s personal net worth.
Evidence register: BEHI-P014-S12. Andrews, John Merrick: A Biographical Sketch (1920), pp. 228–229. Nominal historical dollars, North Carolina Mutual company account at December 31, 1919. Inspected printed reproduction; original return and underlying books pending. The year extends beyond Merrick’s August death.
KEY ECONOMIC INDICATORS
Each measure identifies its entity, period, source and evidence limits. Dollar amounts are nominal historical U.S. dollars. Assets, revenue, profit, transaction amounts and employment measures are distinct. “Not yet established” identifies a research gap, not zero or “not applicable.”
| MEASURE / VALUE | ENTITY / PERIOD | SOURCE / LOCATOR | CONTENT CONDITION / EVIDENCE CLASSIFICATION | INTERPRETATION / LIMITS |
|---|---|---|---|---|
| Premium income $1,224,541.69 | North Carolina Mutual company 1919 | Andrews, 1920, pp. 228–229 (PDF pp. 258–259); BEHI-P014-S12. | Documented VERIFIED | Verified printed reproduction; original returns not inspected. Includes months after Merrick’s August death. |
| Admitted assets $755,744.26 | North Carolina Mutual company December 31, 1919 | Andrews, 1920, pp. 228–229 (PDF pp. 258–259); BEHI-P014-S12. | Documented VERIFIED | Assets-side total. Printed liabilities-plus-surplus total differs by one cent; no silent correction. |
| Policyholder payments $401,240.66 | North Carolina Mutual company 1919 | Andrews, 1920, pp. 228–229 (PDF pp. 258–259); BEHI-P014-S12. | Documented VERIFIED | Company payments, not profit, payroll or Merrick’s personal income. |
| Personal net estate Not yet established | John Merrick estate Reporting period not established | Research gap; see Evidence & Context and Receipts. | Not yet established Evidence classification: not assigned to an unresolved answer. | Company assets cannot substitute for probate inventory, debts and ownership records. Research Gap: Personal net estate |
For evidence-label definitions, see the Receipts evidence guide.
CHANNELS OF ECONOMIC IMPACT
Recurring collections supporting insurance obligations.
Money returned to policyholders and paid to agents.
Assets held against liabilities and reserves.
THE RECORD & ITS LIMITS
Premium income, total cash available, insurance in force, assets, surplus and profit are different measures. The opening balance must not be counted as new revenue.
The 1919 annual statement extends past Merrick’s death. It measures a company year, not the value of his estate or his personal contribution during that year.
The biography’s table gives $819,771 in 1918; Duke’s exhibit says more than $1 million by that year. Use the inspected table’s amount as the printed claim while seeking original annual returns.
READING THE EVIDENCE
Insurance pooled payments and maintained assets to meet household obligations. These figures demonstrate institutional activity, but they cannot by themselves quantify regional employment, net community wealth, inflation-adjusted impact or Merrick’s personal net worth.
1919 COMPANY FIGURES — PRINTED APPENDIX
| Measure | Amount | Meaning and limit |
|---|---|---|
| Premiums | $1,224,541.69 | Premium receipts; not profit or personal income. |
| Rents and interest | $42,497.93 | Separate receipt category. |
| Premiums + rents/interest | $1,267,039.62 | Institute Analysis; sum of printed receipt categories. |
| Opening balance | $395,487.66 | Carried forward; not new 1919 revenue. |
| Printed receipts-side total | $1,662,527.28 | Includes opening balance. |
| Admitted assets | $755,744.26 | Company balance-sheet amount; not personal wealth. |
| Liabilities | $639,278.42 | Company obligations. |
| Unassigned funds / surplus | $116,465.84 | Company surplus; not Merrick’s estate. |
| Policyholder payments | $401,240.66 | Sick/death claims and all other payments to policyholders. |
| Agent commissions | $445,577.87 | An expense category, not an employee count. |
Source: Andrews, pp. 228–229, reproduced statement as of December 31, 1919. The statement prints the liabilities-and-surplus total as $755,744.25, one cent below the assets-side total. Original regulatory returns are needed to resolve the difference. Merrick died August 6, 1919.
EVIDENCE & CONTEXT
| Source | Description | Date | Evidence Classification | Notes |
|---|---|---|---|---|
| Fifteenth-anniversary premium-income spread BEHI-P014-S02 | Duke exhibit item 8537; anniversary spread, 1899–1914 | April 1, 1914 | VERIFIED | The inspected company publication labels John Merrick founder and president, A. M. Moore secretary-treasurer and C. C. Spaulding vice-president/general manager. Its premium chart ends at $358,311. Andrews’s annual table assigns that figure to 1913, and $404,766 to 1914. The anniversary date is not proof that the last chart figure covers calendar 1914. Published company claims are not an independent audit or personal wealth. |
| Annual premium-income table BEHI-P014-S10 | Andrews, pp. 105, 108–109; PDF pp. 127, 130–131 | 1899–1919; published 1920 | VERIFIED | The inspected printed table gives $840 for 1899, $358,311 for 1913, $404,766 for 1914, $819,771 for 1918 and $1,224,541 for 1919. These are rounded annual premium figures in a publication. Duke’s modern exhibit places more than $1 million in 1918; the conflict is preserved pending original returns. Premiums are not profit or Merrick’s personal income. |
| Regulatory examination — reproduced extracts BEHI-P014-S11 | Andrews, pp. 223–227; PDF pp. 253–257 | April 21–24, 1920; condition December 31, 1919 | VERIFIED | The inspected book prints report extracts signed in print by E. T. Burr and S. F. Campbell, approved by J. R. Young April 24. They report a 1913 charter amendment and April 7, 1919 name amendment, test checks for 1916–1918 and a detailed 1919 check through agents’ reports, agency registers, cash journal and checks. This is an inspected printed reproduction; the original signed report and underlying books were not inspected. Andrews’s narrative May 12 announcement is a different event from the reported April 7 legal change. |
| 1919 financial statement — reproduced appendix BEHI-P014-S12 | Andrews, pp. 228–229; PDF pp. 258–259 | December 31, 1919; published 1920 | VERIFIED | The visually inspected statement prints premiums $1,224,541.69; rents/interest $42,497.93; opening balance $395,487.66; gross assets $774,935.32; admitted assets $755,744.26; liabilities $639,278.42; surplus $116,465.84; policyholder payments $401,240.66 and commissions $445,577.87. Its $1,662,527.28 total includes the opening balance and is not annual revenue. Premiums plus rents/interest equal $1,267,039.62 (Institute Analysis). The liabilities-plus-surplus total is printed $755,744.25, one cent below the assets-side total. No silent correction is made. This year-end account includes months after Merrick’s August death. |
| Duke exhibit — founders and growth BEHI-P014-S14 | Soul & Service: early years and founder page | Modern exhibit; inspected October 4, 2026 | ATTRIBUTED | Duke describes Merrick’s enslaved origins, barbering and insurance leadership and joint Duke/NCCU archival custody. The early-years exhibit states premium income exceeded $1 million by 1918, conflicting with the 1920 table’s $819,771. The 1921 six-story building belongs to the successor period, after Merrick’s death. The exhibit is a research guide, not a substitute for annual returns. |
| Estate and deed reconciliation — acquisition register BEHI-P014-S15 | Durham probate and Register of Deeds research targets; earlier correspondence leads | 1881–1925 deeds; 1919/1939 estates | ATTRIBUTED | Durham County Register of Deeds supplied an eleven-page historical index PDF, which BEHI inspected: mortgage indexes on PDF pp. 1–4 and deed indexes on pp. 5–11, covering the requested 1881–1925 period. These are index locators, not the underlying deeds or mortgages, and do not establish transaction terms or an ownership chain. Original probate files also remain unrecovered: Merrick’s 1919 will, inventory, accounts and business interests, and Martha Merrick’s 1939 Will File No. 1441, identified in the State Archives published index; the original will and related estate-administration file remain uninspected. The 1901 Parrish sheriff-sale, 1887 cottage, 1911 Carr financing, Fidelity/Home Savings loans and $550 rent lead still require instrument-by-instrument reconciliation. |
Timeline
TAKEAWAY: The chronology separates Merrick’s lifetime, legal formation, operating milestones, and later commemoration. Printed reproductions retain their particular evidence limits.
TIMELINE
The chronology separates Merrick’s lifetime, the company’s legal and operating milestones, and later commemoration. A date in a printed reproduction is classified for that specific evidence; missing underlying documents remain identified.
A career timeline with organizational boundaries
- 1880
Durham service business
Move and barbering in institutional and retrospective accounts.
- 1883
Royal Knights experience
Reported acquisition of a separate fraternal organization.
- 1898
Insurance organization
October 20 meeting in the state account; subscriptions require originals.
- 1899
Incorporation & opening
Act first page inspected; April 1 business opening reported by Andrews.
- 1904–1908
Premises & allied ventures
Office/deposit account, bank organizing, and drugstore activity reported.
- 1914
Leadership documented
April 1 anniversary spread identifies executive roles.
- 1919
Succession & accounts
August 6 death; December 31 company statement includes later months.
- 1920–1943
Examination & memory
Reproduced 1920 examination; later buildings and honors belong to later periods.
Evidence register: BEHI-P014-S01–S02, S04, S06–S09, S11–S14. This visual index preserves the classifications in the detailed chronology below. Organization, incorporation, business opening, legal amendment, public announcement, and year-end accounting are distinct events; later activity is not credited entirely to Merrick’s lifetime.
TIMELINE AT A GLANCE
1859–1919.
Organization, incorporation and expansion.
Successor leadership and public memory.
THE RECORD & ITS LIMITS
The 1898 organization, 1899 incorporation and April 1899 business opening are distinct milestones.
The reproduced examination reports April 7, 1919; Andrews describes a May 12 announcement. Legal amendment and announcement can occur on different dates.
Year-end 1919 finances and the 1921 building include work after Merrick’s death.
READING THE EVIDENCE
The timeline becomes more reliable when each entry identifies its source and the event that the date actually describes.
DOCUMENTED & ATTRIBUTED CHRONOLOGY
| Date | Event | Classification |
|---|---|---|
| 1859-09-07 | Birth in Sampson County, North Carolina; enslaved origins described in the biography and institutional accounts. BEHI-P014-S03; BEHI-P014-S14 | ATTRIBUTED |
| 1880 | Move to Durham and barbering business, according to the state historical account. BEHI-P014-S04; BEHI-P014-S13 | ATTRIBUTED |
| 1883-09-24 | Reported Royal Knights acquisition with four collaborators; a separate organization from Mutual. BEHI-P014-S06 | ATTRIBUTED |
| 1887 | Reported Fayetteville Street cottage; deed remains an acquisition target. BEHI-P014-S04; BEHI-P014-S15 | ATTRIBUTED |
| c. 1890 | Dandruff preparation and advertising described retrospectively. BEHI-P014-S05 | ATTRIBUTED |
| 1892 | John Wright’s account dates his sale of the shop business to Merrick. BEHI-P014-S04 | ATTRIBUTED |
| 1898-10-20 | Organizing meeting dated by NC DNCR; reported subscriptions require original records. BEHI-P014-S07; BEHI-P014-S13 | ATTRIBUTED |
| 1899 | Incorporation act, chapter 156, identifies Merrick among eight named incorporators; first page inspected. BEHI-P014-S01 | VERIFIED |
| 1899-04-01 | Opening for business dated by Andrews; earliest operational records requested. BEHI-P014-S07 | ATTRIBUTED |
| 1904–1905 | Reported Parrish Street offices and South Carolina expansion deposit; original property and banking records pending. BEHI-P014-S08 | ATTRIBUTED |
| 1907-07-29 | Bank-organizing notice reproduced in Andrews. BEHI-P014-S09 | ATTRIBUTED |
| 1908 | Bull City Drug organization described in Andrews. BEHI-P014-S09 | ATTRIBUTED |
| 1913-08-06 | Charter amendment reported in the reproduced 1920 examination; original amendment pending. BEHI-P014-S11 | VERIFIED |
| 1914-04-01 | Fifteenth-anniversary company spread identifies Merrick as founder and president. BEHI-P014-S02 | VERIFIED |
| 1918 | Printed annual premium table reports $819,771; differs from Duke’s modern million-dollar account. BEHI-P014-S10; BEHI-P014-S14 | DISPUTED |
| 1919-04-07 | Name/charter change dated by the reproduced examination. Andrews’s narrative dates an officers’ announcement May 12. BEHI-P014-S11; BEHI-P014-S03 | VERIFIED |
| 1919-08-06 | Merrick’s death, dated in Andrews, p. 147. BEHI-P014-S03 | ATTRIBUTED |
| 1919-12-31 | Year-end company statement reports premiums $1,224,541.69; includes successor-period months. BEHI-P014-S12 | VERIFIED |
| 1920-04-21 | Regulatory examination report reproduced in the biography; approval dated April 24. BEHI-P014-S11 | VERIFIED |
| 1921 | Six-story Parrish Street building in Duke’s account; successor-period legacy. BEHI-P014-S14 | ATTRIBUTED |
| 1943-07-11 | Launch of Liberty ship John Merrick, dated by NC DNCR. BEHI-P014-S13 | ATTRIBUTED |
EVIDENCE & CONTEXT
| Source | Description | Date | Evidence Classification | Notes |
|---|---|---|---|---|
| Incorporation act — first-page reproduction BEHI-P014-S01 | Private Laws of North Carolina, 1899, chapter 156; reproduced first page | 1899 | VERIFIED | The inspected first page names John Merrick, A. M. Moore, J. E. Shepard, W. G. Pearson, D. T. Watson, T. O. Fuller, E. A. Johnson and W. C. Bruce. It creates the North Carolina Mutual and Provident Association for sixty years and describes death, sickness, accident and burial benefits. The reproduction ends during section 2. The remaining act, ratification date and later amendments were not inspected. Named incorporators are not automatically a cash subscription ledger. |
| Fifteenth-anniversary premium-income spread BEHI-P014-S02 | Duke exhibit item 8537; anniversary spread, 1899–1914 | April 1, 1914 | VERIFIED | The inspected company publication labels John Merrick founder and president, A. M. Moore secretary-treasurer and C. C. Spaulding vice-president/general manager. Its premium chart ends at $358,311. Andrews’s annual table assigns that figure to 1913, and $404,766 to 1914. The anniversary date is not proof that the last chart figure covers calendar 1914. Published company claims are not an independent audit or personal wealth. |
| Insurance organizers and reported subscriptions BEHI-P014-S07 | Andrews, pp. 64–66 | 1898–1899; published 1920 | ATTRIBUTED | Andrews names seven 1898 organizers and reports $50 each in capital stock, business beginning April 1, 1899, and a later offer to return $50 plus interest for releases. Seven times $50 equals $350 as Institute Analysis of reported subscriptions. No founding cash book, bank deposit, subscription instrument or executed release was inspected. The organizer list differs from the eight names on the charter’s first page. |
| Annual premium-income table BEHI-P014-S10 | Andrews, pp. 105, 108–109; PDF pp. 127, 130–131 | 1899–1919; published 1920 | VERIFIED | The inspected printed table gives $840 for 1899, $358,311 for 1913, $404,766 for 1914, $819,771 for 1918 and $1,224,541 for 1919. These are rounded annual premium figures in a publication. Duke’s modern exhibit places more than $1 million in 1918; the conflict is preserved pending original returns. Premiums are not profit or Merrick’s personal income. |
| Regulatory examination — reproduced extracts BEHI-P014-S11 | Andrews, pp. 223–227; PDF pp. 253–257 | April 21–24, 1920; condition December 31, 1919 | VERIFIED | The inspected book prints report extracts signed in print by E. T. Burr and S. F. Campbell, approved by J. R. Young April 24. They report a 1913 charter amendment and April 7, 1919 name amendment, test checks for 1916–1918 and a detailed 1919 check through agents’ reports, agency registers, cash journal and checks. This is an inspected printed reproduction; the original signed report and underlying books were not inspected. Andrews’s narrative May 12 announcement is a different event from the reported April 7 legal change. |
| 1919 financial statement — reproduced appendix BEHI-P014-S12 | Andrews, pp. 228–229; PDF pp. 258–259 | December 31, 1919; published 1920 | VERIFIED | The visually inspected statement prints premiums $1,224,541.69; rents/interest $42,497.93; opening balance $395,487.66; gross assets $774,935.32; admitted assets $755,744.26; liabilities $639,278.42; surplus $116,465.84; policyholder payments $401,240.66 and commissions $445,577.87. Its $1,662,527.28 total includes the opening balance and is not annual revenue. Premiums plus rents/interest equal $1,267,039.62 (Institute Analysis). The liabilities-plus-surplus total is printed $755,744.25, one cent below the assets-side total. No silent correction is made. This year-end account includes months after Merrick’s August death. |
| Institutional biography and historical marker BEHI-P014-S13 | NC DNCR, John Merrick 1859–1919 (G-109) | 2023; inspected October 4, 2026 | ATTRIBUTED | The state historical account describes his Durham move in 1880, the October 20, 1898 organizing meeting, February 1899 incorporation, subsequent Moore presidency, 1926 reinterment and July 11, 1943 launch of the Liberty ship John Merrick. These are institutional historical accounts. They do not establish personal net worth, an inspected estate inventory or present-day company operations. |
| Duke exhibit — founders and growth BEHI-P014-S14 | Soul & Service: early years and founder page | Modern exhibit; inspected October 4, 2026 | ATTRIBUTED | Duke describes Merrick’s enslaved origins, barbering and insurance leadership and joint Duke/NCCU archival custody. The early-years exhibit states premium income exceeded $1 million by 1918, conflicting with the 1920 table’s $819,771. The 1921 six-story building belongs to the successor period, after Merrick’s death. The exhibit is a research guide, not a substitute for annual returns. |
CHRONOLOGICAL RECORD
-
1859-09-07
Merrick — 1859-09-07 — Birth in Sampson County, North Carolina
John Merrick / North Carolina Mutual
Birth in Sampson County, North Carolina; enslaved origins described in the biography and institutional accounts. -
1880
Merrick — 1880 — Move to Durham and barbering business, according to the state historical account.
John Merrick / North Carolina Mutual
Move to Durham and barbering business, according to the state historical account. -
1883-09-24
Merrick — 1883-09-24 — Reported Royal Knights acquisition with four collaborators
John Merrick / North Carolina Mutual
Reported Royal Knights acquisition with four collaborators; a separate organization from Mutual. -
1887
Merrick — 1887 — Reported Fayetteville Street cottage
John Merrick / North Carolina Mutual
Reported Fayetteville Street cottage; deed remains an acquisition target. -
c. 1890
Merrick — c. 1890 — Dandruff preparation and advertising described retrospectively.
John Merrick / North Carolina Mutual
Dandruff preparation and advertising described retrospectively. -
1892
Merrick — 1892 — John Wright’s account dates his sale of the shop business to Merrick.
John Merrick / North Carolina Mutual
John Wright’s account dates his sale of the shop business to Merrick. -
1898-10-20
Merrick — 1898-10-20 — Organizing meeting dated by NC DNCR
John Merrick / North Carolina Mutual
Organizing meeting dated by NC DNCR; reported subscriptions require original records. -
1899
Merrick — 1899 — Incorporation act, chapter 156, identifies Merrick among eight named incorporators
John Merrick / North Carolina Mutual
Incorporation act, chapter 156, identifies Merrick among eight named incorporators; first page inspected. -
1899-04-01
Merrick — 1899-04-01 — Opening for business dated by Andrews
John Merrick / North Carolina Mutual
Opening for business dated by Andrews; earliest operational records requested. -
1904–1905
Merrick — 1904–1905 — Reported Parrish Street offices and South Carolina expansion deposit
John Merrick / North Carolina Mutual
Reported Parrish Street offices and South Carolina expansion deposit; original property and banking records pending. -
1907-07-29
Merrick — 1907-07-29 — Bank-organizing notice reproduced in Andrews.
John Merrick / North Carolina Mutual
Bank-organizing notice reproduced in Andrews. -
1908
Merrick — 1908 — Bull City Drug organization described in Andrews.
John Merrick / North Carolina Mutual
Bull City Drug organization described in Andrews. -
1913-08-06
Merrick — 1913-08-06 — Charter amendment reported in the reproduced 1920 examination
John Merrick / North Carolina Mutual
Charter amendment reported in the reproduced 1920 examination; original amendment pending. -
1914-04-01
Merrick — 1914-04-01 — Fifteenth-anniversary company spread identifies Merrick as founder and president.
John Merrick / North Carolina Mutual
Fifteenth-anniversary company spread identifies Merrick as founder and president. -
1918
Merrick — 1918 — Printed annual premium table reports $819,771
John Merrick / North Carolina Mutual
Printed annual premium table reports $819,771; differs from Duke’s modern million-dollar account. -
1919-04-07
Merrick — 1919-04-07 — Name/charter change dated by the reproduced examination. Andrews’s narrative dates an officers’ announcement May 12.
John Merrick / North Carolina Mutual
Name/charter change dated by the reproduced examination. Andrews’s narrative dates an officers’ announcement May 12. -
1919-08-06
Merrick — 1919-08-06 — Merrick’s death, dated in Andrews, p. 147.
John Merrick / North Carolina Mutual
Merrick’s death, dated in Andrews, p. 147. -
1919-12-31
Merrick — 1919-12-31 — Year-end company statement reports premiums $1,224,541.69
John Merrick / North Carolina Mutual
Year-end company statement reports premiums $1,224,541.69; includes successor-period months. -
1920-04-21
Merrick — 1920-04-21 — Regulatory examination report reproduced in the biography
John Merrick / North Carolina Mutual
Regulatory examination report reproduced in the biography; approval dated April 24. -
1921
Merrick — 1921 — Six-story Parrish Street building in Duke’s account
John Merrick / North Carolina Mutual
Six-story Parrish Street building in Duke’s account; successor-period legacy. -
1943-07-11
Merrick — 1943-07-11 — Launch of Liberty ship John Merrick, dated by NC DNCR.
John Merrick / North Carolina Mutual
Launch of Liberty ship John Merrick, dated by NC DNCR.
Myths & Disputes
TAKEAWAY: Merrick’s importance does not require a sole-founder story or inflated fortune. Organizer lists, income dates, and financial totals must be reconciled precisely.
MYTHS & DISPUTES
Merrick’s importance does not depend on an inflated fortune, a sole-founder story or a compressed chronology. The record contains different organizer lists, disputed income dating and financial totals that need careful definitions.
Five distinctions that change the business story
Evidence register: BEHI-P014-S01–S02, S07–S08, S10–S12, S14, S16. Andrews, John Merrick: A Biographical Sketch (1920) and the Duke reproductions. “Documented” describes the printed category or date assignment; disputed historical figures retain their uncertainty.
COMMON SOURCES OF CONFUSION
Organization and incorporation lists differ.
Premiums, assets and personal wealth differ.
Legal change, announcement and succession differ.
THE RECORD & ITS LIMITS
Andrews names seven 1898 organizers, including P. W. Dawkins. The first charter page names eight people, including T. O. Fuller and W. C. Bruce, and omits Dawkins. Preserve both lists without silently harmonizing them.
The inspected 1920 table gives $819,771 in 1918 and $1,224,541 in 1919. Duke’s exhibit dates the million-dollar threshold to 1918. Original annual returns are the next test.
The statement’s $1,662,527.28 includes $395,487.66 carried forward. Assets and surplus belong to the company account, while the estate and deed record remain unresolved.
READING THE EVIDENCE
Corrections strengthen the account by defining precisely what each source supports. A memorial narrative, a company advertisement and a reproduced regulatory examination should retain their different authority and limits.
EVIDENCE & CONTEXT
| Source | Description | Date | Evidence Classification | Notes |
|---|---|---|---|---|
| Incorporation act — first-page reproduction BEHI-P014-S01 | Private Laws of North Carolina, 1899, chapter 156; reproduced first page | 1899 | VERIFIED | The inspected first page names John Merrick, A. M. Moore, J. E. Shepard, W. G. Pearson, D. T. Watson, T. O. Fuller, E. A. Johnson and W. C. Bruce. It creates the North Carolina Mutual and Provident Association for sixty years and describes death, sickness, accident and burial benefits. The reproduction ends during section 2. The remaining act, ratification date and later amendments were not inspected. Named incorporators are not automatically a cash subscription ledger. |
| Fifteenth-anniversary premium-income spread BEHI-P014-S02 | Duke exhibit item 8537; anniversary spread, 1899–1914 | April 1, 1914 | VERIFIED | The inspected company publication labels John Merrick founder and president, A. M. Moore secretary-treasurer and C. C. Spaulding vice-president/general manager. Its premium chart ends at $358,311. Andrews’s annual table assigns that figure to 1913, and $404,766 to 1914. The anniversary date is not proof that the last chart figure covers calendar 1914. Published company claims are not an independent audit or personal wealth. |
| 1920 memorial biography — source and interpretation BEHI-P014-S03 | R. McCants Andrews, John Merrick: A Biographical Sketch, Durham: Seeman Printery; 264-page scan | 1920 | VERIFIED | The book and OCR were recovered. Relevant business passages were reviewed; selected financial, regulatory and portrait pages were inspected visually. This is a memorial biography, not a complete original business archive. Pages 42–43 acknowledge faulty memory and conflicting accounts. Verification here establishes the inspected publication and its wording, not every narrated event. |
| Insurance organizers and reported subscriptions BEHI-P014-S07 | Andrews, pp. 64–66 | 1898–1899; published 1920 | ATTRIBUTED | Andrews names seven 1898 organizers and reports $50 each in capital stock, business beginning April 1, 1899, and a later offer to return $50 plus interest for releases. Seven times $50 equals $350 as Institute Analysis of reported subscriptions. No founding cash book, bank deposit, subscription instrument or executed release was inspected. The organizer list differs from the eight names on the charter’s first page. |
| Annual premium-income table BEHI-P014-S10 | Andrews, pp. 105, 108–109; PDF pp. 127, 130–131 | 1899–1919; published 1920 | VERIFIED | The inspected printed table gives $840 for 1899, $358,311 for 1913, $404,766 for 1914, $819,771 for 1918 and $1,224,541 for 1919. These are rounded annual premium figures in a publication. Duke’s modern exhibit places more than $1 million in 1918; the conflict is preserved pending original returns. Premiums are not profit or Merrick’s personal income. |
| Regulatory examination — reproduced extracts BEHI-P014-S11 | Andrews, pp. 223–227; PDF pp. 253–257 | April 21–24, 1920; condition December 31, 1919 | VERIFIED | The inspected book prints report extracts signed in print by E. T. Burr and S. F. Campbell, approved by J. R. Young April 24. They report a 1913 charter amendment and April 7, 1919 name amendment, test checks for 1916–1918 and a detailed 1919 check through agents’ reports, agency registers, cash journal and checks. This is an inspected printed reproduction; the original signed report and underlying books were not inspected. Andrews’s narrative May 12 announcement is a different event from the reported April 7 legal change. |
| 1919 financial statement — reproduced appendix BEHI-P014-S12 | Andrews, pp. 228–229; PDF pp. 258–259 | December 31, 1919; published 1920 | VERIFIED | The visually inspected statement prints premiums $1,224,541.69; rents/interest $42,497.93; opening balance $395,487.66; gross assets $774,935.32; admitted assets $755,744.26; liabilities $639,278.42; surplus $116,465.84; policyholder payments $401,240.66 and commissions $445,577.87. Its $1,662,527.28 total includes the opening balance and is not annual revenue. Premiums plus rents/interest equal $1,267,039.62 (Institute Analysis). The liabilities-plus-surplus total is printed $755,744.25, one cent below the assets-side total. No silent correction is made. This year-end account includes months after Merrick’s August death. |
| Duke exhibit — founders and growth BEHI-P014-S14 | Soul & Service: early years and founder page | Modern exhibit; inspected October 4, 2026 | ATTRIBUTED | Duke describes Merrick’s enslaved origins, barbering and insurance leadership and joint Duke/NCCU archival custody. The early-years exhibit states premium income exceeded $1 million by 1918, conflicting with the 1920 table’s $819,771. The 1921 six-story building belongs to the successor period, after Merrick’s death. The exhibit is a research guide, not a substitute for annual returns. |
| Estate and deed reconciliation — acquisition register BEHI-P014-S15 | Durham probate and Register of Deeds research targets; earlier correspondence leads | 1881–1925 deeds; 1919/1939 estates | ATTRIBUTED | Durham County Register of Deeds supplied an eleven-page historical index PDF, which BEHI inspected: mortgage indexes on PDF pp. 1–4 and deed indexes on pp. 5–11, covering the requested 1881–1925 period. These are index locators, not the underlying deeds or mortgages, and do not establish transaction terms or an ownership chain. Original probate files also remain unrecovered: Merrick’s 1919 will, inventory, accounts and business interests, and Martha Merrick’s 1939 Will File No. 1441, identified in the State Archives published index; the original will and related estate-administration file remain uninspected. The 1901 Parrish sheriff-sale, 1887 cottage, 1911 Carr financing, Fidelity/Home Savings loans and $550 rent lead still require instrument-by-instrument reconciliation. |
Claim Review & Corrections
| CLAIM / ASSERTION | HISTORICAL CLARIFICATION & CORRECTION | CLAIM STATUS | RECEIPT |
|---|---|---|---|
|
◆
Merrick — Charter names eight incorporators
“The inspected first page of the 1899 act names Merrick among eight incorporators.”
|
The first page is incomplete. Its list differs from seven earlier organizers and does not prove paid subscriptions or ownership shares. |
Verified | |
|
◆
Merrick — Merrick’s company role
“The 1914 anniversary spread identifies Merrick as founder and president, Moore as secretary-treasurer and Spaulding as vice-president/general manager.”
|
The spread verifies printed executive roles. It is a company publication and does not establish all corporate ownership or individual contribution. |
Verified | |
|
◆
Merrick — Reported founding capital
“Andrews reports seven organizers subscribing $50 each.”
|
The calculated $350 is Institute Analysis of attributed inputs; cash payment, a deposit and executed subscription instruments were not inspected. |
Attributed | |
|
◆
Merrick — Premium-income dating
“The 1920 table prints $819,771 in 1918 and $1,224,541 in 1919.”
|
Duke’s modern exhibit places the million-dollar threshold in 1918. The conflicting claim remains disputed until original returns are inspected. |
Disputed | |
|
◆
Merrick — Anniversary chart’s final amount
“The April 1914 anniversary chart ends at $358,311.”
|
Andrews assigns $358,311 to 1913 and $404,766 to 1914. Publication date is not proof of a full-calendar-year 1914 amount. |
Verified | |
|
◆
Merrick — 1919 receipts versus opening balance
“The statement prints premiums of $1,224,541.69, rents/interest of $42,497.93 and a $395,487.66 opening balance.”
|
The $1,662,527.28 total includes carried-forward money. Premiums plus rents/interest equal $1,267,039.62 (Institute Analysis), not profit or Merrick’s personal income. |
Verified | |
|
◆
Merrick — Company assets versus personal estate
“The appendix prints admitted assets $755,744.26 and surplus $116,465.84.”
|
These are company amounts and cover a year ending after Merrick’s death. The opposite-side total is one cent lower. No personal net-worth estimate is supported without estate and ownership records. |
Verified | |
|
◆
Merrick — Regulatory examination and controls
“The printed examination describes agents’ reports, registers, cash journals, bank endorsement controls and a detailed 1919 receipts/disbursements check.”
|
The inspected source is the book’s reproduced extract, not the original signed report or the underlying accounting books. |
Verified | |
|
◆
Merrick — 1919 legal change and announcement
“The reproduced examination dates the name amendment April 7, 1919; Andrews’s narrative describes an officers’ announcement May 12.”
|
Legal amendment and announcement are distinct events. Both precede Merrick’s August death; the original amendment is still needed. |
Verified | |
|
◆
Merrick — Separate enterprises and financing
“Royal Knights, barbering, property, product and allied business accounts are reported in Andrews.”
|
These are distinct entities and retrospective accounts. Keep the $10,000 South Carolina deposit separate from the $6,000 Fidelity-loan lead and verify each original instrument. |
Attributed |
Legacy
TAKEAWAY: Merrick helped establish an institution that continued under later leaders. Subsequent buildings, growth, and honors should be credited to their own periods.
LEGACY
Merrick helped establish an insurance institution that continued under Moore, Spaulding and later leadership. His legacy belongs both to Durham’s business history and to the larger history of Black financial organization. Later buildings, company growth and public honors should be credited to their own periods.
An institution carried forward by other people
A founder’s initiative
Merrick’s significance includes bringing collaborators together and serving as founding president. His record belongs within the wider history of Black financial organization in Durham.
A succession of leaders
Moore and Spaulding were already named in executive roles during his lifetime. Later growth should preserve the work of successor leadership, agents, employees, and policyholders.
A business community
Reported bank, retail, property, and fraternal connections place insurance within a broader local economy. Their shared setting does not prove one owner or a consolidated account.
Public memory & surviving evidence
Later headquarters, commemoration, and archival preservation extend the story beyond 1919. They show the institution’s historical reach while remaining distinct from lifetime transactions.
Evidence register: BEHI-P014-S02, S09, S13–S14. BEHI interpretation based on the anniversary spread, attributed enterprise accounts, NC DNCR biography, and Duke exhibit. The 1921 headquarters is successor-period history; the 1943 ship honor is commemoration, not a measure of company assets.
CHANNELS OF LEGACY
Continuity beyond its founding president.
Insurance within an allied business community.
Historical recognition and archival preservation.
THE RECORD & ITS LIMITS
The 1921 six-story headquarters was completed after his death. Duke’s archive also documents later employees and operations, extending the story beyond the founding generation.
Banking, drugstore, property and fraternal ventures show reported collaboration. Their particular financing and ownership histories still require original records.
NC DNCR dates his reinterment to 1926 and the Liberty ship launch to July 11, 1943. These later honors document commemoration, not lifetime transactions.
READING THE EVIDENCE
A lasting institution can carry a founder’s influence while also embodying the labor and decisions of subsequent generations. Merrick’s legacy is strongest when those contributions remain visible.
EVIDENCE & CONTEXT
| Source | Description | Date | Evidence Classification | Notes |
|---|---|---|---|---|
| Bank, drugstore and allied enterprise accounts BEHI-P014-S09 | Andrews, pp. 54–63 | 1907–1908; published 1920 | ATTRIBUTED | Andrews reproduces a July 29, 1907 bank-organizing notice and describes Bull City Drug’s 1908 organizers and later sale of stores. These are accounts of collaboration. Minutes, stock ownership, bank statements, drugstore sale contracts and manufacturing loss records were not inspected. Collective participation does not establish Merrick’s exclusive ownership. |
| Regulatory examination — reproduced extracts BEHI-P014-S11 | Andrews, pp. 223–227; PDF pp. 253–257 | April 21–24, 1920; condition December 31, 1919 | VERIFIED | The inspected book prints report extracts signed in print by E. T. Burr and S. F. Campbell, approved by J. R. Young April 24. They report a 1913 charter amendment and April 7, 1919 name amendment, test checks for 1916–1918 and a detailed 1919 check through agents’ reports, agency registers, cash journal and checks. This is an inspected printed reproduction; the original signed report and underlying books were not inspected. Andrews’s narrative May 12 announcement is a different event from the reported April 7 legal change. |
| Institutional biography and historical marker BEHI-P014-S13 | NC DNCR, John Merrick 1859–1919 (G-109) | 2023; inspected October 4, 2026 | ATTRIBUTED | The state historical account describes his Durham move in 1880, the October 20, 1898 organizing meeting, February 1899 incorporation, subsequent Moore presidency, 1926 reinterment and July 11, 1943 launch of the Liberty ship John Merrick. These are institutional historical accounts. They do not establish personal net worth, an inspected estate inventory or present-day company operations. |
| Duke exhibit — founders and growth BEHI-P014-S14 | Soul & Service: early years and founder page | Modern exhibit; inspected October 4, 2026 | ATTRIBUTED | Duke describes Merrick’s enslaved origins, barbering and insurance leadership and joint Duke/NCCU archival custody. The early-years exhibit states premium income exceeded $1 million by 1918, conflicting with the 1920 table’s $819,771. The 1921 six-story building belongs to the successor period, after Merrick’s death. The exhibit is a research guide, not a substitute for annual returns. |
Company Records
TAKEAWAY: The register distinguishes original instruments, inspected reproductions, attributed accounts, and acquisition targets. A category’s presence does not establish complete surviving records.
COMPANY RECORDS
The eight permanent categories below retain inspected reproductions, attributed business accounts and unresolved acquisition targets. The company register is linked to native historical records. Each record states whether the original instrument, a reproduction or only an account was inspected.
How the reproduced examination followed the money
Agent reports
The printed examination describes checking reports from the collection network. These records could tie premiums to reporting periods and named agents.
Agency registers
Registers offered another route through the transactions. Recovering them would allow comparison with the reports rather than relying only on a summarized total.
Cash journal & checks
The reproduced account describes examination of journal entries and checks. Original books and instruments could establish dates, counterparties, and settlement.
Annual return & condition
The examination concerns the company’s December 31, 1919 condition. Its printed findings are inspectable evidence; the original signed report remains an acquisition target.
Evidence register: BEHI-P014-S11. Andrews, John Merrick: A Biographical Sketch (1920), pp. 223–227. Diagram of record types described in the reproduced examination, not a claim that BEHI has independently checked the underlying books.
The eight categories below remain intact. Formation and ownership require full acts, amendments, subscriptions, and releases; Financial and Ledgers & Accounts require original returns and books; property and personal capital require deeds, mortgage releases, and probate. Each line of inquiry should be reconciled separately before drawing a consolidated conclusion.
Charter and organizing evidence.
Shops, products, policies and allied businesses.
Financial statement and reported internal controls.
THE RECORD & ITS LIMITS
A missing patent, ledger or contract does not remove its category. The category remains visible with the precise acquisition gap.
North Carolina Mutual, Royal Knights, John Merrick & Co., shops, property and allied ventures have separate records and obligations.
The Duke/NCCU collection is an archival route. A collection reference or request does not establish that a particular original has been supplied or reviewed.
READING THE EVIDENCE
The register provides an audit trail from a narrative claim to its evidence and its limits. Records classified Verified here verify the stated contents of inspected reproductions, rather than certifying every underlying transaction.
INCORPORATION RECORDS
| Source | Description | Date | Evidence Classification | Notes |
|---|---|---|---|---|
| Incorporation act — first-page reproduction BEHI-P014-S01 | Private Laws of North Carolina, 1899, chapter 156; reproduced first page | 1899 | VERIFIED | The inspected first page names John Merrick, A. M. Moore, J. E. Shepard, W. G. Pearson, D. T. Watson, T. O. Fuller, E. A. Johnson and W. C. Bruce. It creates the North Carolina Mutual and Provident Association for sixty years and describes death, sickness, accident and burial benefits. The reproduction ends during section 2. The remaining act, ratification date and later amendments were not inspected. Named incorporators are not automatically a cash subscription ledger. |
| Insurance organizers and reported subscriptions BEHI-P014-S07 | Andrews, pp. 64–66 | 1898–1899; published 1920 | ATTRIBUTED | Andrews names seven 1898 organizers and reports $50 each in capital stock, business beginning April 1, 1899, and a later offer to return $50 plus interest for releases. Seven times $50 equals $350 as Institute Analysis of reported subscriptions. No founding cash book, bank deposit, subscription instrument or executed release was inspected. The organizer list differs from the eight names on the charter’s first page. |
| Regulatory examination — reproduced extracts BEHI-P014-S11 | Andrews, pp. 223–227; PDF pp. 253–257 | April 21–24, 1920; condition December 31, 1919 | VERIFIED | The inspected book prints report extracts signed in print by E. T. Burr and S. F. Campbell, approved by J. R. Young April 24. They report a 1913 charter amendment and April 7, 1919 name amendment, test checks for 1916–1918 and a detailed 1919 check through agents’ reports, agency registers, cash journal and checks. This is an inspected printed reproduction; the original signed report and underlying books were not inspected. Andrews’s narrative May 12 announcement is a different event from the reported April 7 legal change. |
| Company minutes and capital reconciliation — acquisition register BEHI-P014-S16 | Duke/NCCU North Carolina Mutual archives; targeted minutes and capital records | 1898–1908 research targets | ATTRIBUTED | Obtain complete 1899 act, amendments, 1898–1903 minutes, subscriptions and first financial records. Earlier leads identify June 1, 8, 9 and 12, 1905, and February 17–18, 1908 minutes; each date remains a target, not a verified meeting entry. Reconcile $6,000 Fidelity-loan collateral separately from the biography’s $10,000 South Carolina deposit. No requested file is labeled inspected solely because an inquiry was sent. |
FINANCIAL RECORDS
| Source | Description | Date | Evidence Classification | Notes |
|---|---|---|---|---|
| Fifteenth-anniversary premium-income spread BEHI-P014-S02 | Duke exhibit item 8537; anniversary spread, 1899–1914 | April 1, 1914 | VERIFIED | The inspected company publication labels John Merrick founder and president, A. M. Moore secretary-treasurer and C. C. Spaulding vice-president/general manager. Its premium chart ends at $358,311. Andrews’s annual table assigns that figure to 1913, and $404,766 to 1914. The anniversary date is not proof that the last chart figure covers calendar 1914. Published company claims are not an independent audit or personal wealth. |
| Parrish Street offices and South Carolina deposit BEHI-P014-S08 | Andrews, pp. 87–89 | 1904–1905; published 1920 | ATTRIBUTED | The biography reports an $8,000 Parrish Street site and office project, and a $10,000 South Carolina deposit supported by Merrick and Moore mortgaging property and obtaining a Fidelity draft. This is not a recovered mortgage or bank entry. Earlier $6,000 Fidelity-loan and $550 monthly-rent leads remain separate unresolved transactions; they must not be substituted for the regulatory deposit. |
| Annual premium-income table BEHI-P014-S10 | Andrews, pp. 105, 108–109; PDF pp. 127, 130–131 | 1899–1919; published 1920 | VERIFIED | The inspected printed table gives $840 for 1899, $358,311 for 1913, $404,766 for 1914, $819,771 for 1918 and $1,224,541 for 1919. These are rounded annual premium figures in a publication. Duke’s modern exhibit places more than $1 million in 1918; the conflict is preserved pending original returns. Premiums are not profit or Merrick’s personal income. |
| 1919 financial statement — reproduced appendix BEHI-P014-S12 | Andrews, pp. 228–229; PDF pp. 258–259 | December 31, 1919; published 1920 | VERIFIED | The visually inspected statement prints premiums $1,224,541.69; rents/interest $42,497.93; opening balance $395,487.66; gross assets $774,935.32; admitted assets $755,744.26; liabilities $639,278.42; surplus $116,465.84; policyholder payments $401,240.66 and commissions $445,577.87. Its $1,662,527.28 total includes the opening balance and is not annual revenue. Premiums plus rents/interest equal $1,267,039.62 (Institute Analysis). The liabilities-plus-surplus total is printed $755,744.25, one cent below the assets-side total. No silent correction is made. This year-end account includes months after Merrick’s August death. |
OPERATIONAL RECORDS
| Source | Description | Date | Evidence Classification | Notes |
|---|---|---|---|---|
| Barbering, shops and household real estate BEHI-P014-S04 | Andrews, pp. 31–34 | 1880–1892; published 1920 | ATTRIBUTED | John Wright’s retrospective account describes their Durham shop partnership and his 1892 sale to Merrick. Andrews reports three shops serving white customers, two serving Black customers, rental-house activity and an 1887 Fayetteville Street cottage. Original partnership agreements, sale instruments, payroll and property deeds were not recovered. Earlier 1887 and 1889–90 directory leads remain acquisition targets. |
| Dandruff preparation and advertising BEHI-P014-S05 | Andrews, pp. 35–36; advertisements copied from a notebook | About 1890; published 1920 | ATTRIBUTED | Andrews reproduces promotional copy for John Merrick & Co., 104 West Main Street, with a $1 bottle price. He says the notebook was found after Merrick’s death. This supports an attributed trade-name and advertising account; efficacy, patent ownership, trademark registration, sales volume and profit remain unverified. |
| Royal Knights of King David acquisition BEHI-P014-S06 | Andrews, pp. 43–45; W. G. Pearson’s account | September 24, 1883; published 1920 | ATTRIBUTED | The retrospective account identifies Merrick, John Wright, W. A. Day, J. D. Morgan and T. J. Jones in the acquisition from Reverend Morris. Royal Knights was a separate fraternal assessment organization. Its experience is relevant context, but must not be represented as North Carolina Mutual’s 1899 incorporation or merged cash account. |
| Bank, drugstore and allied enterprise accounts BEHI-P014-S09 | Andrews, pp. 54–63 | 1907–1908; published 1920 | ATTRIBUTED | Andrews reproduces a July 29, 1907 bank-organizing notice and describes Bull City Drug’s 1908 organizers and later sale of stores. These are accounts of collaboration. Minutes, stock ownership, bank statements, drugstore sale contracts and manufacturing loss records were not inspected. Collective participation does not establish Merrick’s exclusive ownership. |
CONTRACTS & TRANSACTIONS
| Source | Description | Date | Evidence Classification | Notes |
|---|---|---|---|---|
| Barbering, shops and household real estate BEHI-P014-S04 | Andrews, pp. 31–34 | 1880–1892; published 1920 | ATTRIBUTED | John Wright’s retrospective account describes their Durham shop partnership and his 1892 sale to Merrick. Andrews reports three shops serving white customers, two serving Black customers, rental-house activity and an 1887 Fayetteville Street cottage. Original partnership agreements, sale instruments, payroll and property deeds were not recovered. Earlier 1887 and 1889–90 directory leads remain acquisition targets. |
| Royal Knights of King David acquisition BEHI-P014-S06 | Andrews, pp. 43–45; W. G. Pearson’s account | September 24, 1883; published 1920 | ATTRIBUTED | The retrospective account identifies Merrick, John Wright, W. A. Day, J. D. Morgan and T. J. Jones in the acquisition from Reverend Morris. Royal Knights was a separate fraternal assessment organization. Its experience is relevant context, but must not be represented as North Carolina Mutual’s 1899 incorporation or merged cash account. |
| Parrish Street offices and South Carolina deposit BEHI-P014-S08 | Andrews, pp. 87–89 | 1904–1905; published 1920 | ATTRIBUTED | The biography reports an $8,000 Parrish Street site and office project, and a $10,000 South Carolina deposit supported by Merrick and Moore mortgaging property and obtaining a Fidelity draft. This is not a recovered mortgage or bank entry. Earlier $6,000 Fidelity-loan and $550 monthly-rent leads remain separate unresolved transactions; they must not be substituted for the regulatory deposit. |
| Bank, drugstore and allied enterprise accounts BEHI-P014-S09 | Andrews, pp. 54–63 | 1907–1908; published 1920 | ATTRIBUTED | Andrews reproduces a July 29, 1907 bank-organizing notice and describes Bull City Drug’s 1908 organizers and later sale of stores. These are accounts of collaboration. Minutes, stock ownership, bank statements, drugstore sale contracts and manufacturing loss records were not inspected. Collective participation does not establish Merrick’s exclusive ownership. |
| Estate and deed reconciliation — acquisition register BEHI-P014-S15 | Durham probate and Register of Deeds research targets; earlier correspondence leads | 1881–1925 deeds; 1919/1939 estates | ATTRIBUTED | Durham County Register of Deeds supplied an eleven-page historical index PDF, which BEHI inspected: mortgage indexes on PDF pp. 1–4 and deed indexes on pp. 5–11, covering the requested 1881–1925 period. These are index locators, not the underlying deeds or mortgages, and do not establish transaction terms or an ownership chain. Original probate files also remain unrecovered: Merrick’s 1919 will, inventory, accounts and business interests, and Martha Merrick’s 1939 Will File No. 1441, identified in the State Archives published index; the original will and related estate-administration file remain uninspected. The 1901 Parrish sheriff-sale, 1887 cottage, 1911 Carr financing, Fidelity/Home Savings loans and $550 rent lead still require instrument-by-instrument reconciliation. |
| Company minutes and capital reconciliation — acquisition register BEHI-P014-S16 | Duke/NCCU North Carolina Mutual archives; targeted minutes and capital records | 1898–1908 research targets | ATTRIBUTED | Obtain complete 1899 act, amendments, 1898–1903 minutes, subscriptions and first financial records. Earlier leads identify June 1, 8, 9 and 12, 1905, and February 17–18, 1908 minutes; each date remains a target, not a verified meeting entry. Reconcile $6,000 Fidelity-loan collateral separately from the biography’s $10,000 South Carolina deposit. No requested file is labeled inspected solely because an inquiry was sent. |
LEGAL & REGULATORY RECORDS
| Source | Description | Date | Evidence Classification | Notes |
|---|---|---|---|---|
| Incorporation act — first-page reproduction BEHI-P014-S01 | Private Laws of North Carolina, 1899, chapter 156; reproduced first page | 1899 | VERIFIED | The inspected first page names John Merrick, A. M. Moore, J. E. Shepard, W. G. Pearson, D. T. Watson, T. O. Fuller, E. A. Johnson and W. C. Bruce. It creates the North Carolina Mutual and Provident Association for sixty years and describes death, sickness, accident and burial benefits. The reproduction ends during section 2. The remaining act, ratification date and later amendments were not inspected. Named incorporators are not automatically a cash subscription ledger. |
| Regulatory examination — reproduced extracts BEHI-P014-S11 | Andrews, pp. 223–227; PDF pp. 253–257 | April 21–24, 1920; condition December 31, 1919 | VERIFIED | The inspected book prints report extracts signed in print by E. T. Burr and S. F. Campbell, approved by J. R. Young April 24. They report a 1913 charter amendment and April 7, 1919 name amendment, test checks for 1916–1918 and a detailed 1919 check through agents’ reports, agency registers, cash journal and checks. This is an inspected printed reproduction; the original signed report and underlying books were not inspected. Andrews’s narrative May 12 announcement is a different event from the reported April 7 legal change. |
| Estate and deed reconciliation — acquisition register BEHI-P014-S15 | Durham probate and Register of Deeds research targets; earlier correspondence leads | 1881–1925 deeds; 1919/1939 estates | ATTRIBUTED | Durham County Register of Deeds supplied an eleven-page historical index PDF, which BEHI inspected: mortgage indexes on PDF pp. 1–4 and deed indexes on pp. 5–11, covering the requested 1881–1925 period. These are index locators, not the underlying deeds or mortgages, and do not establish transaction terms or an ownership chain. Original probate files also remain unrecovered: Merrick’s 1919 will, inventory, accounts and business interests, and Martha Merrick’s 1939 Will File No. 1441, identified in the State Archives published index; the original will and related estate-administration file remain uninspected. The 1901 Parrish sheriff-sale, 1887 cottage, 1911 Carr financing, Fidelity/Home Savings loans and $550 rent lead still require instrument-by-instrument reconciliation. |
| Company minutes and capital reconciliation — acquisition register BEHI-P014-S16 | Duke/NCCU North Carolina Mutual archives; targeted minutes and capital records | 1898–1908 research targets | ATTRIBUTED | Obtain complete 1899 act, amendments, 1898–1903 minutes, subscriptions and first financial records. Earlier leads identify June 1, 8, 9 and 12, 1905, and February 17–18, 1908 minutes; each date remains a target, not a verified meeting entry. Reconcile $6,000 Fidelity-loan collateral separately from the biography’s $10,000 South Carolina deposit. No requested file is labeled inspected solely because an inquiry was sent. |
INTELLECTUAL PROPERTY RECORDS
| Source | Description | Date | Evidence Classification | Notes |
|---|---|---|---|---|
| Dandruff preparation and advertising BEHI-P014-S05 | Andrews, pp. 35–36; advertisements copied from a notebook | About 1890; published 1920 | ATTRIBUTED | Andrews reproduces promotional copy for John Merrick & Co., 104 West Main Street, with a $1 bottle price. He says the notebook was found after Merrick’s death. This supports an attributed trade-name and advertising account; efficacy, patent ownership, trademark registration, sales volume and profit remain unverified. |
No original patent, trademark registration or trade-name filing was recovered. The available product advertisement is an attributed account reproduced in Andrews.
LEDGERS & ACCOUNTS
| Source | Description | Date | Evidence Classification | Notes |
|---|---|---|---|---|
| Regulatory examination — reproduced extracts BEHI-P014-S11 | Andrews, pp. 223–227; PDF pp. 253–257 | April 21–24, 1920; condition December 31, 1919 | VERIFIED | The inspected book prints report extracts signed in print by E. T. Burr and S. F. Campbell, approved by J. R. Young April 24. They report a 1913 charter amendment and April 7, 1919 name amendment, test checks for 1916–1918 and a detailed 1919 check through agents’ reports, agency registers, cash journal and checks. This is an inspected printed reproduction; the original signed report and underlying books were not inspected. Andrews’s narrative May 12 announcement is a different event from the reported April 7 legal change. |
| 1919 financial statement — reproduced appendix BEHI-P014-S12 | Andrews, pp. 228–229; PDF pp. 258–259 | December 31, 1919; published 1920 | VERIFIED | The visually inspected statement prints premiums $1,224,541.69; rents/interest $42,497.93; opening balance $395,487.66; gross assets $774,935.32; admitted assets $755,744.26; liabilities $639,278.42; surplus $116,465.84; policyholder payments $401,240.66 and commissions $445,577.87. Its $1,662,527.28 total includes the opening balance and is not annual revenue. Premiums plus rents/interest equal $1,267,039.62 (Institute Analysis). The liabilities-plus-surplus total is printed $755,744.25, one cent below the assets-side total. No silent correction is made. This year-end account includes months after Merrick’s August death. |
| Company minutes and capital reconciliation — acquisition register BEHI-P014-S16 | Duke/NCCU North Carolina Mutual archives; targeted minutes and capital records | 1898–1908 research targets | ATTRIBUTED | Obtain complete 1899 act, amendments, 1898–1903 minutes, subscriptions and first financial records. Earlier leads identify June 1, 8, 9 and 12, 1905, and February 17–18, 1908 minutes; each date remains a target, not a verified meeting entry. Reconcile $6,000 Fidelity-loan collateral separately from the biography’s $10,000 South Carolina deposit. No requested file is labeled inspected solely because an inquiry was sent. |
REPORTS & CORRESPONDENCE
| Source | Description | Date | Evidence Classification | Notes |
|---|---|---|---|---|
| Fifteenth-anniversary premium-income spread BEHI-P014-S02 | Duke exhibit item 8537; anniversary spread, 1899–1914 | April 1, 1914 | VERIFIED | The inspected company publication labels John Merrick founder and president, A. M. Moore secretary-treasurer and C. C. Spaulding vice-president/general manager. Its premium chart ends at $358,311. Andrews’s annual table assigns that figure to 1913, and $404,766 to 1914. The anniversary date is not proof that the last chart figure covers calendar 1914. Published company claims are not an independent audit or personal wealth. |
| 1920 memorial biography — source and interpretation BEHI-P014-S03 | R. McCants Andrews, John Merrick: A Biographical Sketch, Durham: Seeman Printery; 264-page scan | 1920 | VERIFIED | The book and OCR were recovered. Relevant business passages were reviewed; selected financial, regulatory and portrait pages were inspected visually. This is a memorial biography, not a complete original business archive. Pages 42–43 acknowledge faulty memory and conflicting accounts. Verification here establishes the inspected publication and its wording, not every narrated event. |
| Annual premium-income table BEHI-P014-S10 | Andrews, pp. 105, 108–109; PDF pp. 127, 130–131 | 1899–1919; published 1920 | VERIFIED | The inspected printed table gives $840 for 1899, $358,311 for 1913, $404,766 for 1914, $819,771 for 1918 and $1,224,541 for 1919. These are rounded annual premium figures in a publication. Duke’s modern exhibit places more than $1 million in 1918; the conflict is preserved pending original returns. Premiums are not profit or Merrick’s personal income. |
| Regulatory examination — reproduced extracts BEHI-P014-S11 | Andrews, pp. 223–227; PDF pp. 253–257 | April 21–24, 1920; condition December 31, 1919 | VERIFIED | The inspected book prints report extracts signed in print by E. T. Burr and S. F. Campbell, approved by J. R. Young April 24. They report a 1913 charter amendment and April 7, 1919 name amendment, test checks for 1916–1918 and a detailed 1919 check through agents’ reports, agency registers, cash journal and checks. This is an inspected printed reproduction; the original signed report and underlying books were not inspected. Andrews’s narrative May 12 announcement is a different event from the reported April 7 legal change. |
| 1919 financial statement — reproduced appendix BEHI-P014-S12 | Andrews, pp. 228–229; PDF pp. 258–259 | December 31, 1919; published 1920 | VERIFIED | The visually inspected statement prints premiums $1,224,541.69; rents/interest $42,497.93; opening balance $395,487.66; gross assets $774,935.32; admitted assets $755,744.26; liabilities $639,278.42; surplus $116,465.84; policyholder payments $401,240.66 and commissions $445,577.87. Its $1,662,527.28 total includes the opening balance and is not annual revenue. Premiums plus rents/interest equal $1,267,039.62 (Institute Analysis). The liabilities-plus-surplus total is printed $755,744.25, one cent below the assets-side total. No silent correction is made. This year-end account includes months after Merrick’s August death. |
| Institutional biography and historical marker BEHI-P014-S13 | NC DNCR, John Merrick 1859–1919 (G-109) | 2023; inspected October 4, 2026 | ATTRIBUTED | The state historical account describes his Durham move in 1880, the October 20, 1898 organizing meeting, February 1899 incorporation, subsequent Moore presidency, 1926 reinterment and July 11, 1943 launch of the Liberty ship John Merrick. These are institutional historical accounts. They do not establish personal net worth, an inspected estate inventory or present-day company operations. |
| Duke exhibit — founders and growth BEHI-P014-S14 | Soul & Service: early years and founder page | Modern exhibit; inspected October 4, 2026 | ATTRIBUTED | Duke describes Merrick’s enslaved origins, barbering and insurance leadership and joint Duke/NCCU archival custody. The early-years exhibit states premium income exceeded $1 million by 1918, conflicting with the 1920 table’s $819,771. The 1921 six-story building belongs to the successor period, after Merrick’s death. The exhibit is a research guide, not a substitute for annual returns. |
| Company minutes and capital reconciliation — acquisition register BEHI-P014-S16 | Duke/NCCU North Carolina Mutual archives; targeted minutes and capital records | 1898–1908 research targets | ATTRIBUTED | Obtain complete 1899 act, amendments, 1898–1903 minutes, subscriptions and first financial records. Earlier leads identify June 1, 8, 9 and 12, 1905, and February 17–18, 1908 minutes; each date remains a target, not a verified meeting entry. Reconcile $6,000 Fidelity-loan collateral separately from the biography’s $10,000 South Carolina deposit. No requested file is labeled inspected solely because an inquiry was sent. |
ARCHIVAL CERTIFICATION & PUBLIC RECORD INTEGRITY
All company records presented in this repository have been cataloged according to the BEHI Company Records Classification System. Documents marked as Primary Sources are drawn from certified state and county archives, corporate filings, and recognized institutional repositories. Where physical scans are currently in the acquisition pipeline, verified archival metadata, source citations, and holding locators are provided to facilitate scholarly research.
| Document & ID | Evidence Type | Date | Description & Location | Source Repository | Action |
|---|---|---|---|---|---|
|
Merrick — Incorporation act — first-page reproduction
BEHI-P014-S01
John Merrick / North Carolina Mutual and allied enterprises
|
Government
Incorporation
|
1899 |
The inspected first page names John Merrick, A. M. Moore, J. E. Shepard, W. G. Pearson, D. T. Watson, T. O. Fuller, E. A. Johnson and W. ...
|
Private Laws of North Carolina, 1899, chapter 156; reproduced first page
|
|
|
Merrick — Fifteenth-anniversary premium-income spread
BEHI-P014-S02
John Merrick / North Carolina Mutual and allied enterprises
|
Corporate / Financial
Advertising & Marketing · Annual Reports · Financial Statements
|
April 1, 1914 |
The inspected company publication labels John Merrick founder and president, A. M. Moore secretary-treasurer and C. C. Spaulding vice-pre...
|
Duke exhibit item 8537; anniversary spread, 1899–1914
|
|
|
Merrick — 1920 memorial biography — source and interpretation
BEHI-P014-S03
John Merrick / North Carolina Mutual and allied enterprises
|
Contemporary Publication
Reports & Correspondence
|
1920 |
The book and OCR were recovered. Relevant business passages were reviewed; selected financial, regulatory and portrait pages were inspect...
|
R. McCants Andrews, John Merrick: A Biographical Sketch, Durham: Seeman Printery; 264-page scan
|
|
|
Merrick — Barbering, shops and household real estate
BEHI-P014-S04
John Merrick / North Carolina Mutual and allied enterprises
|
Contemporary Publication
Business Operations · Property Records · Purchase & Sale Agreements
|
1880–1892; published 1920 |
John Wright’s retrospective account describes their Durham shop partnership and his 1892 sale to Merrick. Andrews reports three shops ser...
|
Andrews, pp. 31–34
|
|
|
Merrick — Dandruff preparation and advertising
BEHI-P014-S05
John Merrick / North Carolina Mutual and allied enterprises
|
Contemporary Publication
Advertising & Marketing · Trademarks & Trade Names
|
About 1890; published 1920 |
Andrews reproduces promotional copy for John Merrick & Co., 104 West Main Street, with a $1 bottle price. He says the notebook was fo...
|
Andrews, pp. 35–36; advertisements copied from a notebook
|
|
|
Merrick — Royal Knights of King David acquisition
BEHI-P014-S06
John Merrick / North Carolina Mutual and allied enterprises
|
Contemporary Publication
Insurance · Purchase & Sale Agreements
|
September 24, 1883; published 1920 |
The retrospective account identifies Merrick, John Wright, W. A. Day, J. D. Morgan and T. J. Jones in the acquisition from Reverend Morri...
|
Andrews, pp. 43–45; W. G. Pearson’s account
|
|
|
Merrick — Insurance organizers and reported subscriptions
BEHI-P014-S07
John Merrick / North Carolina Mutual and allied enterprises
|
Contemporary Publication
Banking Records · Incorporation · Purchase & Sale Agreements
|
1898–1899; published 1920 |
Andrews names seven 1898 organizers and reports $50 each in capital stock, business beginning April 1, 1899, and a later offer to return ...
|
Andrews, pp. 64–66
|
|
|
Merrick — Parrish Street offices and South Carolina deposit
BEHI-P014-S08
John Merrick / North Carolina Mutual and allied enterprises
|
Contemporary Publication
Loans & Credit · Property Records · Regulatory Correspondence
|
1904–1905; published 1920 |
The biography reports an $8,000 Parrish Street site and office project, and a $10,000 South Carolina deposit supported by Merrick and Moo...
|
Andrews, pp. 87–89
|
|
|
Merrick — Bank, drugstore and allied enterprise accounts
BEHI-P014-S09
John Merrick / North Carolina Mutual and allied enterprises
|
Contemporary Publication
Banking Records · Business Operations · Purchase & Sale Agreements
|
1907–1908; published 1920 |
Andrews reproduces a July 29, 1907 bank-organizing notice and describes Bull City Drug’s 1908 organizers and later sale of stores. These ...
|
Andrews, pp. 54–63
|
|
|
Merrick — Annual premium-income table
BEHI-P014-S10
John Merrick / North Carolina Mutual and allied enterprises
|
Corporate / Financial
Annual Reports · Financial Statements
|
1899–1919; published 1920 |
The inspected printed table gives $840 for 1899, $358,311 for 1913, $404,766 for 1914, $819,771 for 1918 and $1,224,541 for 1919. These a...
|
Andrews, pp. 105, 108–109; PDF pp. 127, 130–131
|
|
|
Merrick — Regulatory examination — reproduced extracts
BEHI-P014-S11
John Merrick / North Carolina Mutual and allied enterprises
|
Government
Annual Reports · Bylaws · Cash Books · General Ledgers · Regulatory Correspondence
|
April 21–24, 1920; condition December 31, 1919 |
The inspected book prints report extracts signed in print by E. T. Burr and S. F. Campbell, approved by J. R. Young April 24. They report...
|
Andrews, pp. 223–227; PDF pp. 253–257
|
|
|
Merrick — 1919 financial statement — reproduced appendix
BEHI-P014-S12
John Merrick / North Carolina Mutual and allied enterprises
|
Corporate / Financial
Annual Reports · Financial Statements · General Ledgers
|
December 31, 1919; published 1920 |
The visually inspected statement prints premiums $1,224,541.69; rents/interest $42,497.93; opening balance $395,487.66; gross assets $774...
|
Andrews, pp. 228–229; PDF pp. 258–259
|
|
|
Merrick — Institutional biography and historical marker
BEHI-P014-S13
John Merrick / North Carolina Mutual and allied enterprises
|
Repository Authority
Reports & Correspondence
|
2023; inspected October 4, 2026 |
The state historical account describes his Durham move in 1880, the October 20, 1898 organizing meeting, February 1899 incorporation, sub...
|
NC DNCR, John Merrick 1859–1919 (G-109)
|
|
|
Merrick — Duke exhibit — founders and growth
BEHI-P014-S14
John Merrick / North Carolina Mutual and allied enterprises
|
Repository Authority
Reports & Correspondence
|
Modern exhibit; inspected October 4, 2026 |
Duke describes Merrick’s enslaved origins, barbering and insurance leadership and joint Duke/NCCU archival custody. The early-years exhib...
|
Soul & Service: early years and founder page
|
|
|
Merrick — Estate and deed reconciliation — acquisition register
BEHI-P014-S15
John Merrick / North Carolina Mutual and allied enterprises
|
Institute Analysis
Estate & Testamentary · Property Records
|
1881–1925 deeds; 1919/1939 estates |
Durham County Register of Deeds supplied an eleven-page historical index PDF, which BEHI inspected: mortgage indexes on PDF pp. 1–4 and d...
|
Durham probate and Register of Deeds research targets; earlier correspondence leads
|
|
|
Merrick — Company minutes and capital reconciliation — acquisition register
BEHI-P014-S16
John Merrick / North Carolina Mutual and allied enterprises
|
Institute Analysis
Amendments · Banking Records · Correspondence · Incorporation · Loans & Credit
|
1898–1908 research targets |
Obtain complete 1899 act, amendments, 1898–1903 minutes, subscriptions and first financial records. Earlier leads identify June 1, 8, 9 a...
|
Duke/NCCU North Carolina Mutual archives; targeted minutes and capital records
|
No verified records are currently published in this category.
Receipts
TAKEAWAY: Merrick’s receipts include company reproductions and inspected property indexes. The underlying deeds and mortgages still require examination before transaction terms can be established.
RECEIPTS & EVIDENCE
HOW TO READ THE EVIDENCE
Follow the claim to its source, then read the evidence status and limits. A source may support one narrow fact while leaving a larger conclusion unresolved.
Content condition describes whether the question can currently be answered. Evidence classification describes the support for a documented finding.
- Documented: A finding is presented with its source, evidence classification and limits. Documented does not automatically mean Verified.
- Not yet established: The answer remains unresolved. The entry identifies missing evidence and connects to Research Gaps.
- Not applicable: The measure does not fit the person or enterprise being examined; an explanation must state why. Missing evidence alone never makes a question not applicable.
Shared section headings remain visible. Relevance that is uncertain is treated as Not yet established until resolved.
Evidence labels and source access
- Verified
- The specific fact or record described has been checked against the cited material. Read the limit: an inspected reproduction, index or catalog entry does not mean every underlying document or broader claim has been verified.
- Attributed
- The statement is credited to the named source. Independent confirmation or the underlying original may still be outstanding.
- Disputed
- Sources or interpretations conflict. Read the competing evidence and the unresolved question.
- Estimated
- The figure is an approximation or qualified valuation, not an exact measured total. Read its basis, date and uncertainty.
- Institute Analysis
- BEHI’s interpretation or calculation from identified evidence. It is separate from what the historical source directly states.
Source access: A link may lead to an original scan, a published transcription, a finding aid, or a repository page. Use the source ID, collection, box, folder and page locator where supplied. A catalog listing or repository confirmation is not inspection of the item itself.
Images and permissions: Historical support and reproduction permission are separate questions. Read each image credit and rights note; a source link does not itself grant permission to republish.
Open questions: See Research Gaps & Open Questions below for missing records and unresolved claims.
Receipts connect a specific assertion to its historical record and correction. Inspected charter and company-publication contents, reproduced examination findings and financial figures are separated from retrospective accounts and acquisition targets.
Assertion → record → correction.
Publication contents and original transactions distinguished.
Specific documents still needed.
DOCUMENTS
Research update — October 20 delivery located
Reviewed October 28, 2026: Durham County Register of Deeds correspondence dated October 20 confirms that several deed-copy batches and mortgage images from off-site storage were sent to BEHI. The mortgage delivery includes messages identifying Book 46 page 342, Book 48 pages 408, 434 and 433, and Book 50 page 285 in two parts. These deliveries require attachment-by-attachment inventory and inspection before historical claims are revised. A later county message identifies “Deed Book 48” and “Deed Book 65page269” as two unnecessary pages in the last batch; retain them separately until their exact files are matched. This delivery update does not verify ownership, consideration, financing terms or probate findings.
Merrick deed and mortgage indexes — eleven-page packet
Publication hold — reviewed October 28, 2026. Durham County’s October 12, 2026 delivery establishes the provenance of the eleven-page index PDF. A publication/reuse basis for hosting this exact supplied reproduction has not yet been documented.
Release condition: Document the applicable reuse basis or county confirmation for public website display and full-PDF download, with credit to the Durham County Register of Deeds.
Evidence limit: PDF pages 1–4 are mortgage indexes and pages 5–11 are deed indexes. Index entries are locators and do not establish transaction terms or a complete ownership chain. This publication hold does not change the claim-specific evidence classifications.
Preview: Withheld while the publication hold is unresolved; the description above identifies the supplied material.
Full file: Not publicly released. No download is offered while this hold remains.
Citation: Durham County Register of Deeds, historical deed and mortgage indexes, eleven-page PDF delivered October 12, 2026; mortgage indexes pp. 1–4 and deed indexes pp. 5–11.
Evidence classification: Archival index/register; locator evidence, not the complete underlying instruments.
Rights note: Unresolved reproduction terms; release conditions above remain in force.
Portrait provenance — album date corrected
Repository clarification received November 4, 2026: John G. reports that he pulled the box and confirmed the photo album is 1909; the guide’s folder label of 1910 is incorrect. BEHI’s earlier description of a 1910 album is superseded by this physical-holdings clarification. The album date does not establish when an individual photograph was taken.
Reproduction scope: Duke’s reproduction team scans the entire album rather than a single page, so the title page will be included. An estimate and ordering instructions have been requested if arrangements are not already underway. Payment, completed scanning and delivery have not been confirmed.
Portrait match remains pending: Earlier Duke correspondence associated the photograph discussed in BEHI’s inquiry with the Mutual Album, credited to J. M. Avery, D. B. Green and A. R. Moore, without identifying the photographer. The previously uploaded portrait’s exact match to the album image and its page-level citation remain unconfirmed. The original upload is retained; portrait display remains suspended pending comparison and assessment of reproduction terms. A rights-contact referral or scanning workflow is not publication permission.
Next verification: Inspect the delivered title page, publication details and portrait page; compare the existing upload to that image and record its exact locator before restoring display.
Duke collection locator — preserve the guide’s 1910 label as a catalog discrepancy, not the confirmed album date.
Read the record — examination and financial statement
These pages reproduce the North Carolina Mutual examination report and December 31, 1919 financial statement in R. McCants Andrews, John Merrick: A Biographical Sketch (1920). The examination is dated April 21, 1920. These are printed reproductions, not the original signed report or underlying account books. The company figures are not Merrick’s personal wealth; year-end 1919 includes operations after his death.
North Carolina Mutual examination and statement, 1920 appendix
Readable text — Selected financial extract
Page 223 introduces the examination report dated April 21, 1920, concerning the company’s financial condition at December 31, 1919. Pages 228–229 contain the financial statement.
| Entry | Recorded value |
|---|---|
| Opening balance, January 1, 1919 (p. 228) | $395,487.66 |
| Premiums (p. 228) | $1,224,541.69 |
| Rents, interest and other income (p. 228) | $42,497.93 |
| Total including opening balance (p. 228) | $1,662,527.28 |
| Gross assets (p. 228) | $774,935.32 |
| Assets not admitted (p. 228) | $19,191.06 |
| Admitted assets (p. 228) | $755,744.26 |
| Liabilities (p. 229) | $639,278.42 |
| Unassigned funds / surplus (p. 229) | $116,465.84 |
Selected figures from the printed appendix; labels shortened. The $1,662,527.28 total includes the opening balance and is not annual revenue. This is a published reproduction of company accounts, not Merrick’s personal estate or the signed examination original. Checked against the source images by BEHI, October 28, 2026.
Preview: 3 selected page images; see citation for coverage.
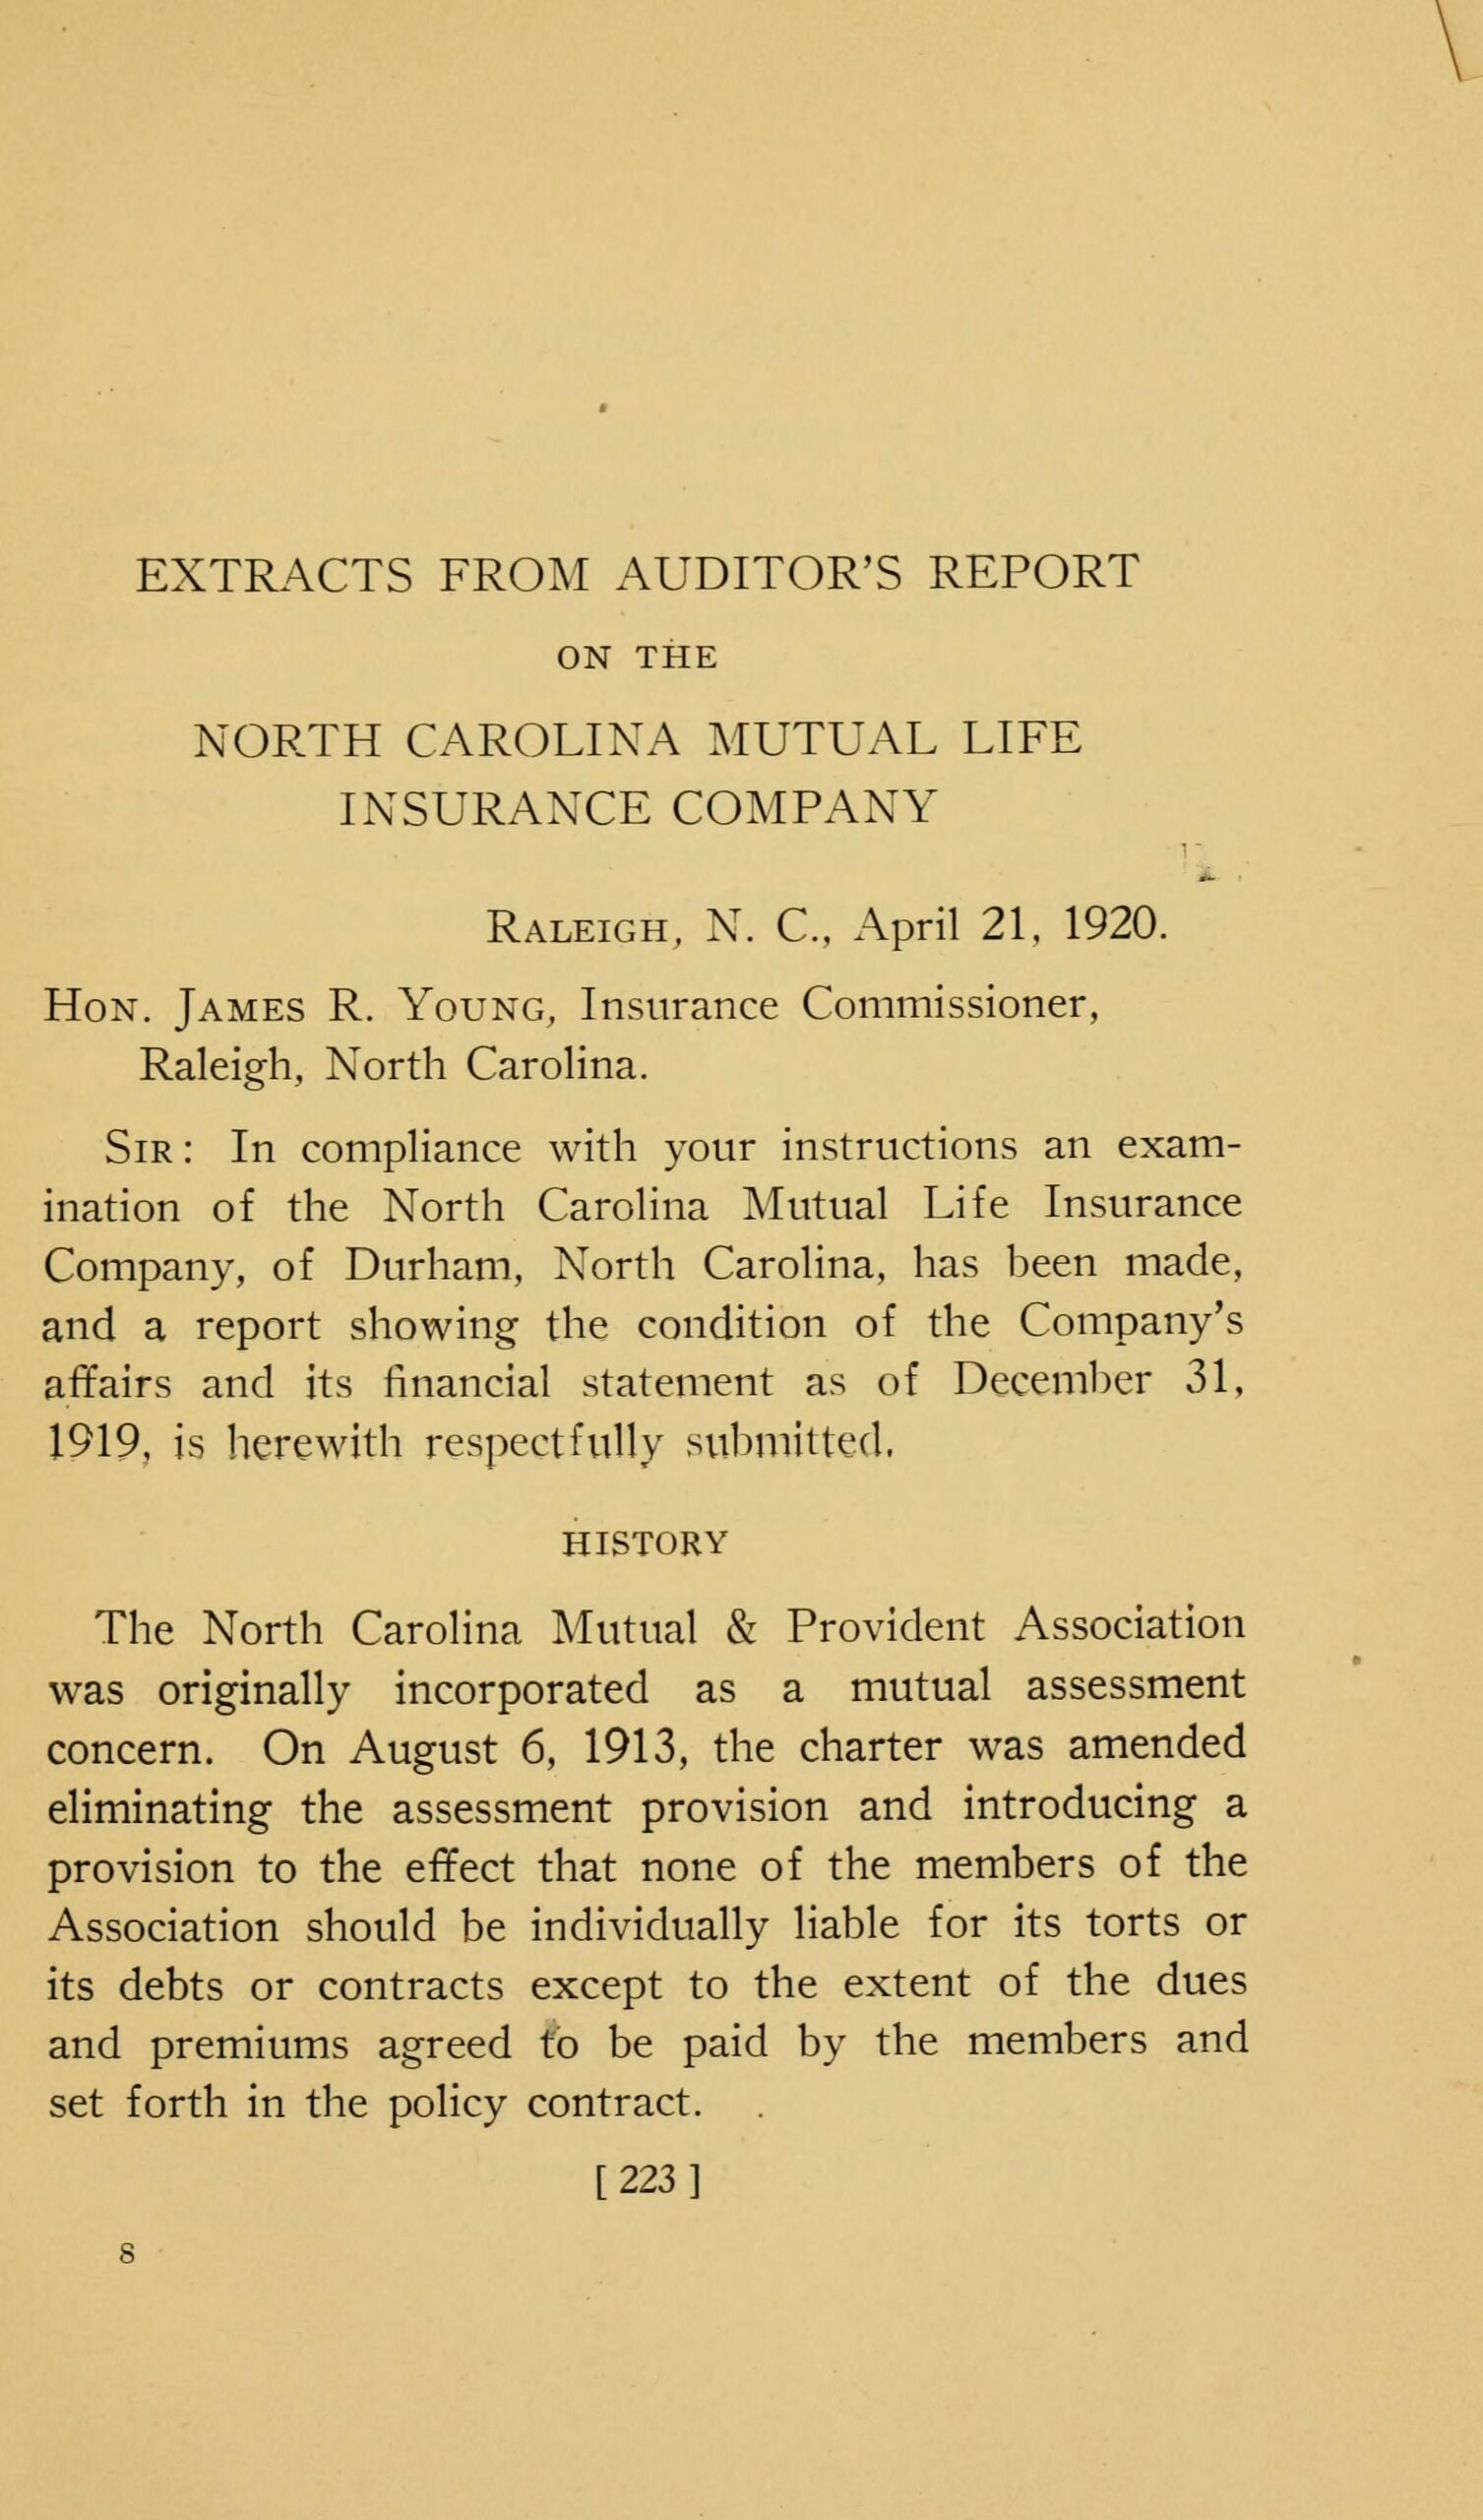
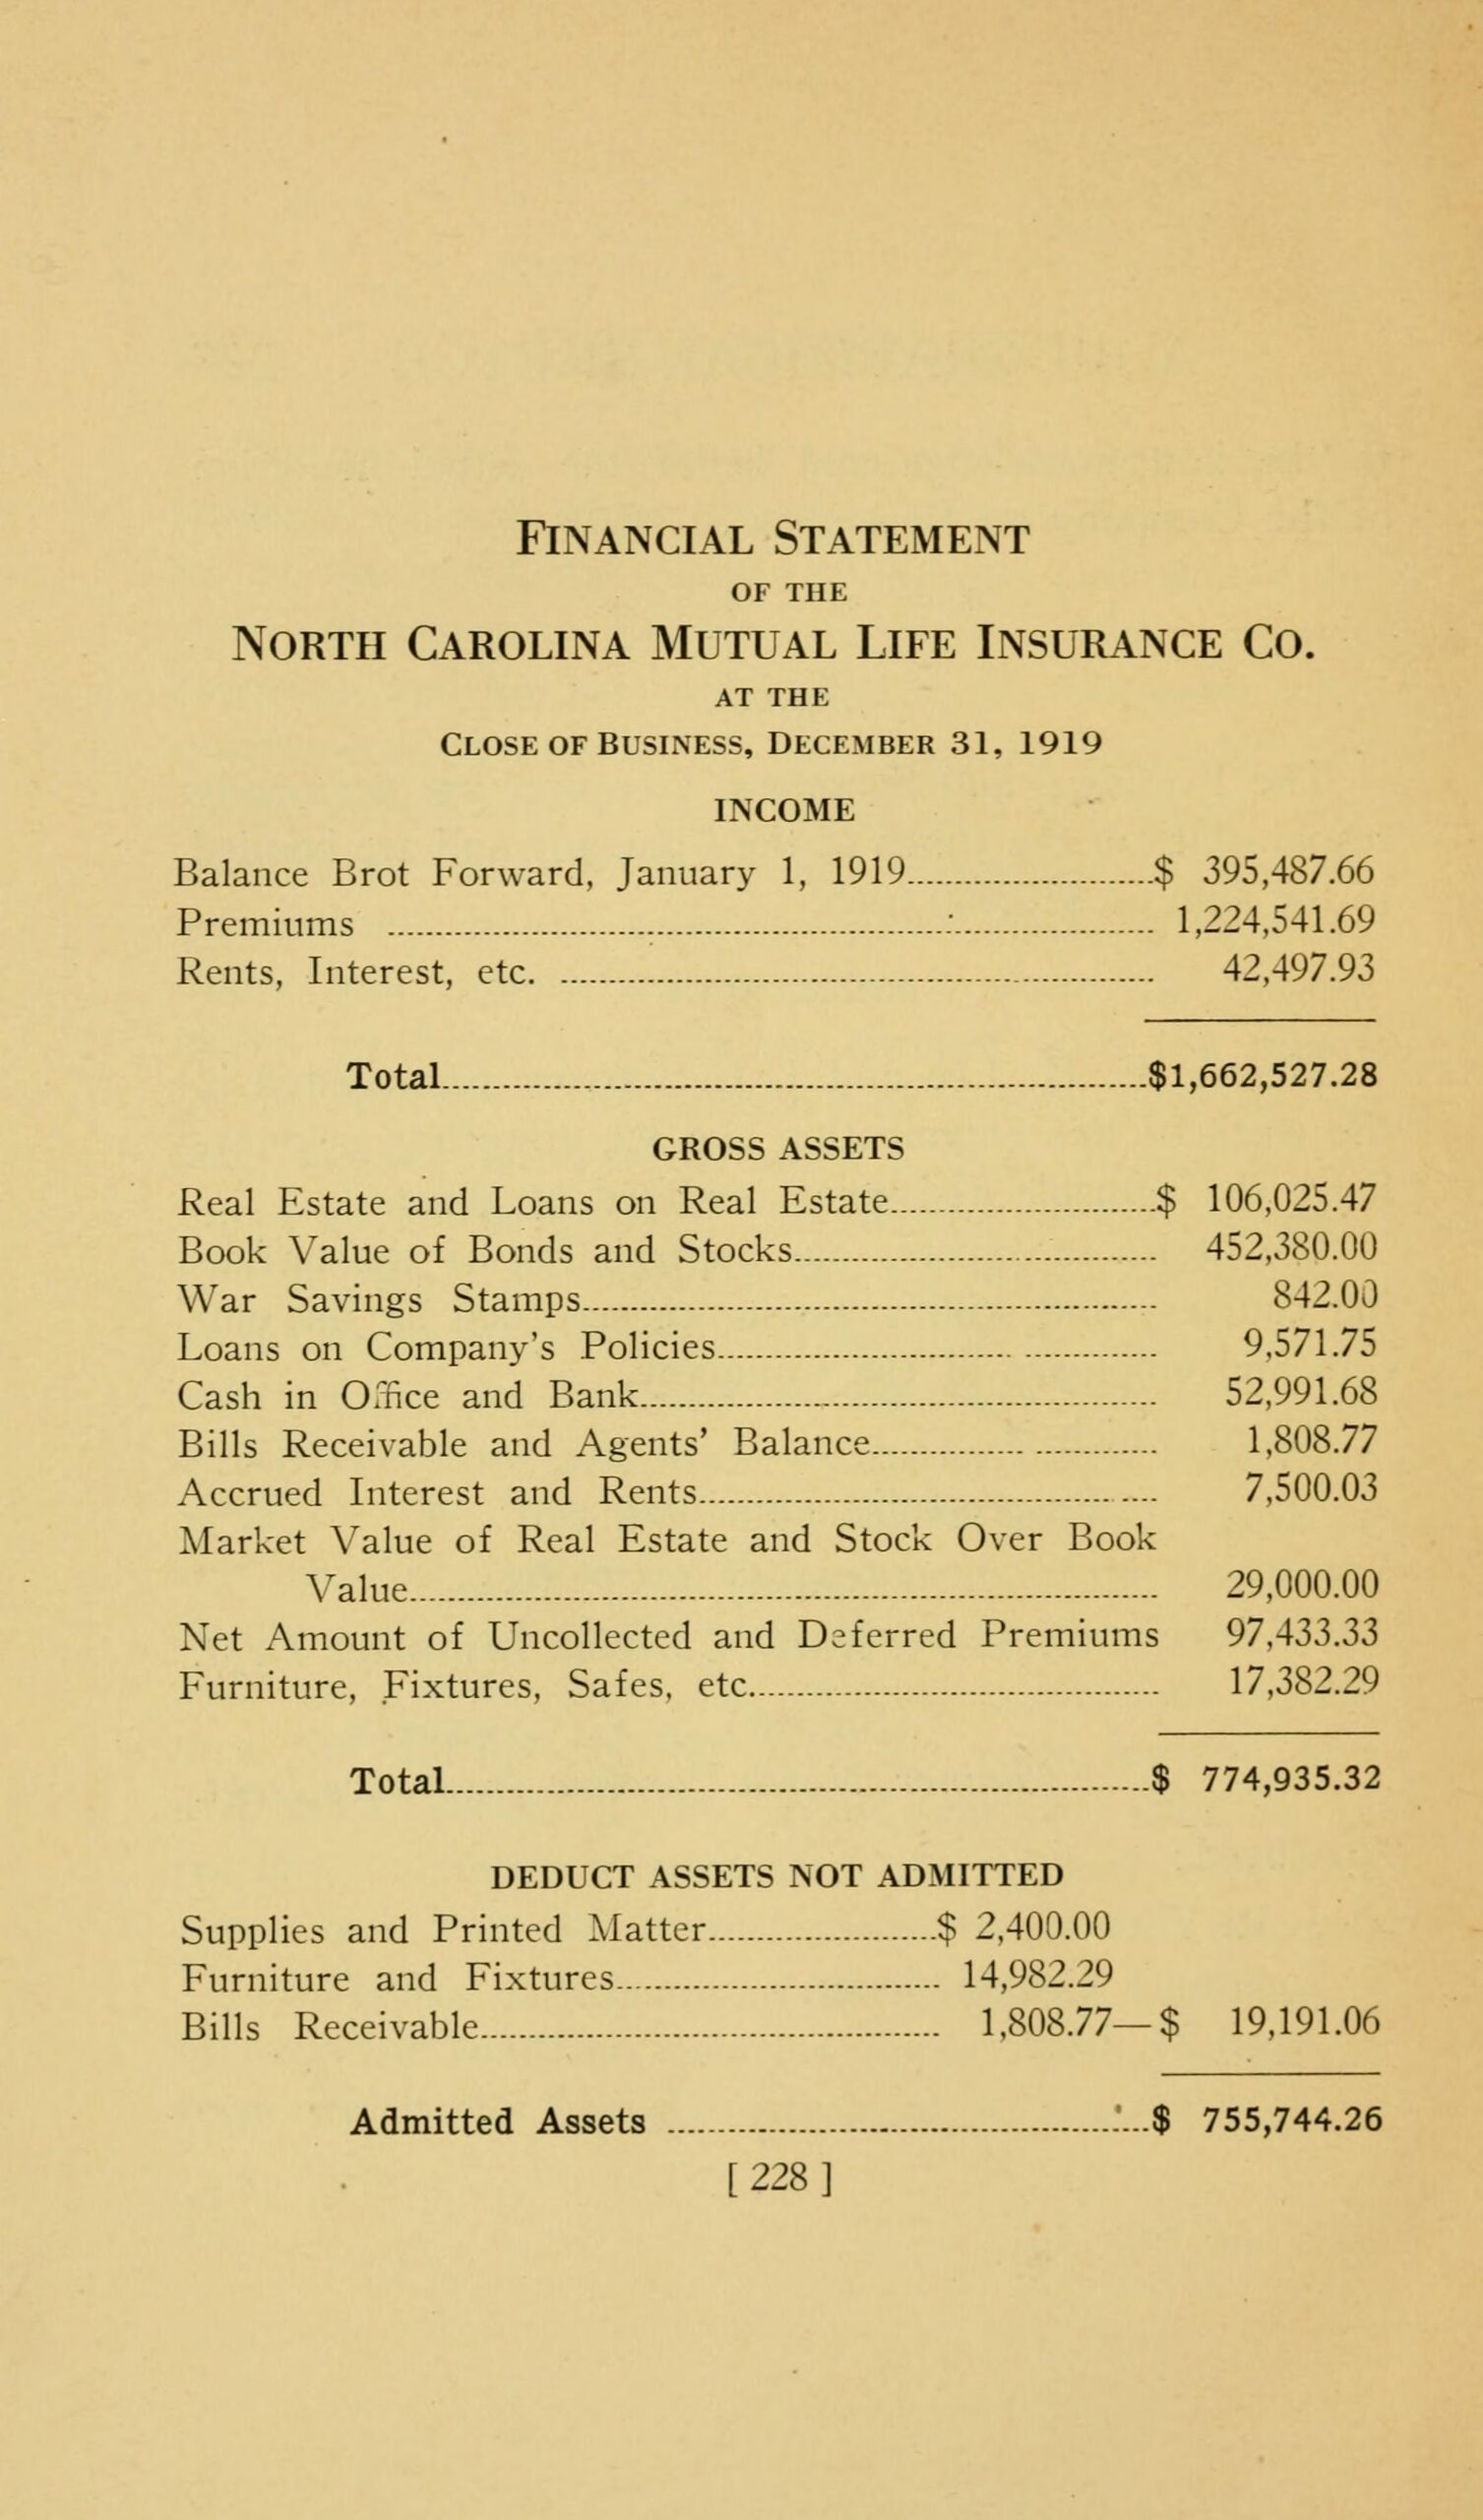
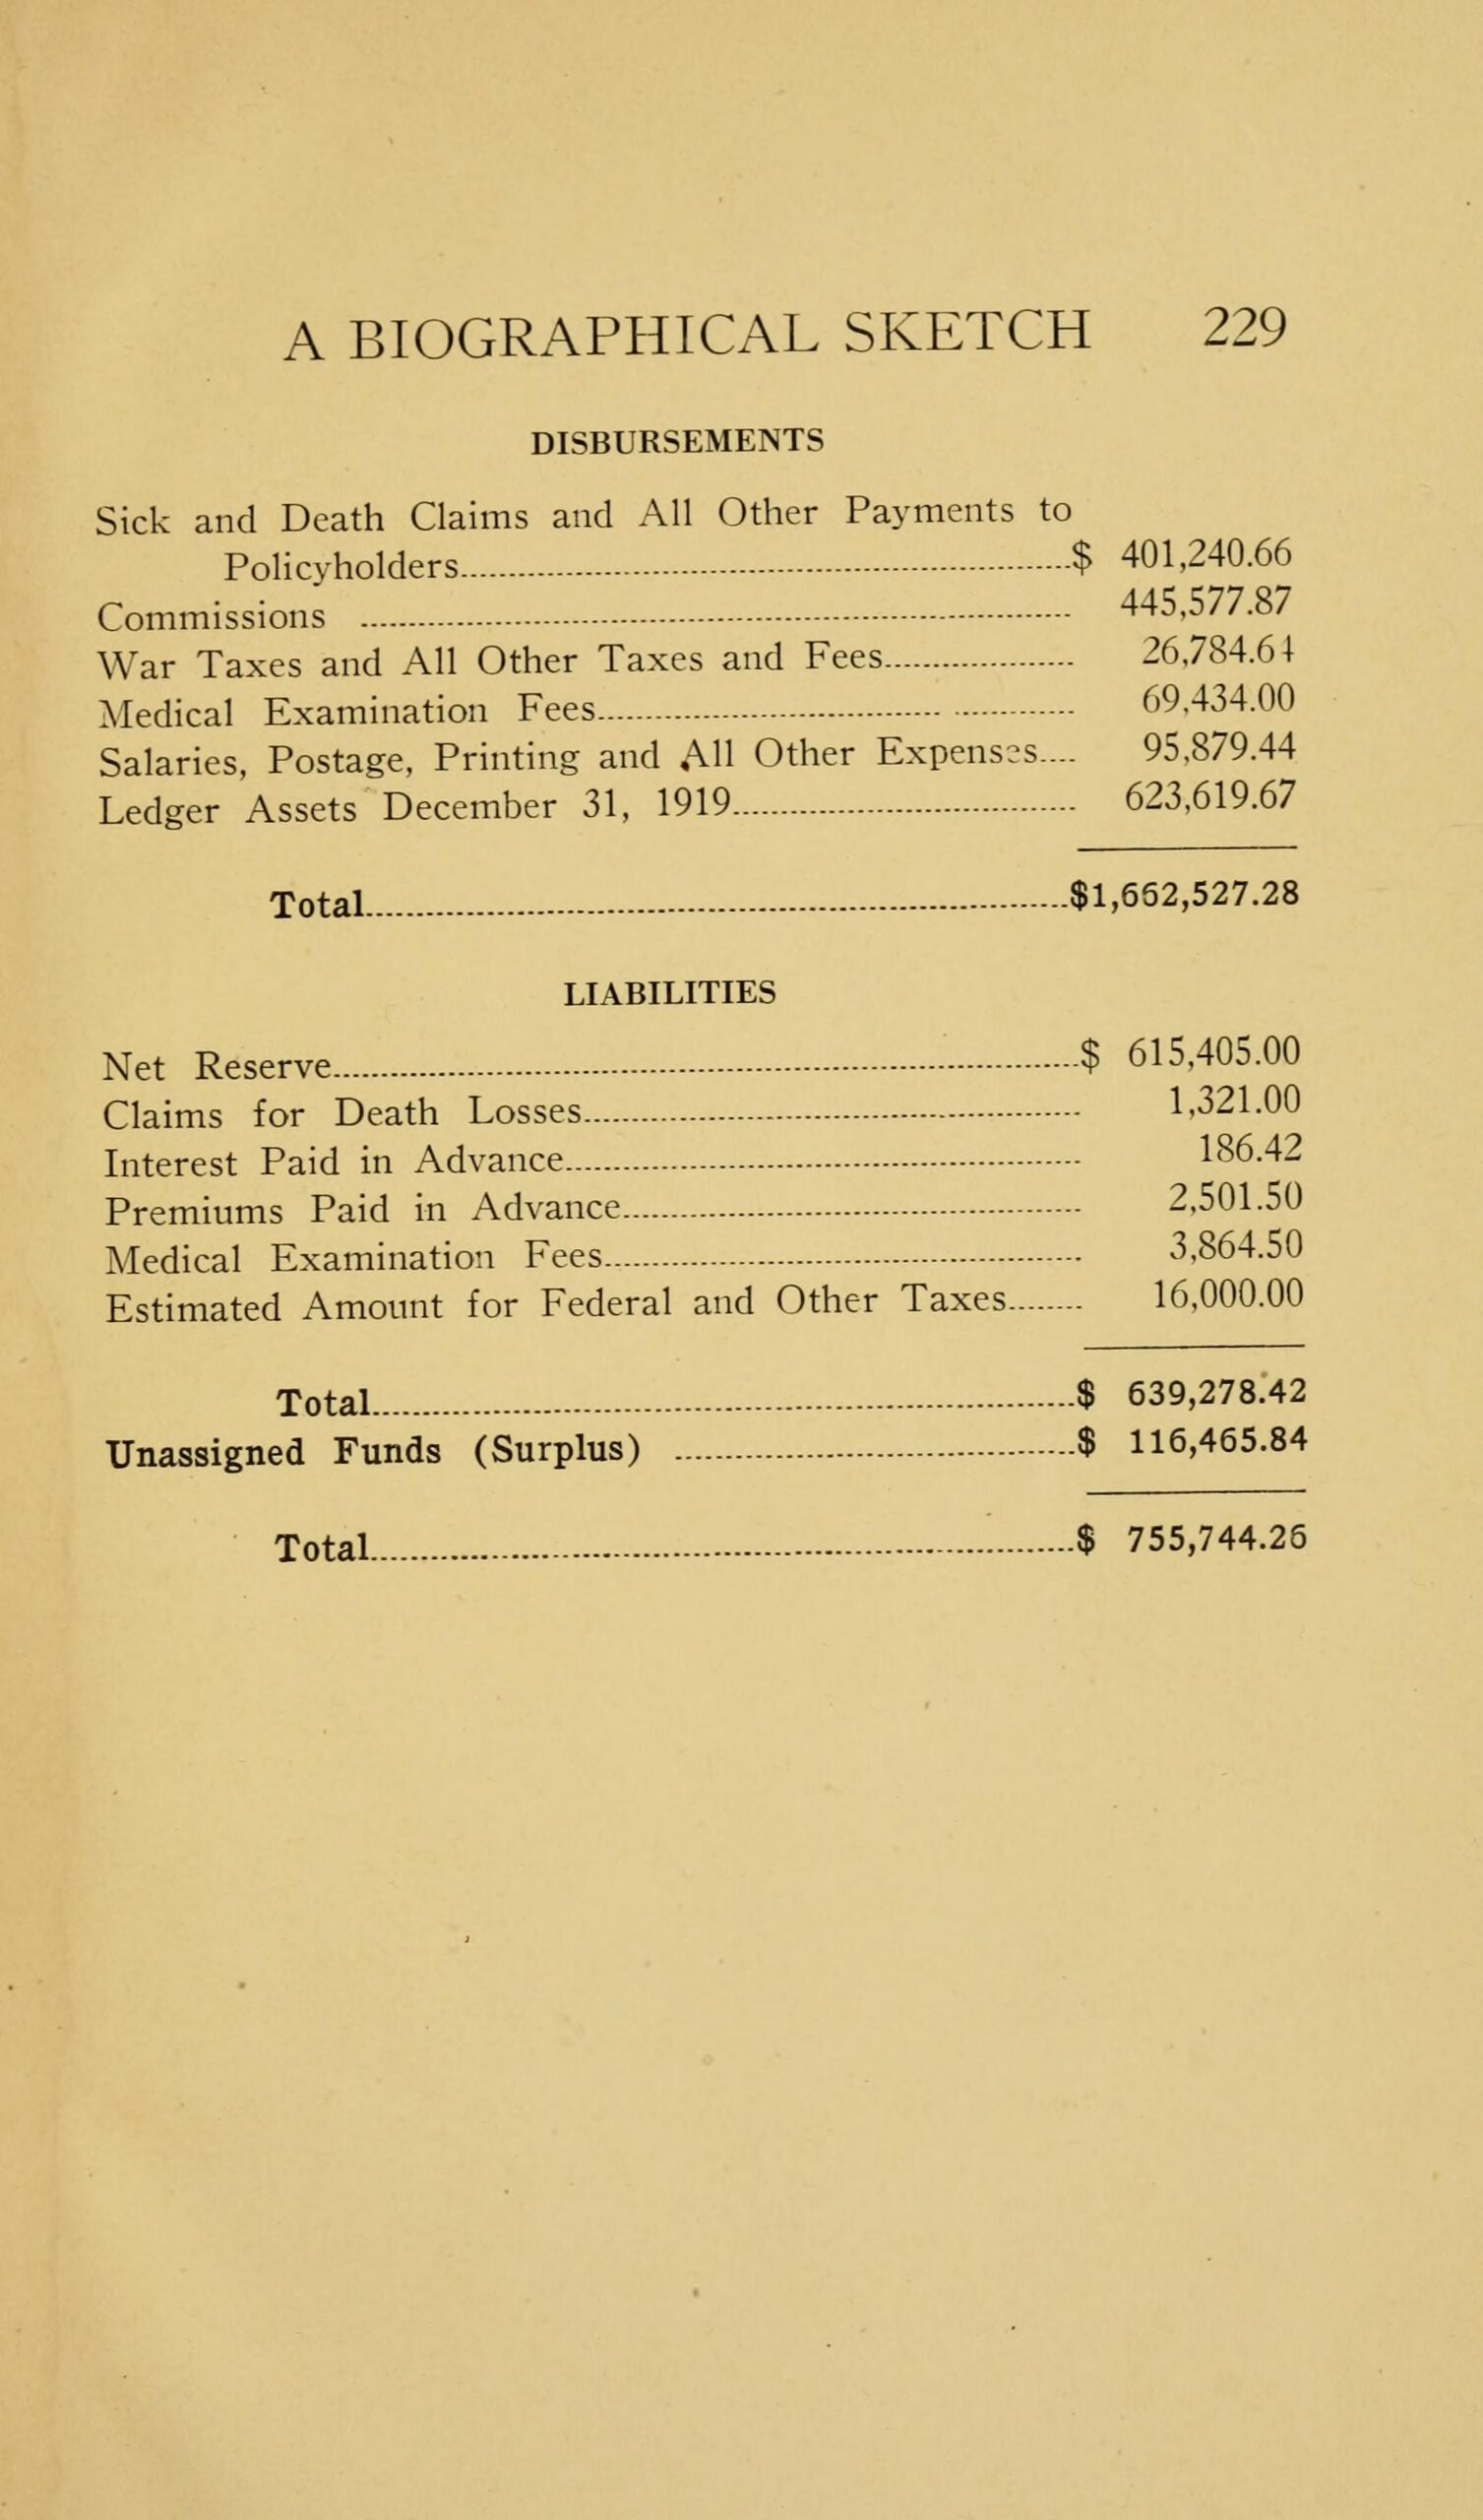
Full file: Open full-size page 1 · Open full-size page 2 · Open full-size page 3
Evidence classification: Printed reproduction of examination and financial statement; not the signed original or account books. Company figures are not personal wealth.
Rights note: Andrews’s 1920 publication is public domain in the United States.
Source: Internet Archive digitized copy of Andrews (1920). Historical publication is public domain in the United States. The complete examination continues on pp. 224–227.
Read the evidence at the level it actually survives
Evidence register: BEHI-P014-S01–S16. Reader route: match the question to the source identifier in the evidence register below, then read its scope and correction. For financial claims, retain entity, date, unit, and category; for ownership, seek the actual instrument and subsequent disposition.
A useful new contribution includes a complete legible scan, repository and collection, instrument or file number, dates, all relevant pages, and provenance. It can revise a specific receipt without forcing unrelated claims into a blanket Verified classification.
SOURCE REGISTER & EVIDENCE LIMITS
EVIDENCE & CONTEXT
| Source | Description | Date | Evidence Classification | Notes |
|---|---|---|---|---|
| Incorporation act — first-page reproduction BEHI-P014-S01 | Private Laws of North Carolina, 1899, chapter 156; reproduced first page | 1899 | VERIFIED | The inspected first page names John Merrick, A. M. Moore, J. E. Shepard, W. G. Pearson, D. T. Watson, T. O. Fuller, E. A. Johnson and W. C. Bruce. It creates the North Carolina Mutual and Provident Association for sixty years and describes death, sickness, accident and burial benefits. The reproduction ends during section 2. The remaining act, ratification date and later amendments were not inspected. Named incorporators are not automatically a cash subscription ledger. |
| Fifteenth-anniversary premium-income spread BEHI-P014-S02 | Duke exhibit item 8537; anniversary spread, 1899–1914 | April 1, 1914 | VERIFIED | The inspected company publication labels John Merrick founder and president, A. M. Moore secretary-treasurer and C. C. Spaulding vice-president/general manager. Its premium chart ends at $358,311. Andrews’s annual table assigns that figure to 1913, and $404,766 to 1914. The anniversary date is not proof that the last chart figure covers calendar 1914. Published company claims are not an independent audit or personal wealth. |
| 1920 memorial biography — source and interpretation BEHI-P014-S03 | R. McCants Andrews, John Merrick: A Biographical Sketch, Durham: Seeman Printery; 264-page scan | 1920 | VERIFIED | The book and OCR were recovered. Relevant business passages were reviewed; selected financial, regulatory and portrait pages were inspected visually. This is a memorial biography, not a complete original business archive. Pages 42–43 acknowledge faulty memory and conflicting accounts. Verification here establishes the inspected publication and its wording, not every narrated event. |
| Barbering, shops and household real estate BEHI-P014-S04 | Andrews, pp. 31–34 | 1880–1892; published 1920 | ATTRIBUTED | John Wright’s retrospective account describes their Durham shop partnership and his 1892 sale to Merrick. Andrews reports three shops serving white customers, two serving Black customers, rental-house activity and an 1887 Fayetteville Street cottage. Original partnership agreements, sale instruments, payroll and property deeds were not recovered. Earlier 1887 and 1889–90 directory leads remain acquisition targets. |
| Dandruff preparation and advertising BEHI-P014-S05 | Andrews, pp. 35–36; advertisements copied from a notebook | About 1890; published 1920 | ATTRIBUTED | Andrews reproduces promotional copy for John Merrick & Co., 104 West Main Street, with a $1 bottle price. He says the notebook was found after Merrick’s death. This supports an attributed trade-name and advertising account; efficacy, patent ownership, trademark registration, sales volume and profit remain unverified. |
| Royal Knights of King David acquisition BEHI-P014-S06 | Andrews, pp. 43–45; W. G. Pearson’s account | September 24, 1883; published 1920 | ATTRIBUTED | The retrospective account identifies Merrick, John Wright, W. A. Day, J. D. Morgan and T. J. Jones in the acquisition from Reverend Morris. Royal Knights was a separate fraternal assessment organization. Its experience is relevant context, but must not be represented as North Carolina Mutual’s 1899 incorporation or merged cash account. |
| Insurance organizers and reported subscriptions BEHI-P014-S07 | Andrews, pp. 64–66 | 1898–1899; published 1920 | ATTRIBUTED | Andrews names seven 1898 organizers and reports $50 each in capital stock, business beginning April 1, 1899, and a later offer to return $50 plus interest for releases. Seven times $50 equals $350 as Institute Analysis of reported subscriptions. No founding cash book, bank deposit, subscription instrument or executed release was inspected. The organizer list differs from the eight names on the charter’s first page. |
| Parrish Street offices and South Carolina deposit BEHI-P014-S08 | Andrews, pp. 87–89 | 1904–1905; published 1920 | ATTRIBUTED | The biography reports an $8,000 Parrish Street site and office project, and a $10,000 South Carolina deposit supported by Merrick and Moore mortgaging property and obtaining a Fidelity draft. This is not a recovered mortgage or bank entry. Earlier $6,000 Fidelity-loan and $550 monthly-rent leads remain separate unresolved transactions; they must not be substituted for the regulatory deposit. |
| Bank, drugstore and allied enterprise accounts BEHI-P014-S09 | Andrews, pp. 54–63 | 1907–1908; published 1920 | ATTRIBUTED | Andrews reproduces a July 29, 1907 bank-organizing notice and describes Bull City Drug’s 1908 organizers and later sale of stores. These are accounts of collaboration. Minutes, stock ownership, bank statements, drugstore sale contracts and manufacturing loss records were not inspected. Collective participation does not establish Merrick’s exclusive ownership. |
| Annual premium-income table BEHI-P014-S10 | Andrews, pp. 105, 108–109; PDF pp. 127, 130–131 | 1899–1919; published 1920 | VERIFIED | The inspected printed table gives $840 for 1899, $358,311 for 1913, $404,766 for 1914, $819,771 for 1918 and $1,224,541 for 1919. These are rounded annual premium figures in a publication. Duke’s modern exhibit places more than $1 million in 1918; the conflict is preserved pending original returns. Premiums are not profit or Merrick’s personal income. |
| Regulatory examination — reproduced extracts BEHI-P014-S11 | Andrews, pp. 223–227; PDF pp. 253–257 | April 21–24, 1920; condition December 31, 1919 | VERIFIED | The inspected book prints report extracts signed in print by E. T. Burr and S. F. Campbell, approved by J. R. Young April 24. They report a 1913 charter amendment and April 7, 1919 name amendment, test checks for 1916–1918 and a detailed 1919 check through agents’ reports, agency registers, cash journal and checks. This is an inspected printed reproduction; the original signed report and underlying books were not inspected. Andrews’s narrative May 12 announcement is a different event from the reported April 7 legal change. |
| 1919 financial statement — reproduced appendix BEHI-P014-S12 | Andrews, pp. 228–229; PDF pp. 258–259 | December 31, 1919; published 1920 | VERIFIED | The visually inspected statement prints premiums $1,224,541.69; rents/interest $42,497.93; opening balance $395,487.66; gross assets $774,935.32; admitted assets $755,744.26; liabilities $639,278.42; surplus $116,465.84; policyholder payments $401,240.66 and commissions $445,577.87. Its $1,662,527.28 total includes the opening balance and is not annual revenue. Premiums plus rents/interest equal $1,267,039.62 (Institute Analysis). The liabilities-plus-surplus total is printed $755,744.25, one cent below the assets-side total. No silent correction is made. This year-end account includes months after Merrick’s August death. |
| Institutional biography and historical marker BEHI-P014-S13 | NC DNCR, John Merrick 1859–1919 (G-109) | 2023; inspected October 4, 2026 | ATTRIBUTED | The state historical account describes his Durham move in 1880, the October 20, 1898 organizing meeting, February 1899 incorporation, subsequent Moore presidency, 1926 reinterment and July 11, 1943 launch of the Liberty ship John Merrick. These are institutional historical accounts. They do not establish personal net worth, an inspected estate inventory or present-day company operations. |
| Duke exhibit — founders and growth BEHI-P014-S14 | Soul & Service: early years and founder page | Modern exhibit; inspected October 4, 2026 | ATTRIBUTED | Duke describes Merrick’s enslaved origins, barbering and insurance leadership and joint Duke/NCCU archival custody. The early-years exhibit states premium income exceeded $1 million by 1918, conflicting with the 1920 table’s $819,771. The 1921 six-story building belongs to the successor period, after Merrick’s death. The exhibit is a research guide, not a substitute for annual returns. |
| Estate and deed reconciliation — acquisition register BEHI-P014-S15 | Durham probate and Register of Deeds research targets; earlier correspondence leads | 1881–1925 deeds; 1919/1939 estates | ATTRIBUTED | Durham County Register of Deeds supplied an eleven-page historical index PDF, which BEHI inspected: mortgage indexes on PDF pp. 1–4 and deed indexes on pp. 5–11, covering the requested 1881–1925 period. These are index locators, not the underlying deeds or mortgages, and do not establish transaction terms or an ownership chain. Original probate files also remain unrecovered: Merrick’s 1919 will, inventory, accounts and business interests, and Martha Merrick’s 1939 Will File No. 1441, identified in the State Archives published index; the original will and related estate-administration file remain uninspected. The 1901 Parrish sheriff-sale, 1887 cottage, 1911 Carr financing, Fidelity/Home Savings loans and $550 rent lead still require instrument-by-instrument reconciliation. |
| Company minutes and capital reconciliation — acquisition register BEHI-P014-S16 | Duke/NCCU North Carolina Mutual archives; targeted minutes and capital records | 1898–1908 research targets | ATTRIBUTED | Obtain complete 1899 act, amendments, 1898–1903 minutes, subscriptions and first financial records. Earlier leads identify June 1, 8, 9 and 12, 1905, and February 17–18, 1908 minutes; each date remains a target, not a verified meeting entry. Reconcile $6,000 Fidelity-loan collateral separately from the biography’s $10,000 South Carolina deposit. No requested file is labeled inspected solely because an inquiry was sent. |
THE RECORD & ITS LIMITS
A receipt establishes the exact point supported: named incorporators, printed office titles, a financial category or a reported event.
The correction identifies limitations such as incomplete charter coverage, promotional context, post-death reporting or missing original instruments.
New documents should include repository, collection, box/folder or instrument number, date, page range and a legible complete scan.
READING THE EVIDENCE
Evidence remains revisable. A full deed, ledger or regulatory return can strengthen or correct the present account; the receipt chain records what the current conclusion rests on.
RESEARCH GAPS & OPEN QUESTIONS
ECONOMIC INDICATORS — MISSING EVIDENCE
Personal net estate
Content condition: Not yet established. John Merrick estate
Reporting period not established
Evidence needed / present limit: Company assets cannot substitute for probate inventory, debts and ownership records.
- Complete 1899 chapter 156, ratification and all later amendments; distinguish legal incorporators from earlier organizers.
- 1898–1903 minutes, signed subscriptions, founding cash book, bank deposits and releases; test the reported $50-per-organizer capital.
- Original 1913 and 1918–1919 annual returns and 1920 regulatory examination; reconcile chart dating, the million-dollar threshold and the one-cent printed balance discrepancy.
- June 1, 8, 9 and 12, 1905, and February 17–18, 1908 minutes named in earlier research leads; verify dates and transactions before adopting them.
- South Carolina deposit, Fidelity draft, mortgages and releases; keep the reported $10,000 requirement separate from the $6,000 loan lead.
- Durham deeds, 1881–1925, and predecessor-county indexes under John, John H., John Henry, Martha, heirs and executors; recover the cottage, Parrish sheriff sale, Carr financing and rent instruments.
- 1919 John Merrick probate: will, inventory, accounts and business interests; Martha Merrick’s 1939 will, File 1441 as identified by N.C. Archives correspondence. Searches for both requested November 3, 2026; order/payment instructions pending, records not yet received or inspected.
- Shop partnership and 1892 sale, directories, leases, employee/payroll records and operating books; bank and drugstore stock and sale records.
- Dandruff product’s original notebook/advertisements, sales ledger and any patent or trademark filings; no efficacy or profitability claim without appropriate evidence.
Submit evidence: Use BEHI’s site contact channel to contribute documents or corrections. Include provenance and complete page coverage; distinguish an original instrument, copy, transcript and later recollection. Requested documents are not treated as inspected until they are received and reviewed.
RESEARCH UPDATES & RECONCILIATION
Estate-record searches requested — November 3, 2026
The North Carolina Department of Natural and Cultural Resources, Archives and Records Correspondence Unit, offered to search for John Merrick’s Durham County estate, 1919, and Martha Merrick’s will, File 1441 (1939). BEHI requested that an out-of-state order be created for both records. Order and payment instructions are pending; payment has not been confirmed.
The quoted upfront search fee is $20 per record ($40 total), covering up to twenty copied pages per record if found, plus $0.10 per additional page. A search does not guarantee a record will be located. BEHI requested the complete surviving John Merrick estate file, including inventory, accounts and settlement, and Martha Merrick’s will with associated probate documents; digital delivery was requested if available.
Evidence classification: Research correspondence and acquisition status only. Neither file has yet been supplied or inspected through this request. File 1441 is the identifier supplied by the archivist, not an independently inspected will. Personal net estate, debts, business holdings and beneficiary interests remain not yet established.
Source: Alison Thurman, Correspondence Unit Head/Reference Archivist, N.C. Archives and Records, email correspondence received November 3, 2026.
Research milestone — Durham County deed and mortgage indexes acquired (October 2026)
Evidence status: Original index images were inspected; underlying deeds and mortgages were not. Index entries alone do not establish transaction terms or an ownership chain.
Read full note: Durham deed and mortgage index update — October 2026
Durham County Register of Deeds Sharon A. Davis supplied an 11-page PDF of historical index extracts relating to John Merrick, covering the requested 1881–1925 period. The inspected scan includes general reverse indexes to mortgages (PDF pp. 1–4) and deeds (pp. 5–11), preserving names, entry dates, and recording book/page locators. The county advises that original deeds can be retrieved from its self-service records website using book/page references; early mortgage instruments are not viewable online, and the office is exploring how to provide copies.
Evidence status: ORIGINAL HISTORICAL INDEX IMAGES INSPECTED; UNDERLYING RECORDED DEEDS AND MORTGAGES NOT YET EXAMINED. Index references guide retrieval but do not alone establish the consideration, legal description, loan balance, terms, ownership chain or connection to Merrick's businesses. Next assignment: transcribe and verify individual book/page entries against the recorded instruments, and await mortgage-copy guidance from the Register of Deeds. Source: Durham County Register of Deeds, historical deed and mortgage index extracts supplied October 2026 (11-page PDF).
Merrick — Charter names eight incorporators
Audited Historical Assertion
The inspected first page of the 1899 act names Merrick among eight incorporators.
BEHI Academic Analysis & Research Clarification
The first page is incomplete. Its list differs from seven earlier organizers and does not prove paid subscriptions or ownership shares.
Supporting Archival Receipts & Primary Sources
HOW TO READ THE RECEIPTS & ARCHIVAL CITATIONS
Evidence linked on this page may include primary archival records, contemporary sources, repository citations, authoritative secondary scholarship, and Institute analysis. Where a physical archival holding has been identified, BEHI provides repository and locator information when available.
Cite This Profile
The Black Economic History Institute (BEHI) Digital Archive