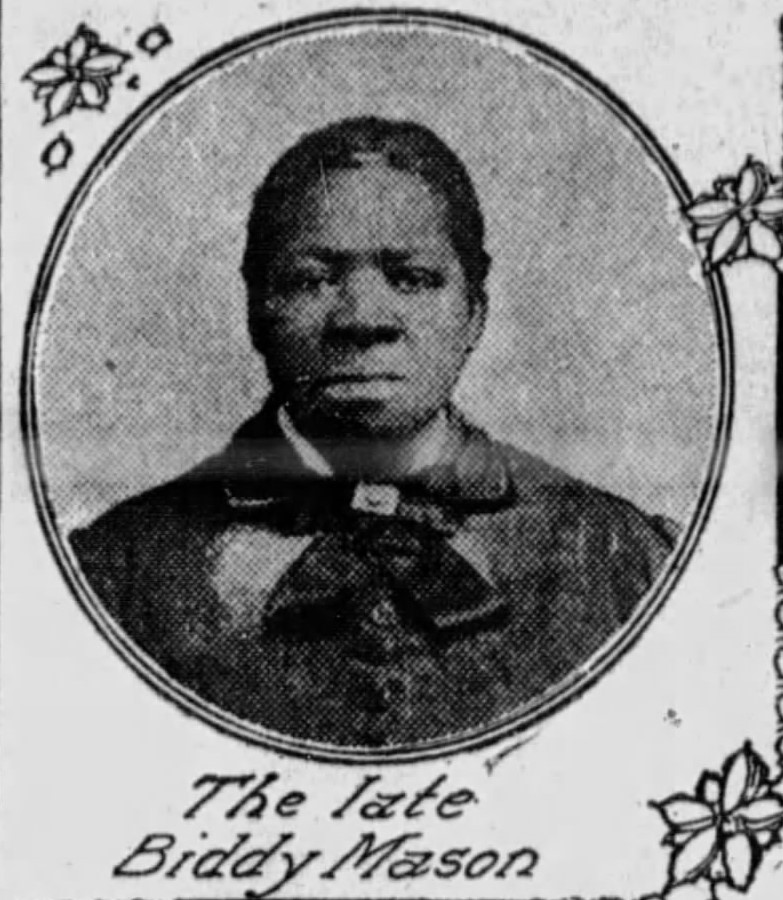
Profile №11 BEHI-P011-BM
Biddy Mason
1818–1891
Midwife, Property Owner, Community Benefactor
Overview
TAKEAWAY: Mason connected freedom, care work, and Los Angeles property with family and community support. Deed terms, estate values, and retrospective accounts retain their evidence limits.
BEHI PROFILE — RESEARCH IN PROGRESS — UPDATED OCTOBER 3, 2026. EVIDENCE IS CLASSIFIED CLAIM BY CLAIM; ATTRIBUTED ACCOUNTS AND UNRESOLVED RESEARCH QUESTIONS ARE IDENTIFIED THROUGHOUT.
OVERVIEW
Bridget “Biddy” Mason turned freedom, skilled care work and urban property ownership into a foundation for her family and a resource for Black Los Angeles. Her story connects an 1856 habeas corpus proceeding with the Spring Street homestead, community fundraising and later family inheritance. This Profile follows those connections document by document while keeping uninspected deeds, estate values and retrospective accounts visible.
Freedom, skilled work, and a lasting family base
Legal protection
The 1856 proceeding addresses liberty and threatened removal from California.
Paid care work
Nursing and midwifery place skilled service at the center of Mason’s economic story.
Property & community
The homestead links family housing with remembered gatherings, fundraising, and later inheritance.
Sources: published freedom-order transcription, NPS biography, and the homestead Receipt. BEHI analysis: these are connected fields of activity, not a fully reconstructed cash-flow account. The amount saved, rental earnings, and net estate remain separate documentary questions.
The dated court order anchors the transition from enslavement.
The 1866 homestead is the center of the documented land trail.
Contemporary fundraising and later recollections reveal different kinds of support.
EXACT ACCOMPLISHMENTS
Historical accounts describe Mason’s nursing and midwifery. Earnings, savings and rental receipts require their own records.
An inspected memorial reproduction identifies an 1866 conveyance to Biddy Mason. The complete recorded deed and its financial terms remain acquisition targets.
An inspected 1869 AME festival advertisement names Mrs. Biddy Mason as a ticket contact for church-building fundraising. It does not establish the amount collected or sole founding.
THE RECORD & ITS LIMITS
A published court-order transcription, inspected newspaper clippings, Beasley’s scanned biography and a memorial deed reproduction provide distinct anchors. Each has a different evidentiary reach.
What did Mason earn, acquire, retain and transfer? Occupational taxes, sale prices, assessed values, family assets and probate net estate require different documents.
This is a full audit of the recovered research and accessible evidence. Original deeds, assessment rolls and the complete probate file remain open acquisition tasks; their absence is identified throughout.
READING THE EVIDENCE
What Would Move This Profile Forward?
These are the next evidence priorities for strengthening this Profile. Each identifies a concrete research step and what it could help establish.
- Complete Probate Case 14493
Obtain the full inventory, appraisal, debt schedules and estate accounts. These would support an 1891 estate valuation distinct from later family-wealth reporting.
- Recover the 1866 deed and later title instruments
Inspect complete deeds, mortgages and transfers for the identified parcels. These would establish purchase terms, ownership changes and financing.
- Match property to tax and rental records
Retrieve county assessment rolls, tax payments and surviving rental accounts for the same parcels and dates. These would distinguish assessed value, ownership costs and income.
- Document the legal church-property history
Seek original AME minutes, incorporation papers, trustee deeds and donation instruments. These would clarify Mason’s documented role beyond the already inspected fundraising advertisement.
Read the Research Gaps & Open Questions for the unresolved issues and evidence limits. New material is reviewed before claims or classifications change.
THE RECEIPTS OR EVIDENCE SUPPORTING THIS PROFILE
Evidence labels apply to individual claims. Read the evidence guide and content-condition definitions.
| SOURCE / LOCATOR | RECORD / CONTEXT | DATE / PERIOD | EVIDENCE STATUS | SUPPORT / LIMITS |
|---|---|---|---|---|
| 1856 freedom order — published transcription | Primary court record via scholarly transcription | January 19, 1856; certified January 9, 1860 | ATTRIBUTED | Text inspected. Names Biddy, Ellen, Ann and Harriet alongside Hannah and her children/grandchild, fourteen people in total. Order dated January 19; later entry January 21; copy certified January 9, 1860. Published text has an inconsistent later-hearing date and spelling variations. Original manuscript not independently inspected. The court record does not establish that Mason personally drafted or filed the petition. |
| 1866 homestead deed — memorial reproduction | Deed-cover reproduction / acquisition lead | November 28, 1866 | ATTRIBUTED | Photograph inspected. Memorial deed cover names William M. Buffum and James F. Burns to Biddy Mason and November 28, 1866. Adjacent memorial text reports $250 and Lots 3 and 8, Block 7, Ord Survey. This is a modern memorial reproduction in a public submission, not a complete Recorder-certified deed. Full instrument, acknowledgment, recording date and book/page remain required. |
| 1891 probate — Case 14493 | Primary archival holding / file needed | 1891; administration thereafter | VERIFIED | Huntington’s own page explicitly identifies the 1891 probate case. VERIFIED applies only to the holding/case identification. Complete will, inventory, appraisal, debts, executor accounts, objections and final distribution have not been inspected. No $300,000 estate total or verified net worth follows from the locator. |
| 1909 Stovall feature — wealth and philanthropy | Historical newspaper clipping | February 12, 1909 | VERIFIED | Three clipping images inspected. Opening figure describes wealth as of 1909; continuation refers to Ellen Huddleston and relatives then controlling the $300,000 estate. VERIFIED applies to what the newspaper says, not to its valuation or an 1891 probate total. Retrospective philanthropy, nursing and migration accounts remain ATTRIBUTED. Original full page/page number still needed. |
| 1869 AME festival advertisement | Contemporary newspaper advertisement | September 25, 1869; event September 30 | VERIFIED | Image inspected. Names Mrs. Biddy Mason among ticket contacts for a festival by the ladies of the AME Church to raise building funds; advertised tickets including supper $2. VERIFIED applies to the advertisement and named role. It does not establish attendance, money collected, sole founding, incorporation or land donation. Museum surrounding prose/caption has an unrelated 1865 date; the clipping itself explicitly advertises September 30, 1869. |
Background
TAKEAWAY: Court texts document Mason and her daughters within the freedom proceeding. Exact birth details reported through later family testimony still require original-record comparison.
BACKGROUND
Mason was born enslaved and was brought west with Robert Smith’s household, eventually residing in California. Her three daughters—Ellen, Ann and Harriet—appear with her in the court text. Beasley’s 1919 account preserves a family-Bible birth date of August 15, 1818 and a Georgia birthplace, but the underlying Bible and original census comparisons require further inspection.
A forced migration and a family network
Mississippi → Utah
The court text describes Smith’s move from Mississippi to Utah with the people he enslaved.
Utah → California
Residence in California became central to the court’s analysis of liberty and threatened removal.
Mason & the Owens family
Later accounts place family relationships and support networks alongside her transition into independent work.
Migration sequence based on the published freedom-order transcription; family context attributed to NPS biography and the sources below. This is a schematic, not a measured travel route. It avoids an exact mileage claim and preserves Ellen, Ann, and Harriet as the daughters named in the court text. Conflicting birthplaces remain unresolved.
HISTORICAL & ECONOMIC CONTEXT
Movement with an enslaver was not a voluntary business venture.
The Mason and Owens families were closely connected.
Search spelling and household variants before assigning a record.
THE RECORD & ITS LIMITS
Beasley credits Ellen Huddleston’s family Bible for the precise birth date and Hancock County, Georgia. NPS notes conflicting census birthplace reports. Preserve the attribution rather than declaring the discrepancy closed.
The published 1856 order identifies Biddy and her daughters separately from Hannah and her children and grandchild. It does not prove that all fourteen petitioners were Mason’s relatives.
Later narratives describe travel and livestock duties. Exact mileage, walking every mile and the beginning of her medical training are not independently established by the inspected court order.
READING THE EVIDENCE
EVIDENCE & CONTEXT
| Source | Description | Date | Evidence Classification | Notes |
|---|---|---|---|---|
| 1856 freedom order — published transcription | Primary court record via scholarly transcription | January 19, 1856; certified January 9, 1860 | ATTRIBUTED | Text inspected. Names Biddy, Ellen, Ann and Harriet alongside Hannah and her children/grandchild, fourteen people in total. Order dated January 19; later entry January 21; copy certified January 9, 1860. Published text has an inconsistent later-hearing date and spelling variations. Original manuscript not independently inspected. The court record does not establish that Mason personally drafted or filed the petition. |
| 1856 judicial opinion — contemporary newspaper transcription | Contemporary legal account | January 28, 1856 opinion; April 5, 1856 publication | ATTRIBUTED | Text inspected. Discusses California residence, threatened removal to Texas, duress and temporary guardianships. Records a private inquiry into Mason’s wishes. Original newspaper page not inspected. Distinguish the January 28 explanation from the January 19 freedom order; no purchase price for freedom is established. |
| 1860 census — household identity and birthplace | Federal census lead | 1860 | ATTRIBUTED | Institutional identification inspected; original census row not transcribed in this audit. Search Bridget Mason, Biddy Mason and Bridget Owens, then reconcile household, age, occupation and birthplace. No census asset amount is adopted. |
| 1870 and 1880 census — property and identity | Federal census acquisition targets | 1870 / 1880 | ATTRIBUTED | Prior scholarship reports inconsistent Mississippi/Georgia birthplace entries. Original images not inspected here. Obtain household pages before claiming exact birthplace or census wealth. Census-reported real/personal estate would be a dated declaration, not audited lifetime net worth. |
| Beasley 1919 — family recollections and biography | Published historical account | 1919 | ATTRIBUTED | Digitized text inspected; page images checked separately. Credits Ellen Huddleston and a family Bible; reports $2.50 per day as a confinement nurse and January 15, 1891 death. The biographical page prints 1854 for freedom, inconsistent with the 1856 court text. Sales of $12,000/$44,000 and family inheritance stories lack full deed identifiers here and are not verified. Stovall passages are repeated, not independent corroboration. |
The Problem
TAKEAWAY: Mason needed legal protection against continued coercion and removal despite California’s prohibition of slavery. Freedom and later household security were distinct practical challenges.
THE PROBLEM
California’s prohibition of slavery did not automatically protect Mason from continued coercion. The judicial texts describe years of residence under Smith’s control and a threatened removal to Texas. The practical problem was securing freedom and protection for adults and children, then building household stability in a racially unequal economy.
What the freedom proceeding addressed
The threat
Removal to Texas could jeopardize the liberty of adults and children.
The court’s inquiry
The text examines California residence, coercion, and whether apparent consent reflected free choice.
Distinct protections
Liberty and temporary guardianship provisions addressed different needs within the proceeding.
Based on the published freedom-order transcription and the published judicial opinion identified below. Legal-process diagram: this summarizes the historical text; it does not claim Mason wrote the petition, purchased her freedom, or delivered an invented courtroom speech. Legal protection did not by itself supply wages, housing, or equal economic access.
DIMENSIONS OF THE PROBLEM
The opinion examines whether apparent consent was freely given.
Freedom and temporary child guardianships were related but distinct orders.
Legal liberty did not supply wages, land or equal opportunity.
HOW THE PROBLEM SHOWED UP
Use the historical title In the Matter of Hannah and Biddy and their children on Petition for Habeas Corpus. Popular shorthand Mason v. Smith should not replace the document’s identity.
The published opinion records a private inquiry into her wishes. It supports reluctance to go to Texas, but does not justify an invented courtroom speech, a self-written petition or a claim that she purchased freedom.
Institute analysis: protection from coerced removal made independent work and property holding possible. The legal record alone does not establish the amount of later savings or wealth.
READING THE EVIDENCE
EVIDENCE & CONTEXT
| Source | Description | Date | Evidence Classification | Notes |
|---|---|---|---|---|
| 1856 freedom order — published transcription | Primary court record via scholarly transcription | January 19, 1856; certified January 9, 1860 | ATTRIBUTED | Text inspected. Names Biddy, Ellen, Ann and Harriet alongside Hannah and her children/grandchild, fourteen people in total. Order dated January 19; later entry January 21; copy certified January 9, 1860. Published text has an inconsistent later-hearing date and spelling variations. Original manuscript not independently inspected. The court record does not establish that Mason personally drafted or filed the petition. |
| 1856 judicial opinion — contemporary newspaper transcription | Contemporary legal account | January 28, 1856 opinion; April 5, 1856 publication | ATTRIBUTED | Text inspected. Discusses California residence, threatened removal to Texas, duress and temporary guardianships. Records a private inquiry into Mason’s wishes. Original newspaper page not inspected. Distinguish the January 28 explanation from the January 19 freedom order; no purchase price for freedom is established. |
| Beasley 1919 — family recollections and biography | Published historical account | 1919 | ATTRIBUTED | Digitized text inspected; page images checked separately. Credits Ellen Huddleston and a family Bible; reports $2.50 per day as a confinement nurse and January 15, 1891 death. The biographical page prints 1854 for freedom, inconsistent with the 1856 court text. Sales of $12,000/$44,000 and family inheritance stories lack full deed identifiers here and are not verified. Stovall passages are repeated, not independent corroboration. |
What She Built
TAKEAWAY: Mason combined paid care work with a homestead and property interests. Complete deeds, assessments, and probate records are needed to establish the financial results.
WHAT SHE BUILT
Mason’s enterprise joined paid care work with a family homestead and property interests in a growing city. The 1866 deed-cover reproduction identifies the Spring Street acquisition. Later research describes rentals, construction and transfers to descendants, but the exact title chain and financial results still depend on complete deeds, assessments and probate papers.
The homestead as an economic and social asset
Skilled services
Care work offered an income-producing occupation; surviving accounts do not establish annual earnings.
Family residence
The Spring Street acquisition supplied a home base whose parcel and ownership history can be traced.
Wider use
Institutional and family accounts connect the home with gatherings and community assistance.
Lots 3 and 8 · Block 7 · Ord Survey
The memorial reproduction supplies these reported parcel identifiers; see the homestead Receipt. This asset diagram is not a property map. Full deed, acknowledgment, recording reference, leases, and later transfers are needed to establish the title chain and financial results.
THE ENTERPRISE SYSTEM
Historical occupational language should retain its period meaning.
The home served residential and wider community purposes.
Owens family businesses and later buildings need separate ownership dates.
THE RECORD & ITS LIMITS
The memorial reproduction names Buffum and Burns as sellers and dates the deed November 28, 1866. Its adjacent text reports $250 and Lots 3 and 8, Block 7. Obtain the full recorded instrument before upgrading its terms to verified primary evidence.
The 1868 Owens–Hall purchase, 1875 sale, 1884 transaction and 1890 transfer remain distinct leads. A repeated narrative of many properties does not establish a complete asset schedule.
An inspected 1869 advertisement names Mason among AME festival ticket contacts. FAME’s current history credits her home meetings and generosity in 1872. These sources support participation and remembered leadership, with formal founding and land transfer still to be documented.
READING THE EVIDENCE
EVIDENCE & CONTEXT
| Source | Description | Date | Evidence Classification | Notes |
|---|---|---|---|---|
| 1866 homestead deed — memorial reproduction | Deed-cover reproduction / acquisition lead | November 28, 1866 | ATTRIBUTED | Photograph inspected. Memorial deed cover names William M. Buffum and James F. Burns to Biddy Mason and November 28, 1866. Adjacent memorial text reports $250 and Lots 3 and 8, Block 7, Ord Survey. This is a modern memorial reproduction in a public submission, not a complete Recorder-certified deed. Full instrument, acknowledgment, recording date and book/page remain required. |
| 1862 federal occupational tax — underlying assessment needed | Federal tax-record citation | October 30, 1862 | ATTRIBUTED | NPS reports a $10 federal occupational tax under the category physician. Article and citation inspected; underlying assessment line and roll/page not recovered. A federal revenue category is not proof of a medical degree, modern professional licensure, earnings or profit. |
| 1868 Owens–Hall acquisition — unresolved deed | Prior scholarly deed lead | 1868 | ATTRIBUTED | Earlier research attributed four lots and $375 to an acquisition from Charles Owens and Martha Hall near Olive and Charity Streets. Exact recording citation and original instrument remain unrecovered. Preserve as an open research lead, not verified portfolio acreage or consideration; reconcile against probate and title chain. |
| 1875 Spring Street transfer — unresolved instrument | Prior deed / newspaper lead | January 2, 1875 | ATTRIBUTED | Date and parties retained from prior research; original deed and cited newspaper page not reopened. Book/page, legal description, consideration and extent of retained title remain pending. Do not merge this with a later $1,500 sale story or treat a reported price as net profit. |
| 1884 Lot 8 sale — unresolved transaction | Prior scholarly sale lead | April 7, 1884 (prior citation) | ATTRIBUTED | Full article and deed were not independently re-read in this audit. Earlier narratives also circulate an 1884 $1,500 figure. Neither amount is adopted as verified consideration. Match date, lot/block, grantor/grantee and instrument before selecting a number or calculating a return. |
| 1890 Mason–Owens deed — family transfer lead | Prior deed lead | June 20, 1890 | ATTRIBUTED | Earlier research describes a transfer to her grandsons with nominal monetary consideration and family affection. Original deed, recording locator, reservations and precise parcel not inspected. A nominal consideration clause would not establish market value or cash sale revenue. Distinguish 1885 business activity from 1890 title transfer. |
| 1869 AME festival advertisement | Contemporary newspaper advertisement | September 25, 1869; event September 30 | VERIFIED | Image inspected. Names Mrs. Biddy Mason among ticket contacts for a festival by the ladies of the AME Church to raise building funds; advertised tickets including supper $2. VERIFIED applies to the advertisement and named role. It does not establish attendance, money collected, sole founding, incorporation or land donation. Museum surrounding prose/caption has an unrelated 1865 date; the clipping itself explicitly advertises September 30, 1869. |
| First AME — institutional founding account | Institutional history | 1872 as remembered by congregation | ATTRIBUTED | Church attributes its foundation, home meetings and donated land to Mason in 1872. This preserves institutional memory; original minutes, articles, trustee deed and donation instrument not recovered. The 1869 advertisement already documents an AME fundraising network. Distinguish congregation activity, formal organization and legal property transfer; no sole-founder or verified land-gift claim is adopted. |
Accomplishments
TAKEAWAY: Mason’s freedom, homestead, and community participation are substantial achievements. They do not depend on an unverified millionaire label or a sole-founder claim.
ACCOMPLISHMENTS
Mason’s lasting accomplishments include a court-recognized transition to freedom, an enduring Los Angeles homestead, participation in Black community fundraising and a family legacy preserved by descendants and historians. The strength of these accomplishments does not depend on an unverified millionaire label or a sole-founder claim.
Who appears in the published freedom order?
Fourteen people in the named groups
Count derived from the published freedom-order transcription: Biddy, Ellen, Ann, Harriet, and Hannah’s separately named group. Published transcription · original manuscript not independently inspected. Bars compare named persons, not households or descendants. The chart does not identify all fourteen as Mason’s relatives or claim she personally filed for everyone.
ACCOMPLISHMENT LEDGER
Dates and evidence classifications apply to the specific findings below. Economic significance is BEHI analysis; evidence limits remain attached to each entry.
| DATE / PERIOD | ACCOMPLISHMENT | ECONOMIC SIGNIFICANCE | SOURCE / LOCATOR | EVIDENCE CLASSIFICATION | EVIDENCE LIMITS |
|---|---|---|---|---|---|
| January 19, 1856 | Court-recognized protection of freedom The published order names Mason and her daughters among fourteen protected people. | Freedom provided a legal basis for later independent work and family life. | 1856 freedom order — published transcription Published order transcription; copy certified January 9, 1860. | ATTRIBUTED | Original manuscript not independently inspected. The record does not establish that Mason personally filed for all fourteen. |
| November 28, 1866 | Los Angeles homestead acquisition A memorial deed-cover reproduction names a conveyance to Biddy Mason. | Connects household stability with urban property ownership. | 1866 homestead deed — memorial reproduction Memorial reproduction; complete recorded instrument pending. | ATTRIBUTED | The reproduction is not a complete Recorder-certified deed; consideration and recording particulars require the original. |
| September 1869 | Participation in church-building fundraising The inspected advertisement names Mrs. Biddy Mason as a ticket contact for the AME festival. | Documents a specific role in community fundraising. | 1869 AME festival advertisement September 25 advertisement for the September 30 festival. | VERIFIED | The advertisement does not establish attendance, funds collected, sole founding or land donation. |
ACCOMPLISHMENT CATEGORIES
The court text protects fourteen people, including Mason and her daughters.
Paid work and land ownership created household options.
Her name appears in a contemporary fundraising notice.
THE RECORD & ITS LIMITS
The published order is dated January 19, 1856. January 21 appears as a later procedural entry; the January 28 published opinion explains the case. Do not collapse them into one event.
Beasley reports daily nursing pay and the first lots. The deed-cover reproduction gives a dated acquisition anchor. Employment, savings and consideration need their own supporting records.
Stovall’s inspected 1909 feature recounts relief, shelter, prisoner visits and church expenses. These are retrospective accounts, not an itemized contemporary donations ledger.
READING THE EVIDENCE
EVIDENCE & CONTEXT
| Source | Description | Date | Evidence Classification | Notes |
|---|---|---|---|---|
| 1856 freedom order — published transcription | Primary court record via scholarly transcription | January 19, 1856; certified January 9, 1860 | ATTRIBUTED | Text inspected. Names Biddy, Ellen, Ann and Harriet alongside Hannah and her children/grandchild, fourteen people in total. Order dated January 19; later entry January 21; copy certified January 9, 1860. Published text has an inconsistent later-hearing date and spelling variations. Original manuscript not independently inspected. The court record does not establish that Mason personally drafted or filed the petition. |
| 1856 judicial opinion — contemporary newspaper transcription | Contemporary legal account | January 28, 1856 opinion; April 5, 1856 publication | ATTRIBUTED | Text inspected. Discusses California residence, threatened removal to Texas, duress and temporary guardianships. Records a private inquiry into Mason’s wishes. Original newspaper page not inspected. Distinguish the January 28 explanation from the January 19 freedom order; no purchase price for freedom is established. |
| 1866 homestead deed — memorial reproduction | Deed-cover reproduction / acquisition lead | November 28, 1866 | ATTRIBUTED | Photograph inspected. Memorial deed cover names William M. Buffum and James F. Burns to Biddy Mason and November 28, 1866. Adjacent memorial text reports $250 and Lots 3 and 8, Block 7, Ord Survey. This is a modern memorial reproduction in a public submission, not a complete Recorder-certified deed. Full instrument, acknowledgment, recording date and book/page remain required. |
| 1909 Stovall feature — wealth and philanthropy | Historical newspaper clipping | February 12, 1909 | VERIFIED | Three clipping images inspected. Opening figure describes wealth as of 1909; continuation refers to Ellen Huddleston and relatives then controlling the $300,000 estate. VERIFIED applies to what the newspaper says, not to its valuation or an 1891 probate total. Retrospective philanthropy, nursing and migration accounts remain ATTRIBUTED. Original full page/page number still needed. |
| Beasley 1919 — family recollections and biography | Published historical account | 1919 | ATTRIBUTED | Digitized text inspected; page images checked separately. Credits Ellen Huddleston and a family Bible; reports $2.50 per day as a confinement nurse and January 15, 1891 death. The biographical page prints 1854 for freedom, inconsistent with the 1856 court text. Sales of $12,000/$44,000 and family inheritance stories lack full deed identifiers here and are not verified. Stovall passages are repeated, not independent corroboration. |
| 1869 AME festival advertisement | Contemporary newspaper advertisement | September 25, 1869; event September 30 | VERIFIED | Image inspected. Names Mrs. Biddy Mason among ticket contacts for a festival by the ladies of the AME Church to raise building funds; advertised tickets including supper $2. VERIFIED applies to the advertisement and named role. It does not establish attendance, money collected, sole founding, incorporation or land donation. Museum surrounding prose/caption has an unrelated 1865 date; the clipping itself explicitly advertises September 30, 1869. |
Economic Impact
TAKEAWAY: Mason’s economic history connects skilled work, property, and family continuity. Verified rental totals, profit, lifetime net worth, and estate valuation remain unavailable.
ECONOMIC IMPACT
Mason’s economic importance lies in the relationship between skilled labor, property and family continuity. Income could support land acquisition; land could support housing, use and future transfers. The present evidence does not supply a verified rental total, net profit, lifetime net worth or estate valuation.
Three amounts with three different meanings
$2.50 per day
Reported care-work pay · a daily rate, not a verified annual income.
$250 in 1866
Reported homestead acquisition cost · full recorded deed still needed.
$300,000 in 1909
A newspaper’s later family-wealth claim · not Mason’s 1891 net estate.
A useful interpretive path, while the original wage, savings, title, and estate accounts remain incomplete.
Amounts are attributed to the NPS biography, memorial/scholarly accounts, and inspected 1909 newspaper wording. See 1909 wealth wording and 1891 estate boundary. Economic comparison, not a scaled wealth graph: differing units, dates, and owners prevent treating these as one growth series or calculating a verified investment return.
KEY ECONOMIC INDICATORS
Each measure identifies its entity, period, source and evidence limits. Dollar amounts are nominal historical U.S. dollars. Assets, revenue, profit, transaction amounts and employment measures are distinct. “Not yet established” identifies a research gap, not zero or “not applicable.”
| MEASURE / VALUE | ENTITY / PERIOD | SOURCE / LOCATOR | CONTENT CONDITION / EVIDENCE CLASSIFICATION | INTERPRETATION / LIMITS |
|---|---|---|---|---|
| Reported daily care pay $2.50 per day | Biddy Mason’s care work Period not established in cited summary | Beasley, 1919; NPS account cited in this profile. | Documented ATTRIBUTED | Reported daily rate; days worked, annual earnings and expenses are not established. |
| Reported homestead purchase $250 | Mason homestead 1866 | Memorial deed reproduction; Los Angeles City Clerk document cited below. | Documented ATTRIBUTED | Purchase consideration, not later property value; complete original deed pending. |
| Net estate value Not yet established | Biddy Mason estate Reporting period not established | Research gap; see Evidence & Context and Receipts. | Not yet established Evidence classification: not assigned to an unresolved answer. | 1891 probate Case 14493 requires appraisal and debt reconciliation. A 1909 family-wealth report is not Mason’s 1891 estate. Research Gap: Net estate value |
For evidence-label definitions, see the Receipts evidence guide.
CHANNELS OF ECONOMIC IMPACT
The relationship is meaningful even while the cash trail remains incomplete.
Descendants’ later holdings must be separated from Mason’s own estate.
Reported charitable support requires dated amounts before totaling.
THE RECORD & ITS LIMITS
The inspected February 12, 1909 feature describes wealth at that later date and relatives then controlling it. It does not establish a $300,000 estate at Mason’s death in 1891. The newspaper amount itself is an attributed valuation.
A $250 acquisition story and a later reported sale cannot yield verified profit without matching parcels, ownership shares, improvements, expenses and transaction dates. Nominal family-deed consideration is not market value.
The complete probate inventory and accounts, Recorder instruments, assessment rolls, leases and receipts can distinguish assets from debts and personal holdings from descendants’ wealth.
READING THE EVIDENCE
ECONOMIC LEDGER
| Economic item | Reported amount | Evidence boundary |
|---|---|---|
| Care-work pay | $2.50 per day | Beasley 1919 and NPS report; no wage account or annual-income total. |
| Federal occupational tax | $10, October 30, 1862 | NPS citation; original assessment needed. Tax, not earnings or modern medical license. |
| Homestead purchase | $250, 1866 | Memorial and scholarship report; full recorded deed needed. |
| 1868 acquisition | $375 (prior research) | Unresolved Owens–Hall deed; amount held as a lead. |
| 1884 sale | $2,800 / competing $1,500 stories | Unresolved date/parcel/parties; neither verified. |
| Family-controlled wealth | $300,000 in 1909 | Inspected retrospective newspaper claim; valuation attributed; not an 1891 net estate. |
| 1891 estate | Not established | Complete inventory, debts, appraisal and accounts not inspected. |
EVIDENCE & CONTEXT
| Source | Description | Date | Evidence Classification | Notes |
|---|---|---|---|---|
| 1866 homestead deed — memorial reproduction | Deed-cover reproduction / acquisition lead | November 28, 1866 | ATTRIBUTED | Photograph inspected. Memorial deed cover names William M. Buffum and James F. Burns to Biddy Mason and November 28, 1866. Adjacent memorial text reports $250 and Lots 3 and 8, Block 7, Ord Survey. This is a modern memorial reproduction in a public submission, not a complete Recorder-certified deed. Full instrument, acknowledgment, recording date and book/page remain required. |
| 1862 federal occupational tax — underlying assessment needed | Federal tax-record citation | October 30, 1862 | ATTRIBUTED | NPS reports a $10 federal occupational tax under the category physician. Article and citation inspected; underlying assessment line and roll/page not recovered. A federal revenue category is not proof of a medical degree, modern professional licensure, earnings or profit. |
| 1868 Owens–Hall acquisition — unresolved deed | Prior scholarly deed lead | 1868 | ATTRIBUTED | Earlier research attributed four lots and $375 to an acquisition from Charles Owens and Martha Hall near Olive and Charity Streets. Exact recording citation and original instrument remain unrecovered. Preserve as an open research lead, not verified portfolio acreage or consideration; reconcile against probate and title chain. |
| 1875 Spring Street transfer — unresolved instrument | Prior deed / newspaper lead | January 2, 1875 | ATTRIBUTED | Date and parties retained from prior research; original deed and cited newspaper page not reopened. Book/page, legal description, consideration and extent of retained title remain pending. Do not merge this with a later $1,500 sale story or treat a reported price as net profit. |
| 1884 Lot 8 sale — unresolved transaction | Prior scholarly sale lead | April 7, 1884 (prior citation) | ATTRIBUTED | Full article and deed were not independently re-read in this audit. Earlier narratives also circulate an 1884 $1,500 figure. Neither amount is adopted as verified consideration. Match date, lot/block, grantor/grantee and instrument before selecting a number or calculating a return. |
| 1890 Mason–Owens deed — family transfer lead | Prior deed lead | June 20, 1890 | ATTRIBUTED | Earlier research describes a transfer to her grandsons with nominal monetary consideration and family affection. Original deed, recording locator, reservations and precise parcel not inspected. A nominal consideration clause would not establish market value or cash sale revenue. Distinguish 1885 business activity from 1890 title transfer. |
| 1891 probate — Case 14493 | Primary archival holding / file needed | 1891; administration thereafter | VERIFIED | Huntington’s own page explicitly identifies the 1891 probate case. VERIFIED applies only to the holding/case identification. Complete will, inventory, appraisal, debts, executor accounts, objections and final distribution have not been inspected. No $300,000 estate total or verified net worth follows from the locator. |
| 1909 Stovall feature — wealth and philanthropy | Historical newspaper clipping | February 12, 1909 | VERIFIED | Three clipping images inspected. Opening figure describes wealth as of 1909; continuation refers to Ellen Huddleston and relatives then controlling the $300,000 estate. VERIFIED applies to what the newspaper says, not to its valuation or an 1891 probate total. Retrospective philanthropy, nursing and migration accounts remain ATTRIBUTED. Original full page/page number still needed. |
| Beasley 1919 — family recollections and biography | Published historical account | 1919 | ATTRIBUTED | Digitized text inspected; page images checked separately. Credits Ellen Huddleston and a family Bible; reports $2.50 per day as a confinement nurse and January 15, 1891 death. The biographical page prints 1854 for freedom, inconsistent with the 1856 court text. Sales of $12,000/$44,000 and family inheritance stories lack full deed identifiers here and are not verified. Stovall passages are repeated, not independent corroboration. |
| County assessment and tax rolls | Primary archival acquisition target | 1860s–1891 | ATTRIBUTED | Earlier inquiry and repository register recovered; no delivered roll or ledger located in this audit. Establish archival custodian, parcel descriptions, assessments, payments and delinquency entries. Assessed values, taxes, market prices and net estate are different quantities. |
Timeline
TAKEAWAY: The freedom proceeding involved several distinct dates and a later certified copy. Property milestones and retrospective recollections retain their separate qualifications.
TIMELINE
The chronology separates dated documents from later recollections and unresolved transaction leads. January 19, January 21 and January 28, 1856 refer to different parts of the freedom proceeding; an 1860 certification is a later copy. Property events remain individually qualified.
Documents and milestones across the life and its memory
- 1856Freedom proceeding
January 19 order, later entry, and opinion have distinct dates.
- 1862Occupational-tax lead
NPS cites an October 30 assessment; original row still needed.
- 1866Homestead acquisition
Deed-cover reproduction is dated November 28.
- 1869 / 1872Community organization
Festival advertisement precedes remembered church organization.
- 1891Death & estate
Reported January 15 death; Probate Case 14493 is the file target.
- 1909 / 1919Family memory
Stovall and Beasley preserve later accounts, not contemporaneous estate appraisals.
Source boundaries and precise dates follow below. This visual distinguishes a legal text, tax citation, deed reproduction, advertisement, institutional recollection, and later biography. The original court and property documents remain separate from their published representations.
TIMELINE AT A GLANCE
A document, hearing and certified copy can have different dates.
Uninspected deed dates remain research leads.
1909 and 1919 accounts describe memory and descendants.
THE RECORD & ITS LIMITS
Birth in 1818 is attributed to family and institutional accounts. The order is dated January 19, 1856; its copy January 9, 1860. NPS cites a tax entry October 30, 1862. The homestead deed cover is dated November 28, 1866.
Prior research identifies a possible 1868 acquisition, January 2, 1875 sale, April 7, 1884 sale and June 20, 1890 family transfer. The inspected 1869 festival advertisement establishes community activity before FAME’s remembered 1872 organization.
Beasley’s family-Bible account reports death January 15, 1891. Huntington identifies Probate Case 14493. Stovall’s 1909 feature and Beasley’s 1919 book preserve retrospective family and community history.
READING THE EVIDENCE
EVIDENCE & CONTEXT
| Source | Description | Date | Evidence Classification | Notes |
|---|---|---|---|---|
| 1856 freedom order — published transcription | Primary court record via scholarly transcription | January 19, 1856; certified January 9, 1860 | ATTRIBUTED | Text inspected. Names Biddy, Ellen, Ann and Harriet alongside Hannah and her children/grandchild, fourteen people in total. Order dated January 19; later entry January 21; copy certified January 9, 1860. Published text has an inconsistent later-hearing date and spelling variations. Original manuscript not independently inspected. The court record does not establish that Mason personally drafted or filed the petition. |
| 1866 homestead deed — memorial reproduction | Deed-cover reproduction / acquisition lead | November 28, 1866 | ATTRIBUTED | Photograph inspected. Memorial deed cover names William M. Buffum and James F. Burns to Biddy Mason and November 28, 1866. Adjacent memorial text reports $250 and Lots 3 and 8, Block 7, Ord Survey. This is a modern memorial reproduction in a public submission, not a complete Recorder-certified deed. Full instrument, acknowledgment, recording date and book/page remain required. |
| 1862 federal occupational tax — underlying assessment needed | Federal tax-record citation | October 30, 1862 | ATTRIBUTED | NPS reports a $10 federal occupational tax under the category physician. Article and citation inspected; underlying assessment line and roll/page not recovered. A federal revenue category is not proof of a medical degree, modern professional licensure, earnings or profit. |
| 1868 Owens–Hall acquisition — unresolved deed | Prior scholarly deed lead | 1868 | ATTRIBUTED | Earlier research attributed four lots and $375 to an acquisition from Charles Owens and Martha Hall near Olive and Charity Streets. Exact recording citation and original instrument remain unrecovered. Preserve as an open research lead, not verified portfolio acreage or consideration; reconcile against probate and title chain. |
| 1875 Spring Street transfer — unresolved instrument | Prior deed / newspaper lead | January 2, 1875 | ATTRIBUTED | Date and parties retained from prior research; original deed and cited newspaper page not reopened. Book/page, legal description, consideration and extent of retained title remain pending. Do not merge this with a later $1,500 sale story or treat a reported price as net profit. |
| 1884 Lot 8 sale — unresolved transaction | Prior scholarly sale lead | April 7, 1884 (prior citation) | ATTRIBUTED | Full article and deed were not independently re-read in this audit. Earlier narratives also circulate an 1884 $1,500 figure. Neither amount is adopted as verified consideration. Match date, lot/block, grantor/grantee and instrument before selecting a number or calculating a return. |
| 1890 Mason–Owens deed — family transfer lead | Prior deed lead | June 20, 1890 | ATTRIBUTED | Earlier research describes a transfer to her grandsons with nominal monetary consideration and family affection. Original deed, recording locator, reservations and precise parcel not inspected. A nominal consideration clause would not establish market value or cash sale revenue. Distinguish 1885 business activity from 1890 title transfer. |
| 1891 probate — Case 14493 | Primary archival holding / file needed | 1891; administration thereafter | VERIFIED | Huntington’s own page explicitly identifies the 1891 probate case. VERIFIED applies only to the holding/case identification. Complete will, inventory, appraisal, debts, executor accounts, objections and final distribution have not been inspected. No $300,000 estate total or verified net worth follows from the locator. |
| 1909 Stovall feature — wealth and philanthropy | Historical newspaper clipping | February 12, 1909 | VERIFIED | Three clipping images inspected. Opening figure describes wealth as of 1909; continuation refers to Ellen Huddleston and relatives then controlling the $300,000 estate. VERIFIED applies to what the newspaper says, not to its valuation or an 1891 probate total. Retrospective philanthropy, nursing and migration accounts remain ATTRIBUTED. Original full page/page number still needed. |
| Beasley 1919 — family recollections and biography | Published historical account | 1919 | ATTRIBUTED | Digitized text inspected; page images checked separately. Credits Ellen Huddleston and a family Bible; reports $2.50 per day as a confinement nurse and January 15, 1891 death. The biographical page prints 1854 for freedom, inconsistent with the 1856 court text. Sales of $12,000/$44,000 and family inheritance stories lack full deed identifiers here and are not verified. Stovall passages are repeated, not independent corroboration. |
| 1869 AME festival advertisement | Contemporary newspaper advertisement | September 25, 1869; event September 30 | VERIFIED | Image inspected. Names Mrs. Biddy Mason among ticket contacts for a festival by the ladies of the AME Church to raise building funds; advertised tickets including supper $2. VERIFIED applies to the advertisement and named role. It does not establish attendance, money collected, sole founding, incorporation or land donation. Museum surrounding prose/caption has an unrelated 1865 date; the clipping itself explicitly advertises September 30, 1869. |
| First AME — institutional founding account | Institutional history | 1872 as remembered by congregation | ATTRIBUTED | Church attributes its foundation, home meetings and donated land to Mason in 1872. This preserves institutional memory; original minutes, articles, trustee deed and donation instrument not recovered. The 1869 advertisement already documents an AME fundraising network. Distinguish congregation activity, formal organization and legal property transfer; no sole-founder or verified land-gift claim is adopted. |
CHRONOLOGICAL RECORD
-
August 15, 1818 (attributed)
Biddy Mason — Attributed birth account
Bridget “Biddy” Mason
Beasley’s 1919 biography credits Ellen Huddleston’s family Bible for August 15, 1818, Hancock County, Georgia. Birthplace varies in other accounts; the family Bible and conflicting census rows have not been independently inspected. -
January 19, 1856
Biddy Mason — Freedom order
Bridget “Biddy” Mason
Published court text orders Mason and the other named petitioners free; the proceeding continued January 21. Certified copy dated January 9, 1860. Original archival leaf awaits inspection. -
October 30, 1862
Biddy Mason — Occupational tax entry
Bridget “Biddy” Mason
NPS identifies a $10 physician tax entry in federal assessment lists. This is a locator, not a modern medical qualification. -
November 28, 1866
Biddy Mason — Reported homestead deed
Bridget “Biddy” Mason
A deed image reproduced in a modern memorial submission names Mason as grantee; the complete original deed and consideration await verification. -
September 25, 1869
Biddy Mason — Church festival advertisement
Bridget “Biddy” Mason
Los Angeles Star advertisement names Mrs. Biddy Mason as a ticket contact for an AME fundraising festival scheduled September 30. -
1872
Biddy Mason — FAME organization account
Bridget “Biddy” Mason
The church’s retrospective history dates organization in Mason’s home to 1872. Legal organization and land-transfer records remain acquisition targets. -
January 15, 1891
Biddy Mason — Death recorded in family account
Bridget “Biddy” Mason
Beasley’s 1919 account attributes this date to Ellen Huddleston’s family Bible. Huntington identifies a related 1891 probate case; its complete inventory has not been inspected. -
February 12, 1909
Biddy Mason — Retrospective family wealth account
Bridget “Biddy” Mason
Stovall reports family wealth valued at $300,000 at the time of her 1909 article. This does not establish Mason’s personal estate at death.
Myths & Disputes
TAKEAWAY: Claims about Mason’s wealth, founding roles, quotations, and deed terms require different evidence. Later retellings do not override the documented freedom-proceeding chronology.
MYTHS & DISPUTES
The audit tests popular claims against the kind of evidence needed to support them. Mason’s significance remains clear while exact wealth, founding roles, deed terms and personal quotations are handled with precise attribution.
Four claims that need different proof
Correction map based on the inspected newspaper/book evidence and existing source register. The published freedom-order chronology takes priority over an inconsistent later 1854 reference. Exact birth details, familiar quotations, and absolute wealth or landownership rankings retain their own evidence requirements.
COMMON SOURCES OF CONFUSION
Later family wealth cannot be moved backward to her death.
A revenue classification is not a modern medical credential.
Home meetings, membership, trusteeship and land donation differ.
THE RECORD & ITS LIMITS
Do not publish a verified $300,000 death estate, modern-dollar millionaire claim, richest-woman ranking or absolute first-Black-landowner claim. Each needs a dated comparison or complete financial record.
Preserve FAME’s account as institutional attribution. The 1869 advertisement shows a pre-1872 AME network. Sole funding, donated land, a first school/orphanage and medical qualifications require additional original instruments or contemporary records.
The familiar open-hand saying is preserved through descendants and later publications; no contemporaneous autograph is identified here. Beasley repeats Stovall and also prints an inconsistent 1854 freedom date. Do not count that repetition as a second independent witness or erase contradictions.
READING THE EVIDENCE
EVIDENCE & CONTEXT
| Source | Description | Date | Evidence Classification | Notes |
|---|---|---|---|---|
| 1856 freedom order — published transcription | Primary court record via scholarly transcription | January 19, 1856; certified January 9, 1860 | ATTRIBUTED | Text inspected. Names Biddy, Ellen, Ann and Harriet alongside Hannah and her children/grandchild, fourteen people in total. Order dated January 19; later entry January 21; copy certified January 9, 1860. Published text has an inconsistent later-hearing date and spelling variations. Original manuscript not independently inspected. The court record does not establish that Mason personally drafted or filed the petition. |
| 1862 federal occupational tax — underlying assessment needed | Federal tax-record citation | October 30, 1862 | ATTRIBUTED | NPS reports a $10 federal occupational tax under the category physician. Article and citation inspected; underlying assessment line and roll/page not recovered. A federal revenue category is not proof of a medical degree, modern professional licensure, earnings or profit. |
| 1891 probate — Case 14493 | Primary archival holding / file needed | 1891; administration thereafter | VERIFIED | Huntington’s own page explicitly identifies the 1891 probate case. VERIFIED applies only to the holding/case identification. Complete will, inventory, appraisal, debts, executor accounts, objections and final distribution have not been inspected. No $300,000 estate total or verified net worth follows from the locator. |
| 1909 Stovall feature — wealth and philanthropy | Historical newspaper clipping | February 12, 1909 | VERIFIED | Three clipping images inspected. Opening figure describes wealth as of 1909; continuation refers to Ellen Huddleston and relatives then controlling the $300,000 estate. VERIFIED applies to what the newspaper says, not to its valuation or an 1891 probate total. Retrospective philanthropy, nursing and migration accounts remain ATTRIBUTED. Original full page/page number still needed. |
| Beasley 1919 — family recollections and biography | Published historical account | 1919 | ATTRIBUTED | Digitized text inspected; page images checked separately. Credits Ellen Huddleston and a family Bible; reports $2.50 per day as a confinement nurse and January 15, 1891 death. The biographical page prints 1854 for freedom, inconsistent with the 1856 court text. Sales of $12,000/$44,000 and family inheritance stories lack full deed identifiers here and are not verified. Stovall passages are repeated, not independent corroboration. |
| 1869 AME festival advertisement | Contemporary newspaper advertisement | September 25, 1869; event September 30 | VERIFIED | Image inspected. Names Mrs. Biddy Mason among ticket contacts for a festival by the ladies of the AME Church to raise building funds; advertised tickets including supper $2. VERIFIED applies to the advertisement and named role. It does not establish attendance, money collected, sole founding, incorporation or land donation. Museum surrounding prose/caption has an unrelated 1865 date; the clipping itself explicitly advertises September 30, 1869. |
| First AME — institutional founding account | Institutional history | 1872 as remembered by congregation | ATTRIBUTED | Church attributes its foundation, home meetings and donated land to Mason in 1872. This preserves institutional memory; original minutes, articles, trustee deed and donation instrument not recovered. The 1869 advertisement already documents an AME fundraising network. Distinguish congregation activity, formal organization and legal property transfer; no sole-founder or verified land-gift claim is adopted. |
| Hayes, Savage and descendant source files | Archival acquisition targets | 1856 / later recollections | ATTRIBUTED | Prior requests retained. Exact current collection/folder/item locators and complete scans not inspected; no quotation or new factual verification derived from these targets. Compare descendant recollections against dated court, deed and probate evidence. |
Claim Review & Corrections
| CLAIM / ASSERTION | HISTORICAL CLARIFICATION & CORRECTION | CLAIM STATUS | RECEIPT |
|---|---|---|---|
|
◆
Mason №11 — Freedom order and dates
“A published court-order transcription dates the adjudication of freedom for Biddy, her daughters and the other named petitioners to January 19, 1856.”
|
The transcription and later procedural dates were inspected. It identifies fourteen people and a certified copy dated January9,1860. Original manuscript not inspected; not proof that Mason drafted/filed the petition or purchased freedom. |
Attributed | |
|
◆
Mason №11 — Homestead acquisition
“The memorial deed-cover reproduction names Buffum and Burns transferring property to Biddy Mason on November 28, 1866; adjacent memorial text reports $250 and Lots3 and8, Block7.”
|
Modern reproduction visually inspected; complete recorded deed and exact book/page not recovered. The reported consideration and parcel cannot yet be promoted to verified original deed terms. |
Attributed | |
|
◆
Mason №11 — 1862 occupational tax
“NPS cites an October30,1862 $10 federal occupational tax entry for Biddy Mason under the category physician.”
|
NPS note6 and archival series inspected; assessment row not recovered. Federal tax terminology is not proof of a degree, modern medical licensure or income. |
Attributed | |
|
◆
Mason №11 — 1869 church fundraising participation
“The inspected September25,1869 Grand Festival advertisement lists Mrs. Biddy Mason among ticket contacts for AME church-building fundraising.”
|
Verification applies to the printed notice, name, purpose and advertised September30 event. It does not prove event attendance, proceeds, sole founding, incorporation or land donation. |
Verified | |
|
◆
Mason №11 — 1909 family wealth wording
“Stovall’s February12,1909 feature applies its $300,000 figure to later family-controlled wealth, not an explicitly stated1891 net probate estate.”
|
Opening and continuation clipping images inspected. The figure’s temporal scope and reported family control are verified as newspaper wording; the valuation itself remains attributed and is not an audited asset total. |
Verified | |
|
◆
Mason №11 — Unverified1891 estate total
“A verified $300,000 net estate for Biddy Mason at her1891 death is not established by the sources inspected in this audit.”
|
Huntington confirms Probate Case14493, not its asset balance. Complete inventory, debts, appraisal, accounts and distribution remain needed. Do not convert later family wealth into a personal death-estate total. |
Disputed | |
|
◆
Mason №11 — Family-source biography and death
“Beasley’s1919 account credits Ellen Huddleston and a family Bible for Mason’s family history, including a January15,1891 death date.”
|
Printed pp109–110 visually inspected. Family Bible not independently inspected. The same biography contains an inconsistent1854 freedom date and transaction claims without complete deed locators; preserve attribution and contradictions. |
Attributed | |
|
◆
Mason №11 — Church founding and property boundary
“FAME’s institutional history attributes1872 organization and support to Mason; the1869 advertisement separately documents her earlier AME fundraising participation.”
|
Current church memory is attributed. Earlier congregation activity, formal organization, trustee title and a personal land donation require separate records. The present evidence does not establish sole founding or a verified gift deed. |
Attributed | |
|
◆
Mason №11 — Later deed chain remains open
“The1868,1875,1884 and1890 property transactions retained from prior research remain acquisition leads pending complete recorded instruments.”
|
Prior citations retained without claiming original reinspection. Reconcile grantor/grantee, lot/block, date, consideration and reserved rights. Nominal family consideration is not market value or cash profit. |
Attributed |
Legacy
TAKEAWAY: Mason’s legacy joins skilled labor, urban ownership, family education, and community care. Descendants and later historians also played essential roles in preserving her story.
LEGACY
Mason’s legacy links Black women’s skilled labor, urban ownership, family education and community care. It also includes the work of people who preserved her history: Ellen Huddleston, Kate Bradley Stovall, Delilah Beasley, Miriam Matthews, later scholars and public artists. The memorial on Spring Street makes that history visible at the homestead site.
How Mason’s history was preserved
Family testimony
Ellen Huddleston and later descendants preserved biographical details and remembered generosity.
Writers & archivists
Stovall, Beasley, Matthews, and later researchers carried the history into print and collections.
Public place
The Spring Street memorial makes the homestead’s history visible within the modern city.
Sources: inspected Stovall and Beasley accounts and the Conservancy’s memorial history. BEHI analysis: each stage preserves a different kind of evidence. A descendant recollection, newspaper valuation, and memorial deed image should not be treated as interchangeable originals.
CHANNELS OF LEGACY
Inherited property and later investments require dated ownership distinctions.
Institutional traditions are sources with their own provenance.
Memorial art interprets historical records for visitors.
THE RECORD & ITS LIMITS
A court copy, newspaper portrait, descendant account and property instrument each preserve a different aspect of Mason’s life. Their differences make the biography richer and more accountable.
The Conservancy identifies the park and de Bretteville’s timeline artwork at 333 South Spring Street. A modern depiction of a deed is valuable for public history, while the full recorded deed remains the title authority.
Complete probate and deed records can clarify the value and disposition of assets. Tax rolls, church records and descendant litigation can explain how holdings and institutions changed after Mason’s lifetime.
READING THE EVIDENCE
EVIDENCE & CONTEXT
| Source | Description | Date | Evidence Classification | Notes |
|---|---|---|---|---|
| 1891 probate — Case 14493 | Primary archival holding / file needed | 1891; administration thereafter | VERIFIED | Huntington’s own page explicitly identifies the 1891 probate case. VERIFIED applies only to the holding/case identification. Complete will, inventory, appraisal, debts, executor accounts, objections and final distribution have not been inspected. No $300,000 estate total or verified net worth follows from the locator. |
| 1909 Stovall feature — wealth and philanthropy | Historical newspaper clipping | February 12, 1909 | VERIFIED | Three clipping images inspected. Opening figure describes wealth as of 1909; continuation refers to Ellen Huddleston and relatives then controlling the $300,000 estate. VERIFIED applies to what the newspaper says, not to its valuation or an 1891 probate total. Retrospective philanthropy, nursing and migration accounts remain ATTRIBUTED. Original full page/page number still needed. |
| Beasley 1919 — family recollections and biography | Published historical account | 1919 | ATTRIBUTED | Digitized text inspected; page images checked separately. Credits Ellen Huddleston and a family Bible; reports $2.50 per day as a confinement nurse and January 15, 1891 death. The biographical page prints 1854 for freedom, inconsistent with the 1856 court text. Sales of $12,000/$44,000 and family inheritance stories lack full deed identifiers here and are not verified. Stovall passages are repeated, not independent corroboration. |
| Hayes, Savage and descendant source files | Archival acquisition targets | 1856 / later recollections | ATTRIBUTED | Prior requests retained. Exact current collection/folder/item locators and complete scans not inspected; no quotation or new factual verification derived from these targets. Compare descendant recollections against dated court, deed and probate evidence. |
| Biddy Mason Memorial Park — public history | Institutional site documentation | Modern memorial | VERIFIED | Institutional site identifies the park, address and memorial artwork. VERIFIED applies to this modern commemorative place. Memorial narrative is not a replacement for the complete historical deeds or court record; no first-landowner ranking or historical net worth is established. |
| Portrait — 1909 newspaper reproduction | Visual record | Published February 12, 1909; exposure date unknown | VERIFIED | Image visually inspected; newspaper caption identifies Mason. Historical photograph published in 1909: underlying U.S. publication is public domain. Photographer and exposure date unknown. Newspaper portrait is published on this Profile with Homestead Museum reproduction credit; NPS version retained for comparison. No date, photographer or AI reconstruction is invented. |
Company Records
TAKEAWAY: The register concerns Mason’s personal enterprise and property; no separate incorporated company is established. Owens-family ventures and First AME property must be tracked independently.
COMPANY RECORDS
For Mason, this section documents personal enterprise, property and associated institutions. No separately incorporated “Biddy Mason company” has been established in this audit. Her personal assets, the Owens family’s livery and property ventures, and First AME’s institutional property must be tracked separately.
Keep three ownership records separate
Mason personally
Care-work income, deeds, taxes, leases, and probate concern her own enterprise and assets.
Owens family ventures
Business operations require dated partnership, lease, and title evidence before assigning their earnings to Mason.
First AME institution
Minutes, corporate filings, trustees’ deeds, and expenses establish a different institutional record.
Entity map based on the property leads, Probate Case 14493, and First AME institutional history. No incorporated Mason company is established. A business operating on family land does not prove she owned the business; a church meeting at her home does not itself establish a church land conveyance. Category-specific records follow below.
Grantor, grantee, parcel and reserved rights define ownership.
Assessment, lease and probate schedules answer different questions.
A church deed or corporate filing is distinct from a home meeting.
THE RECORD & ITS LIMITS
Prioritize the complete 1866 deed, then reconcile 1868, 1875, 1884 and 1890 leads with Recorder indexes. Record execution and recording dates separately; retain lot and block descriptions.
An Owens business operating on family land does not prove Mason owned the business or received all its earnings. Match leases, title, partnerships and dated advertisements before assigning revenue.
Probate Case 14493 is the key estate target. AME minutes, incorporation papers, trustees’ deeds and expense records can distinguish institutional founding, legal title and personal assistance.
READING THE EVIDENCE
EVIDENCE & CONTEXT
| Source | Description | Date | Evidence Classification | Notes |
|---|---|---|---|---|
| 1866 homestead deed — memorial reproduction | Deed-cover reproduction / acquisition lead | November 28, 1866 | ATTRIBUTED | Photograph inspected. Memorial deed cover names William M. Buffum and James F. Burns to Biddy Mason and November 28, 1866. Adjacent memorial text reports $250 and Lots 3 and 8, Block 7, Ord Survey. This is a modern memorial reproduction in a public submission, not a complete Recorder-certified deed. Full instrument, acknowledgment, recording date and book/page remain required. |
| 1868 Owens–Hall acquisition — unresolved deed | Prior scholarly deed lead | 1868 | ATTRIBUTED | Earlier research attributed four lots and $375 to an acquisition from Charles Owens and Martha Hall near Olive and Charity Streets. Exact recording citation and original instrument remain unrecovered. Preserve as an open research lead, not verified portfolio acreage or consideration; reconcile against probate and title chain. |
| 1875 Spring Street transfer — unresolved instrument | Prior deed / newspaper lead | January 2, 1875 | ATTRIBUTED | Date and parties retained from prior research; original deed and cited newspaper page not reopened. Book/page, legal description, consideration and extent of retained title remain pending. Do not merge this with a later $1,500 sale story or treat a reported price as net profit. |
| 1884 Lot 8 sale — unresolved transaction | Prior scholarly sale lead | April 7, 1884 (prior citation) | ATTRIBUTED | Full article and deed were not independently re-read in this audit. Earlier narratives also circulate an 1884 $1,500 figure. Neither amount is adopted as verified consideration. Match date, lot/block, grantor/grantee and instrument before selecting a number or calculating a return. |
| 1890 Mason–Owens deed — family transfer lead | Prior deed lead | June 20, 1890 | ATTRIBUTED | Earlier research describes a transfer to her grandsons with nominal monetary consideration and family affection. Original deed, recording locator, reservations and precise parcel not inspected. A nominal consideration clause would not establish market value or cash sale revenue. Distinguish 1885 business activity from 1890 title transfer. |
| 1891 probate — Case 14493 | Primary archival holding / file needed | 1891; administration thereafter | VERIFIED | Huntington’s own page explicitly identifies the 1891 probate case. VERIFIED applies only to the holding/case identification. Complete will, inventory, appraisal, debts, executor accounts, objections and final distribution have not been inspected. No $300,000 estate total or verified net worth follows from the locator. |
| First AME — institutional founding account | Institutional history | 1872 as remembered by congregation | ATTRIBUTED | Church attributes its foundation, home meetings and donated land to Mason in 1872. This preserves institutional memory; original minutes, articles, trustee deed and donation instrument not recovered. The 1869 advertisement already documents an AME fundraising network. Distinguish congregation activity, formal organization and legal property transfer; no sole-founder or verified land-gift claim is adopted. |
| County assessment and tax rolls | Primary archival acquisition target | 1860s–1891 | ATTRIBUTED | Earlier inquiry and repository register recovered; no delivered roll or ledger located in this audit. Establish archival custodian, parcel descriptions, assessments, payments and delinquency entries. Assessed values, taxes, market prices and net estate are different quantities. |
| Hayes, Savage and descendant source files | Archival acquisition targets | 1856 / later recollections | ATTRIBUTED | Prior requests retained. Exact current collection/folder/item locators and complete scans not inspected; no quotation or new factual verification derived from these targets. Compare descendant recollections against dated court, deed and probate evidence. |
ARCHIVAL CERTIFICATION & PUBLIC RECORD INTEGRITY
All company records presented in this repository have been cataloged according to the BEHI Company Records Classification System. Documents marked as Primary Sources are drawn from certified state and county archives, corporate filings, and recognized institutional repositories. Where physical scans are currently in the acquisition pipeline, verified archival metadata, source citations, and holding locators are provided to facilitate scholarly research.
| Document & ID | Evidence Type | Date | Description & Location | Source Repository | Action |
|---|---|---|---|---|---|
|
Mason №11 — 1856 freedom order — published transcription
BEHI-P011-S01
Bridget “Biddy” Mason
|
Primary Archival
Legal & Regulatory
|
January 19, 1856; certified January 9, 1860 |
Text inspected. Names Biddy, Ellen, Ann and Harriet alongside Hannah and her children/grandchild, fourteen people in total. Order dated J...
|
||
|
Mason №11 — 1856 judicial opinion — contemporary newspaper transcription
BEHI-P011-S02
Bridget “Biddy” Mason
|
Primary Archival
Legal & Regulatory
|
January 28, 1856 opinion; April 5, 1856 publication |
Text inspected. Discusses California residence, threatened removal to Texas, duress and temporary guardianships. Records a private inquir...
|
||
|
Mason №11 — 1866 homestead deed — memorial reproduction
BEHI-P011-S03
Bridget “Biddy” Mason
|
Primary Archival
Ownership & Property
|
November 28, 1866 |
Photograph inspected. Memorial deed cover names William M. Buffum and James F. Burns to Biddy Mason and November 28, 1866. Adjacent memor...
|
||
|
Mason №11 — 1862 federal occupational tax — underlying assessment needed
BEHI-P011-S04
Bridget “Biddy” Mason
|
Primary Archival
Financial
|
October 30, 1862 |
NPS reports a $10 federal occupational tax under the category physician. Article and citation inspected; underlying assessment line and r...
|
||
|
Mason №11 — 1860 census — household identity and birthplace
BEHI-P011-S05
Bridget “Biddy” Mason
|
Primary Archival
Reports & Correspondence
|
1860 |
Institutional identification inspected; original census row not transcribed in this audit. Search Bridget Mason, Biddy Mason and Bridget ...
|
||
|
Mason №11 — 1870 and 1880 census — property and identity
BEHI-P011-S06
Bridget “Biddy” Mason
|
Primary Archival
Ownership & Property
|
1870 / 1880 |
Prior scholarship reports inconsistent Mississippi/Georgia birthplace entries. Original images not inspected here. Obtain household pages...
|
||
|
Mason №11 — 1868 Owens–Hall acquisition — unresolved deed
BEHI-P011-S07
Bridget “Biddy” Mason
|
Primary Archival
Ownership & Property
|
1868 |
Earlier research attributed four lots and $375 to an acquisition from Charles Owens and Martha Hall near Olive and Charity Streets. Exact...
|
||
|
Mason №11 — 1875 Spring Street transfer — unresolved instrument
BEHI-P011-S08
Bridget “Biddy” Mason
|
Primary Archival
Contracts & Transactions
|
January 2, 1875 |
Date and parties retained from prior research; original deed and cited newspaper page not reopened. Book/page, legal description, conside...
|
||
|
Mason №11 — 1884 Lot 8 sale — unresolved transaction
BEHI-P011-S09
Bridget “Biddy” Mason
|
Primary Archival
Contracts & Transactions
|
April 7, 1884 (prior citation) |
Full article and deed were not independently re-read in this audit. Earlier narratives also circulate an 1884 $1,500 figure. Neither amou...
|
||
|
Mason №11 — 1890 Mason–Owens deed — family transfer lead
BEHI-P011-S10
Bridget “Biddy” Mason
|
Primary Archival
Ownership & Property
|
June 20, 1890 |
Earlier research describes a transfer to her grandsons with nominal monetary consideration and family affection. Original deed, recording...
|
||
|
Mason №11 — 1891 probate — Case 14493
BEHI-P011-S11
Bridget “Biddy” Mason
|
Primary Archival
Legal & Regulatory
|
1891; administration thereafter |
Huntington’s own page explicitly identifies the 1891 probate case. VERIFIED applies only to the holding/case identification. Complete wil...
|
Los Angeles Probate: Second Series, Case14493
|
|
|
Mason №11 — 1909 Stovall feature — wealth and philanthropy
BEHI-P011-S12
Bridget “Biddy” Mason
|
Primary Archival
Reports & Correspondence
|
February 12, 1909 |
Three clipping images inspected. Opening figure describes wealth as of 1909; continuation refers to Ellen Huddleston and relatives then c...
|
||
|
Mason №11 — Beasley 1919 — family recollections and biography
BEHI-P011-S13
Bridget “Biddy” Mason
|
Primary Archival
Reports & Correspondence
|
1919 |
Digitized text inspected; page images checked separately. Credits Ellen Huddleston and a family Bible; reports $2.50 per day as a confine...
|
||
|
Mason №11 — Hayden 1989 — property research framework
BEHI-P011-S14
Bridget “Biddy” Mason
|
Primary Archival
Ownership & Property
|
Fall 1989 |
Bibliographic identity and prior research trail retained. Complete article/footnotes were not re-inspected from the publisher in this aud...
|
||
|
Mason №11 — 1869 AME festival advertisement
BEHI-P011-S15
Bridget “Biddy” Mason
|
Primary Archival
Financial
|
September 25, 1869; event September 30 |
Image inspected. Names Mrs. Biddy Mason among ticket contacts for a festival by the ladies of the AME Church to raise building funds; adv...
|
||
|
Mason №11 — First AME — institutional founding account
BEHI-P011-S16
Bridget “Biddy” Mason
|
Primary Archival
Formation & Governance
|
1872 as remembered by congregation |
Church attributes its foundation, home meetings and donated land to Mason in 1872. This preserves institutional memory; original minutes,...
|
||
|
Mason №11 — County assessment and tax rolls
BEHI-P011-S17
Bridget “Biddy” Mason
|
Primary Archival
Financial
|
1860s–1891 |
Earlier inquiry and repository register recovered; no delivered roll or ledger located in this audit. Establish archival custodian, parce...
|
||
|
Mason №11 — Hayes, Savage and descendant source files
BEHI-P011-S18
Bridget “Biddy” Mason
|
Primary Archival
Reports & Correspondence
|
1856 / later recollections |
Prior requests retained. Exact current collection/folder/item locators and complete scans not inspected; no quotation or new factual veri...
|
||
|
Mason №11 — Biddy Mason Memorial Park — public history
BEHI-P011-S19
Bridget “Biddy” Mason
|
Primary Archival
Reports & Correspondence
|
Modern memorial |
Institutional site identifies the park, address and memorial artwork. VERIFIED applies to this modern commemorative place. Memorial narra...
|
||
|
Mason №11 — Portrait — 1909 newspaper reproduction
BEHI-P011-S20
Bridget “Biddy” Mason
|
Primary Archival
Reports & Correspondence
|
Published February 12, 1909; exposure date unknown |
Image visually inspected; newspaper caption identifies Mason. Historical photograph published in 1909: underlying U.S. publication is pub...
|
No verified records are currently published in this category.
Receipts
TAKEAWAY: Mason’s evidence connects legal freedom with property and community history. Original title, financial, and probate questions remain visible alongside the documented findings.
RECEIPTS & EVIDENCE
HOW TO READ THE EVIDENCE
Evidence classifications apply to individual claims. A published transcription, memorial reproduction, retrospective newspaper account and inspected original are different forms of evidence. Acquisition cost, assessed value, family wealth and net estate are not interchangeable.
Follow the claim to its source, then read the evidence status and limits. A source may support one narrow fact while leaving a larger conclusion unresolved.
Content condition describes whether the question can currently be answered. Evidence classification describes the support for a documented finding.
- Documented: A finding is presented with its source, evidence classification and limits. Documented does not automatically mean Verified.
- Not yet established: The answer remains unresolved. The entry identifies missing evidence and connects to Research Gaps.
- Not applicable: The measure does not fit the person or enterprise being examined; an explanation must state why. Missing evidence alone never makes a question not applicable.
Shared section headings remain visible. Relevance that is uncertain is treated as Not yet established until resolved.
Evidence labels and source access
- Verified
- The specific fact or record described has been checked against the cited material. Read the limit: an inspected reproduction, index or catalog entry does not mean every underlying document or broader claim has been verified.
- Attributed
- The statement is credited to the named source. Independent confirmation or the underlying original may still be outstanding.
- Disputed
- Sources or interpretations conflict. Read the competing evidence and the unresolved question.
- Estimated
- The figure is an approximation or qualified valuation, not an exact measured total. Read its basis, date and uncertainty.
- Institute Analysis
- BEHI’s interpretation or calculation from identified evidence. It is separate from what the historical source directly states.
Source access: A link may lead to an original scan, a published transcription, a finding aid, or a repository page. Use the source ID, collection, box, folder and page locator where supplied. A catalog listing or repository confirmation is not inspection of the item itself.
Images and permissions: Historical support and reproduction permission are separate questions. Read each image credit and rights note; a source link does not itself grant permission to republish.
Open questions: See Research Gaps & Open Questions below for missing records and unresolved claims.
The source registry below preserves the recovered research document by document. Linked claim receipts state what was inspected, what a source supports and what remains unresolved. Read the claim receipts: Freedom order and dates · Homestead acquisition · 1862 occupational tax · 1869 church fundraising participation · 1909 family wealth wording · Unverified1891 estate total · Family-source biography and death · Church founding and property boundary · Later deed chain remains open. VERIFIED is used narrowly for inspected wording, named participation or an identified holding—not as a blanket certification of Mason’s entire biography.
Newspaper images and Beasley pages were visually checked.
Published court texts remain distinct from original manuscripts.
Acquisition leads are plainly labeled and retained.
DOCUMENTS
Follow the claim to the right original
Freedom
Read the court text, date the order and copy separately, and seek the manuscript.
Property
Match the full instrument to parcel, parties, acknowledgment, and recording date.
Estate
Recover inventory, liabilities, accounts, and distribution—not merely the case number.
Start with freedom dates, homestead acquisition, and the unresolved estate total. Receipt workflow: the existing linked claim Receipts remain the access points for these questions. A verified source’s wording or holding identification does not independently verify every reported amount or historical interpretation.
SOURCE REGISTER & EVIDENCE LIMITS
EVIDENCE & CONTEXT
| Source | Description | Date | Evidence Classification | Notes |
|---|---|---|---|---|
| 1856 freedom order — published transcription | Primary court record via scholarly transcription | January 19, 1856; certified January 9, 1860 | ATTRIBUTED | Text inspected. Names Biddy, Ellen, Ann and Harriet alongside Hannah and her children/grandchild, fourteen people in total. Order dated January 19; later entry January 21; copy certified January 9, 1860. Published text has an inconsistent later-hearing date and spelling variations. Original manuscript not independently inspected. The court record does not establish that Mason personally drafted or filed the petition. |
| 1856 judicial opinion — contemporary newspaper transcription | Contemporary legal account | January 28, 1856 opinion; April 5, 1856 publication | ATTRIBUTED | Text inspected. Discusses California residence, threatened removal to Texas, duress and temporary guardianships. Records a private inquiry into Mason’s wishes. Original newspaper page not inspected. Distinguish the January 28 explanation from the January 19 freedom order; no purchase price for freedom is established. |
| 1866 homestead deed — memorial reproduction | Deed-cover reproduction / acquisition lead | November 28, 1866 | ATTRIBUTED | Photograph inspected. Memorial deed cover names William M. Buffum and James F. Burns to Biddy Mason and November 28, 1866. Adjacent memorial text reports $250 and Lots 3 and 8, Block 7, Ord Survey. This is a modern memorial reproduction in a public submission, not a complete Recorder-certified deed. Full instrument, acknowledgment, recording date and book/page remain required. |
| 1862 federal occupational tax — underlying assessment needed | Federal tax-record citation | October 30, 1862 | ATTRIBUTED | NPS reports a $10 federal occupational tax under the category physician. Article and citation inspected; underlying assessment line and roll/page not recovered. A federal revenue category is not proof of a medical degree, modern professional licensure, earnings or profit. |
| 1860 census — household identity and birthplace | Federal census lead | 1860 | ATTRIBUTED | Institutional identification inspected; original census row not transcribed in this audit. Search Bridget Mason, Biddy Mason and Bridget Owens, then reconcile household, age, occupation and birthplace. No census asset amount is adopted. |
| 1870 and 1880 census — property and identity | Federal census acquisition targets | 1870 / 1880 | ATTRIBUTED | Prior scholarship reports inconsistent Mississippi/Georgia birthplace entries. Original images not inspected here. Obtain household pages before claiming exact birthplace or census wealth. Census-reported real/personal estate would be a dated declaration, not audited lifetime net worth. |
| 1868 Owens–Hall acquisition — unresolved deed | Prior scholarly deed lead | 1868 | ATTRIBUTED | Earlier research attributed four lots and $375 to an acquisition from Charles Owens and Martha Hall near Olive and Charity Streets. Exact recording citation and original instrument remain unrecovered. Preserve as an open research lead, not verified portfolio acreage or consideration; reconcile against probate and title chain. |
| 1875 Spring Street transfer — unresolved instrument | Prior deed / newspaper lead | January 2, 1875 | ATTRIBUTED | Date and parties retained from prior research; original deed and cited newspaper page not reopened. Book/page, legal description, consideration and extent of retained title remain pending. Do not merge this with a later $1,500 sale story or treat a reported price as net profit. |
| 1884 Lot 8 sale — unresolved transaction | Prior scholarly sale lead | April 7, 1884 (prior citation) | ATTRIBUTED | Full article and deed were not independently re-read in this audit. Earlier narratives also circulate an 1884 $1,500 figure. Neither amount is adopted as verified consideration. Match date, lot/block, grantor/grantee and instrument before selecting a number or calculating a return. |
| 1890 Mason–Owens deed — family transfer lead | Prior deed lead | June 20, 1890 | ATTRIBUTED | Earlier research describes a transfer to her grandsons with nominal monetary consideration and family affection. Original deed, recording locator, reservations and precise parcel not inspected. A nominal consideration clause would not establish market value or cash sale revenue. Distinguish 1885 business activity from 1890 title transfer. |
| 1891 probate — Case 14493 | Primary archival holding / file needed | 1891; administration thereafter | VERIFIED | Huntington’s own page explicitly identifies the 1891 probate case. VERIFIED applies only to the holding/case identification. Complete will, inventory, appraisal, debts, executor accounts, objections and final distribution have not been inspected. No $300,000 estate total or verified net worth follows from the locator. |
| 1909 Stovall feature — wealth and philanthropy | Historical newspaper clipping | February 12, 1909 | VERIFIED | Three clipping images inspected. Opening figure describes wealth as of 1909; continuation refers to Ellen Huddleston and relatives then controlling the $300,000 estate. VERIFIED applies to what the newspaper says, not to its valuation or an 1891 probate total. Retrospective philanthropy, nursing and migration accounts remain ATTRIBUTED. Original full page/page number still needed. |
| Beasley 1919 — family recollections and biography | Published historical account | 1919 | ATTRIBUTED | Digitized text inspected; page images checked separately. Credits Ellen Huddleston and a family Bible; reports $2.50 per day as a confinement nurse and January 15, 1891 death. The biographical page prints 1854 for freedom, inconsistent with the 1856 court text. Sales of $12,000/$44,000 and family inheritance stories lack full deed identifiers here and are not verified. Stovall passages are repeated, not independent corroboration. |
| Hayden 1989 — property research framework | Scholarly secondary research | Fall 1989 | ATTRIBUTED | Bibliographic identity and prior research trail retained. Complete article/footnotes were not re-inspected from the publisher in this audit. Use its deed leads to recover originals; do not claim that all reported transactions have been independently verified. Distinguish scholarly inference, family memory and archival instruments. |
| 1869 AME festival advertisement | Contemporary newspaper advertisement | September 25, 1869; event September 30 | VERIFIED | Image inspected. Names Mrs. Biddy Mason among ticket contacts for a festival by the ladies of the AME Church to raise building funds; advertised tickets including supper $2. VERIFIED applies to the advertisement and named role. It does not establish attendance, money collected, sole founding, incorporation or land donation. Museum surrounding prose/caption has an unrelated 1865 date; the clipping itself explicitly advertises September 30, 1869. |
| First AME — institutional founding account | Institutional history | 1872 as remembered by congregation | ATTRIBUTED | Church attributes its foundation, home meetings and donated land to Mason in 1872. This preserves institutional memory; original minutes, articles, trustee deed and donation instrument not recovered. The 1869 advertisement already documents an AME fundraising network. Distinguish congregation activity, formal organization and legal property transfer; no sole-founder or verified land-gift claim is adopted. |
| County assessment and tax rolls | Primary archival acquisition target | 1860s–1891 | ATTRIBUTED | Earlier inquiry and repository register recovered; no delivered roll or ledger located in this audit. Establish archival custodian, parcel descriptions, assessments, payments and delinquency entries. Assessed values, taxes, market prices and net estate are different quantities. |
| Hayes, Savage and descendant source files | Archival acquisition targets | 1856 / later recollections | ATTRIBUTED | Prior requests retained. Exact current collection/folder/item locators and complete scans not inspected; no quotation or new factual verification derived from these targets. Compare descendant recollections against dated court, deed and probate evidence. |
| Biddy Mason Memorial Park — public history | Institutional site documentation | Modern memorial | VERIFIED | Institutional site identifies the park, address and memorial artwork. VERIFIED applies to this modern commemorative place. Memorial narrative is not a replacement for the complete historical deeds or court record; no first-landowner ranking or historical net worth is established. |
| Portrait — 1909 newspaper reproduction | Visual record | Published February 12, 1909; exposure date unknown | VERIFIED | Image visually inspected; newspaper caption identifies Mason. Historical photograph published in 1909: underlying U.S. publication is public domain. Photographer and exposure date unknown. Newspaper portrait is published on this Profile with Homestead Museum reproduction credit; NPS version retained for comparison. No date, photographer or AI reconstruction is invented. |
READING THE EVIDENCE
RESEARCH GAPS & OPEN QUESTIONS
ECONOMIC INDICATORS — MISSING EVIDENCE
Net estate value
Content condition: Not yet established. Biddy Mason estate
Reporting period not established
Evidence needed / present limit: 1891 probate Case 14493 requires appraisal and debt reconciliation. A 1909 family-wealth report is not Mason’s 1891 estate.
The review below distinguishes inspected evidence, corrections and the original records still needed.
THE RECORD & ITS LIMITS
Start with the claim, then read its evidence boundary and linked source record. A source can verify its own wording without verifying the amount or historical assertion it reports.
Highest priority: complete Probate Case 14493 and the 1866 deed, followed by the later title chain, federal assessment row, county rolls and AME legal records. Earlier requests remain active research history.
New documents will be reviewed before a classification changes. The public portrait is identified in the 1909 newspaper and credited to the Homestead Museum reproduction; other acquired visual records retain separate rights metadata.
RESEARCH UPDATES & RECONCILIATION
Research updates are recorded within the source register and research gaps above; no separate update block is presented here.
Mason №11 — Freedom order and dates
Audited Historical Assertion
A published court-order transcription dates the adjudication of freedom for Biddy, her daughters and the other named petitioners to January 19, 1856.
BEHI Academic Analysis & Research Clarification
The transcription and later procedural dates were inspected. It identifies fourteen people and a certified copy dated January9,1860. Original manuscript not inspected; not proof that Mason drafted/filed the petition or purchased freedom.
Supporting Archival Receipts & Primary Sources
HOW TO READ THE RECEIPTS & ARCHIVAL CITATIONS
Evidence linked on this page may include primary archival records, contemporary sources, repository citations, authoritative secondary scholarship, and Institute analysis. Where a physical archival holding has been identified, BEHI provides repository and locator information when available.
Cite This Profile
The Black Economic History Institute (BEHI) Digital Archive